
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Cloud Services Market Size, Share, By Service Model (Software as a Service (SaaS), Infrastructure as a Service (IaaS), and Platform as a Service (PaaS)), By Deployment Model (Public Cloud, Private Cloud, and Hybrid Cloud), By Organization Size (Large Enterprises and Small and Medium-Sized Enterprises), By End-Use Industry (Banking, Financial Services and Insurance, IT and Telecommunications, Retail and Consumer Goods, Manufacturing, Healthcare and Life Sciences, Government and Public Sector, Media and Entertainment, Energy and Utilities, Education, and Others), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-4113
Published
October, 2026
Pages
270 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
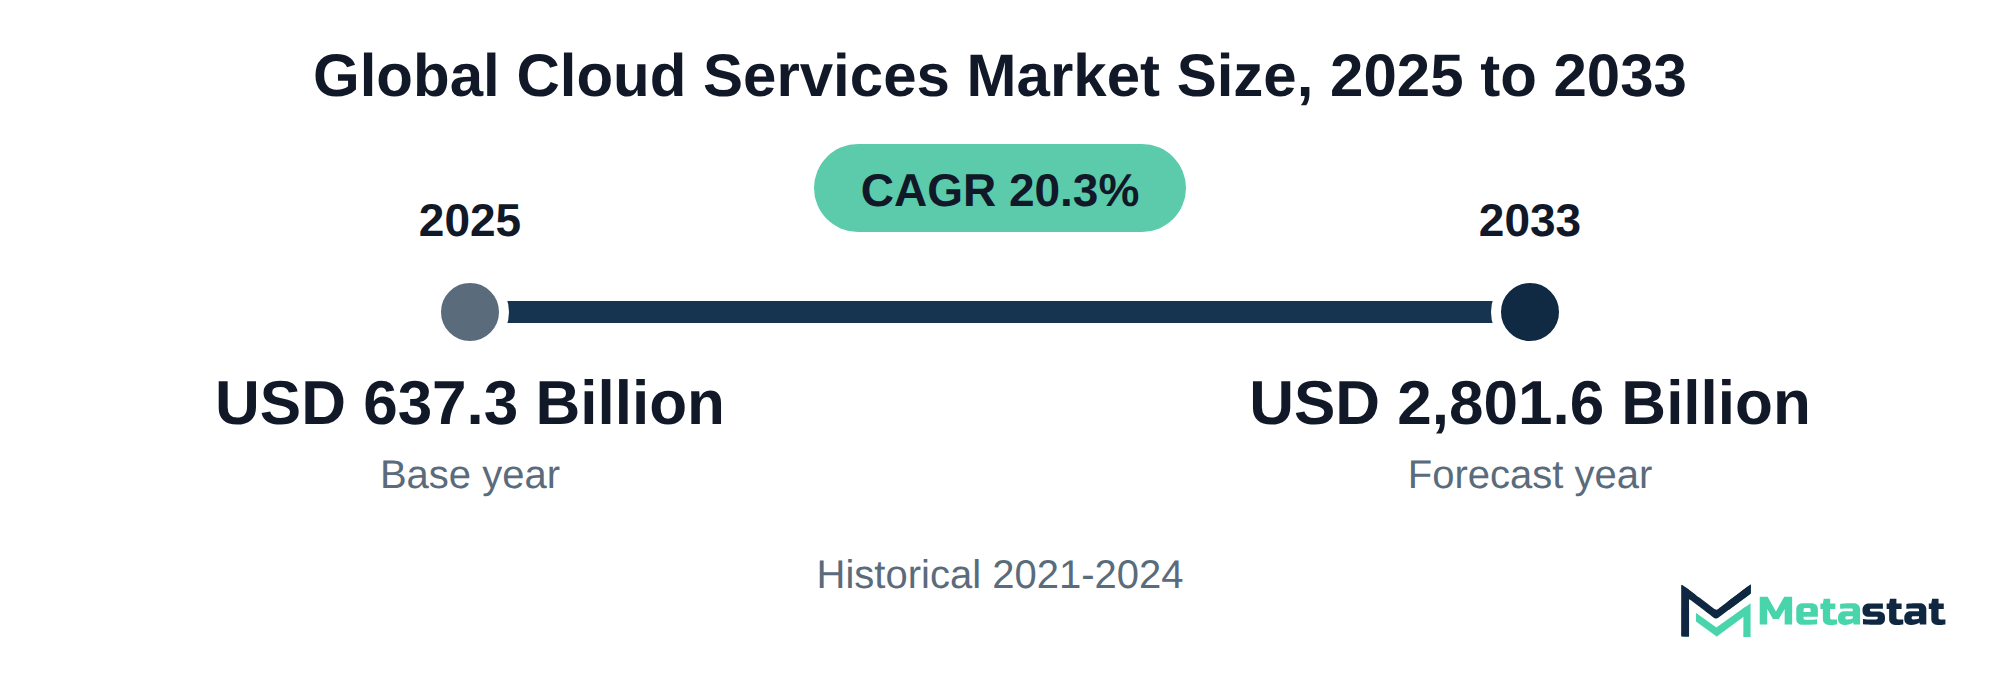
Market Valuation: Valued at $637.3 Billion in 2025, projected to reach $2,801.6 Billion by 2033 at a 20.3% CAGR.
Dominant Segment: The Software as a Service (SaaS) segment leads the market, projected to reach USD 1,298.3 billion by 2033, driven by its accessibility and lower upfront costs.
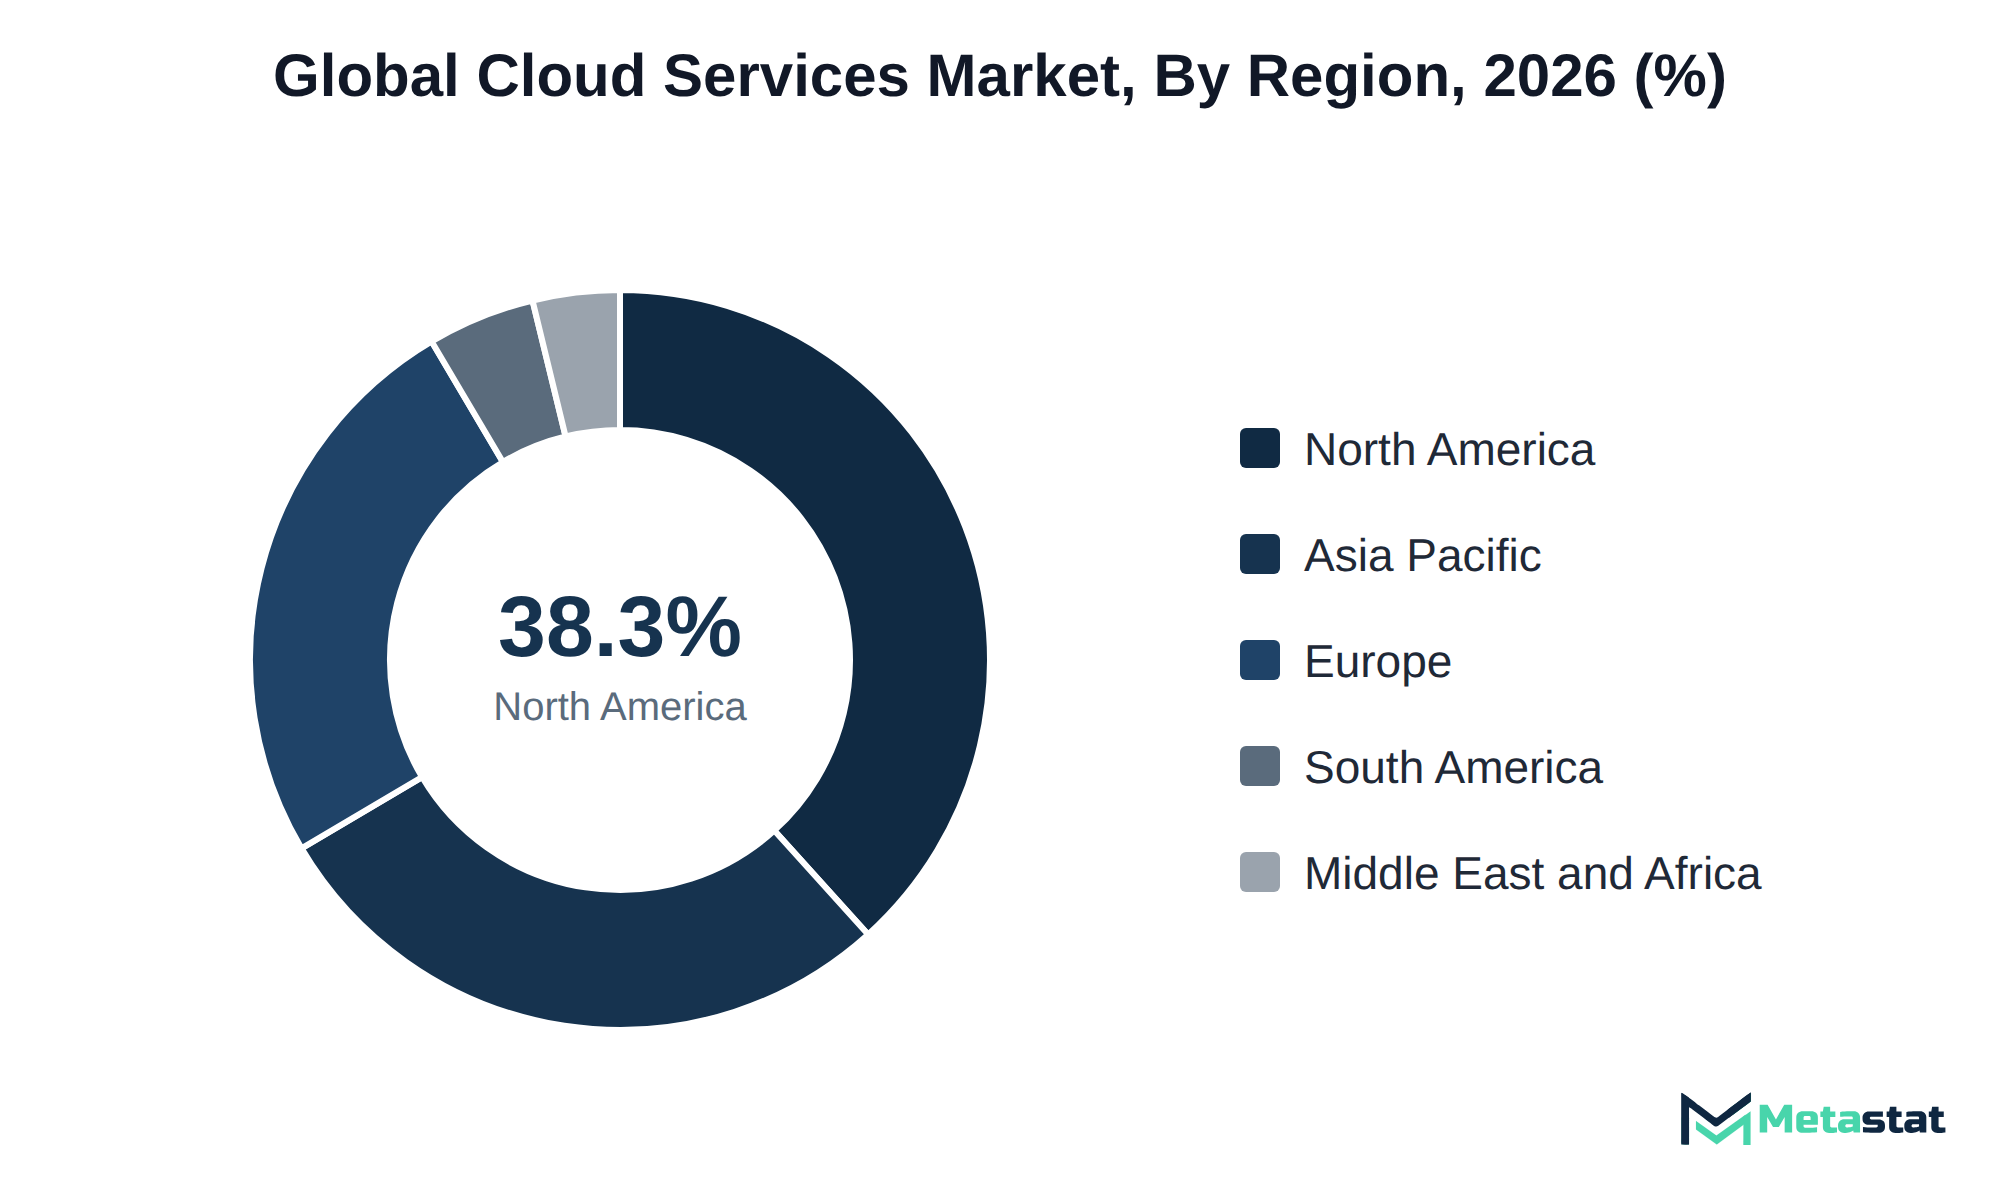
Geographic Lead: North America is the leading region, holding 38.3% of the market in 2025, with the US expected to maintain its dominance due to rapid digitalization and cloud adoption.
What's Inside: The report provides a comprehensive analysis of the Cloud Services market, covering competitive insights, market dynamics, and detailed forecasts from 2026 to 2033.
Emerging Trends: The Infrastructure as a Service (IaaS) segment is experiencing significant growth, projected to reach USD 817.5 billion by 2033, reflecting the increasing demand for scalable cloud solutions.
Investment Drivers: The shift towards public cloud adoption is a key driver, with this segment expected to reach USD 1,545.4 billion by 2033, highlighting the industry's focus on agility and innovation.
Choose Your License
Global Cloud Services Market
The global Cloud Services market was valued at USD 637.3 billion in 2025 and is projected to reach USD 2,801.6 billion by 2033, growing at a CAGR of 20.3% over the forecast period.
The Cloud Services market spans three main service models: Software as a Service (SaaS), Infrastructure as a Service (IaaS), and Platform as a Service (PaaS). Buyers invest in these solutions to enhance operational efficiency, reduce IT costs, and improve scalability. The growing reliance on digital transformation across industries drives substantial spending in this sector, with organizations seeking to leverage cloud technologies for competitive advantage.
Growth in the market is driven by a surge in demand for flexible deployment models and advanced technological solutions. Public Cloud services represent the segment with the highest value, reflecting a shift towards scalable and cost-efficient infrastructures. North America holds 38.3% of the market in 2025, with the US leading in 2026. Rapid digitalization across sectors also supports cloud adoption and further market expansion.
The Cloud Services market experiences significant growth due to increasing adoption by large enterprises, which seek to modernize their operations. The region of Asia Pacific holds a market share of 28.2%, driven by several small and medium-sized enterprises embracing cloud solutions. Demand therefore comes from both large enterprises and smaller firms.
Investments in the Cloud Services market arise from the demand for flexible, scalable, and cost-effective solutions that improve operational efficiency. Organizations increasingly rely on cloud services to enhance collaboration, enable remote work, and streamline business processes. The need for big data analytics and real-time insights drives enterprises to adopt cloud solutions across various industries.
Growth within the market is propelled by the increasing adoption of Software as a Service (SaaS), which has emerged as the segment with the highest value. The Asia Pacific region, accounting for 28.2%, follows closely, indicating a significant opportunity for service providers targeting this region.
Investment in cloud infrastructure is driven by the growing digital transformation initiatives among organizations. The ongoing shift towards public cloud adoption, expected to reach USD 1,545.4 billion by 2033, reflects the industry's emphasis on agility and innovation. Companies increasingly prioritize cloud solutions to remain competitive and responsive to market demands.
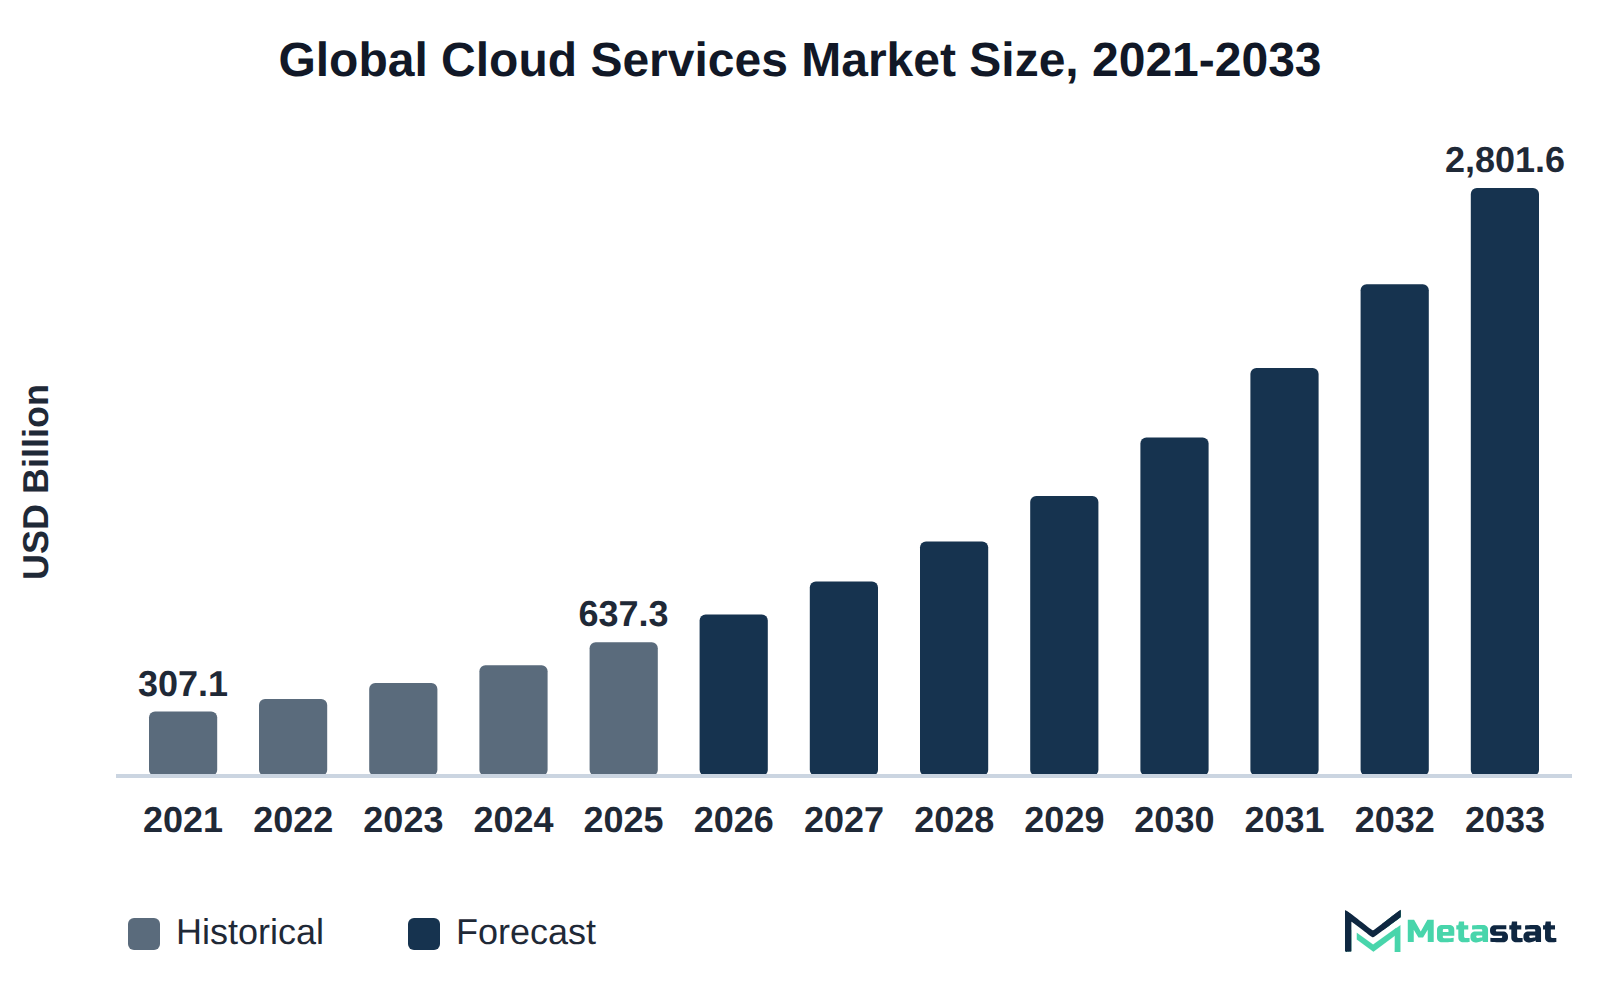
The surge in artificial intelligence (AI) training and inference has significantly reallocated cloud spending towards compute and data platforms. This shift arises from the increasing demand for high-performance computing capabilities required for complex AI workloads. The Cloud Services market anticipates substantial growth in the Infrastructure as a Service (IaaS) segment, projected to reach USD 817.5 billion by 2033, reflecting a compound annual growth rate (CAGR) of 21.1%. This growth reflects the need for scalable, high-performance computing resources that expand business AI capabilities.
Large enterprises lead this transformation, investing in advanced cloud infrastructure to support data-intensive applications and machine learning processes. The integration of enterprise artificial intelligence into various industries drives demand for enhanced data storage and processing solutions. The commercial consequence of this trend involves increased competition among cloud service providers to deliver optimized environments for AI workload management. Companies offering specialized AI compute services gain a competitive advantage in the Cloud Services market.
Contracts for sovereign and hybrid cloud solutions increasingly reshape enterprise procurement strategies. These contracts emphasize compliance with local regulations and data sovereignty requirements, reflecting a growing demand for security and control over sensitive information. The Public Cloud segment, projected to reach USD 1,545.4 billion by 2033, is expected to be central to this transformation. Such contracts typically involve tiered pricing models that align with usage, providing enterprises with flexibility in managing their cloud expenditures.
Enterprises adopting sovereign cloud solutions often encounter varied pricing structures that differ from traditional cloud offerings. Many providers implement pay-as-you-go models, allowing organizations to pay only for resources consumed. This approach contrasts with fixed pricing models where companies commit to a predetermined capacity, exposing them to potential underutilization costs. Investment from large enterprises in the Cloud Services market reflects this trend. It is projected to grow from USD 489.1 billion in 2026 to USD 1,665.8 billion by 2033, driven by the need for more tailored procurement options.
Hybrid cloud contracts present unique opportunities and challenges for procurement teams. These contracts often facilitate a combination of on-premises infrastructure and cloud services, allowing greater flexibility while optimizing costs. The market exhibits significant demand for hybrid solutions, with projections suggesting strong growth in this segment. Hybrid models help enterprises allocate resources efficiently while complying with both global and local regulations. This strategic approach enhances the competitive position of organizations operating within the Cloud Services market, positioning them for long-term success.
Small and Medium-Sized Enterprises (SMEs) face unique challenges in cloud adoption, primarily due to limited budgets and fluctuating resource requirements. Consumption pricing models have emerged as a key factor in addressing these challenges. Such pricing allows SMEs to pay only for the resources they use, thus minimizing upfront costs and aligning expenses with actual usage. This flexibility is particularly beneficial for SMEs that experience variable workloads, allowing them to scale services up or down based on their immediate needs.
The Cloud Services market reflects this trend, with the segment for Small and Medium-Sized Enterprises projected to reach USD 1,135.8 billion by 2033, growing significantly at a CAGR of 22.2%. This growth indicates that SMEs increasingly use cloud solutions to improve operational efficiency without substantial fixed costs. By adopting a FinOps framework, these organizations optimize their cloud spending through continuous tracking and analysis of resource usage, leading to better financial management and improved decision-making.
Consumption pricing and FinOps strategies help SMEs get more value from cloud services while maintaining financial control, which supports wider adoption.
Enterprises face critical decisions when selecting between Infrastructure as a Service (IaaS), Platform as a Service (PaaS), and Software as a Service (SaaS). Each service model offers distinct advantages tailored to specific business needs. The Cloud Services market reflects this diversity, with IaaS projected to reach USD 817.5 billion by 2033, highlighting its growing appeal for organizations requiring scalable infrastructure.
Organizations seeking flexibility and control gravitate toward IaaS, which provides essential virtualized computing resources over the internet. The model suits large enterprises that prioritize customization and resource management. Conversely, PaaS enables developers to create and manage applications without dealing with underlying hardware and software complexities. This model appeals to businesses focusing on rapid application development and deployment.
SaaS, with its anticipated market growth, offers an all-in-one solution for enterprises seeking ready-to-use software applications. Organizations evaluating their needs benefit from understanding the unique advantages of each service model, which optimizes operational efficiency and minimizes costs. The decision ultimately influences technology investments and shapes competitive positioning in an evolving market environment.
Small and Medium-Sized Enterprises (SMEs) increasingly adopt cloud solutions, driven by the need for cost efficiency and flexibility. The shift toward cloud services supports operational scalability, allowing these businesses to compete effectively in their respective markets. With the growing emphasis on digital transformation, SMEs prioritize technologies that enhance productivity and reduce overhead. The Cloud Services market is projected to experience significant growth in this segment, with an expected CAGR of 22.2% through 2033. This transformation encourages SMEs to invest in Software as a Service (SaaS) and Infrastructure as a Service (IaaS), enhancing their capabilities without substantial upfront costs. Increased cloud adoption leads to higher demand for innovative solutions, ultimately driving revenue growth within the market.
Growth in the Cloud Services market experiences a substantial boost from the pursuit of cost efficiency. Organizations increasingly shift to cloud solutions to optimize operational expenditures while accessing advanced technologies. This transition reduces the need for substantial on-premises infrastructure investments and lowers maintenance costs, leading to significant savings over time.
Large enterprises, in particular, leverage cloud solutions to streamline operations and enhance scalability. The ability to scale resources dynamically allows these organizations to respond swiftly to changing market demands while avoiding high fixed costs. This efficiency becomes especially valuable during economic fluctuations, where cost control takes precedence.
Investment in cloud services provides immediate financial benefits and positions organizations strategically for future growth. The market's expansion is driven by companies seeking to maintain competitive advantages through innovative and flexible technological solutions. The increasing emphasis on cost efficiency fundamentally shapes procurement strategies and influences the overall direction of the market.
Complex regulatory environments hinder widespread adoption among businesses, particularly affecting large enterprises. Increased scrutiny surrounding data privacy and security mandates influences the decision-making process, leading to slower uptake of cloud services. Companies often face challenges in aligning their operations with evolving compliance standards, resulting in smaller orders for cloud solutions. The financial burden associated with compliance measures deters investments in new technologies, further delaying cloud transition. Organizations within highly regulated sectors, including banking and healthcare, experience heightened pressure to meet stringent guidelines, affecting their agility in cloud integration. This situation impacts the growth trajectory of the cloud services market, with firms prioritizing compliance readiness over immediate technology upgrades, limiting overall demand for services in the market.
Challenges related to talent acquisition in the Cloud Services market hinder the ability of suppliers to maintain service quality and profitability. High demand for skilled professionals in cloud computing drives up costs, affecting margins across various service models. Companies face intense competition for expertise in areas including software development, data analytics, and cybersecurity. The shift towards advanced technologies necessitates continuous upskilling of the workforce, increasing operational expenditures. Suppliers respond by investing in training programs, partnering with educational institutions, and implementing attractive recruitment strategies to secure top talent. These initiatives aim to build a skilled workforce capable of supporting evolving customer demands and driving innovation. Despite these efforts, the competitive labor market continues to challenge profitability and service consistency within the market.
Small and Medium-Sized Enterprises (SMEs) represent a significant growth opportunity in the Cloud Services market, driven by the need for flexible and scalable solutions. The transition to digital platforms among SMEs accelerates demand for cloud offerings, enabling them to compete with larger entities while minimizing upfront costs. The SME segment is projected to grow at a compound annual growth rate (CAGR) of 22.2% through 2033, reaching USD 1,135.8 billion. While these businesses shift from traditional IT infrastructure to cloud-based models, they increasingly leverage Software as a Service (SaaS) and Infrastructure as a Service (IaaS) for improved operational efficiency. The cost-effective nature of these solutions contributes to their rapid adoption, equipping SMEs with the tools necessary for innovation and enhanced customer engagement within their respective industries. This trend illustrates a significant shift in the market, emphasizing the growing importance of supporting smaller enterprises in their digital transformation efforts.
The Global Cloud Services market is segmented based on Service Model, Deployment Model, Organization Size, and End-Use Industry.
Software as a Service (SaaS) segment is valued at USD 389.5 billion in 2026 and is projected to reach USD 1,298.3 billion by 2033, at a CAGR of 18.8% during the forecast period. This segment provides cloud-based software solutions that organizations use to improve operational efficiency and scalability. Predominantly used by various industries, SaaS applications serve sectors including finance, healthcare, and retail. The increasing demand for cost-effective and flexible software solutions drives growth in this segment. SaaS distinguishes itself from other service models through its rapid growth trajectory, driven by its accessibility and lower upfront costs. In contrast, Infrastructure as a Service (IaaS) and Platform as a Service (PaaS) segments exhibit different growth rates, with IaaS showing a CAGR of 21.1% and PaaS having a projected value without a specified CAGR. Overall, the SaaS segment significantly influences the Cloud Services market, reflecting broader trends in technology adoption and digital transformation.
IaaS provides virtualized computing resources over the internet, allowing organizations to manage servers, storage, and networking without the complexity of physical infrastructure. This model appeals primarily to large enterprises and IT service providers, which rely on it for flexibility and scalability. The growing demand for cloud storage and processing power fuels this segment, driven by increasing adoption of data analytics and machine learning technologies. Compared to other service models, IaaS exhibits faster growth due to its cost-effectiveness and the ability to rapidly scale resources in response to fluctuating workloads. In contrast, Software as a Service (SaaS) and Platform as a Service (PaaS) segments cater to different needs, with SaaS focused on application delivery and PaaS providing development frameworks.
Platform as a Service (PaaS) segment is expected to reach USD 685.8 billion by 2033. This segment provides a cloud computing model that allows developers to build, deploy, and manage applications without the complexity of maintaining the underlying infrastructure. PaaS is widely used by software developers and enterprises seeking rapid application development and deployment. The segment experiences growth driven by increased demand for agile development and a shift towards microservices architecture. Compared to Software as a Service (SaaS) and Infrastructure as a Service (IaaS), PaaS has a higher growth rate, with a CAGR of 18.8% through 2033. This growth reflects a broader trend of digital transformation across various industries, where organizations seek to enhance their development capabilities while minimizing operational overhead. The adoption of PaaS is essential for companies aiming to innovate rapidly and maintain competitive advantages in the market.
Public Cloud segment is valued at USD 444.8 billion in 2026 and is projected to reach USD 1,545.4 billion by 2033, at a CAGR of 19.5% during the forecast period. This segment is widely adopted by various industries for applications including data storage, hosting, and software delivery. Organizations across sectors leverage public cloud solutions to enhance operational flexibility and scalability, enabling them to adapt quickly to market changes. The primary drivers of growth in this segment include the increasing demand for remote work solutions and the need for cost-effective infrastructure. Compared to other deployment models, public cloud services provide a faster growth trajectory, with a CAGR of 19.5%, outpacing private cloud's 19.1%. This growth results from its appeal to a broader range of customers, including startups and large enterprises, seeking efficient and scalable options in the Cloud Services market.
Private Cloud segment is estimated to reach USD 658.1 billion by 2033, at a CAGR of 19.1% during the forecast period. This deployment model provides dedicated cloud resources, allowing organizations to maintain greater control over their data and applications. Large enterprises and specific industries including banking and healthcare often adopt private cloud solutions for enhanced security and compliance. Demand drivers include the increasing need for data privacy and regulatory compliance. This segment differs from the Public Cloud model, which experiences higher growth at a CAGR of 19.5%, while private cloud solutions typically incur higher costs due to dedicated infrastructure and management. The focus on security and customization makes private cloud solutions attractive to organizations that prioritize control and compliance over flexibility.
Hybrid Cloud segment is expected to reach USD 598.1 billion by 2033. This model blends public and private cloud resources, enabling organizations to maintain critical data on private servers while leveraging public cloud capabilities for less sensitive operations. Hybrid cloud solutions are particularly favored by large enterprises seeking flexibility and scalability in IT infrastructure. Demand for this segment increases, driven by enterprises striving to enhance operational efficiency and reduce costs. With a CAGR of 19.5%, Hybrid Cloud growth outpaces traditional private cloud offerings. Organizations frequently adopt this deployment model to achieve a balanced approach to cloud computing, allowing greater control over sensitive information compared to fully public models. The unique capabilities of Hybrid Cloud differentiate it from other deployment models, presenting a versatile and adaptable option for businesses across various industries.
Organizations in this segment employ cloud services primarily for enhanced scalability, flexibility, and cost-effectiveness in managing IT infrastructure. The demand for these services is driven by the increasing need for large enterprises to innovate and remain competitive in a rapidly changing market. Compared to smaller firms, this segment typically engages in larger-scale operations and has a greater capacity for investment in cloud infrastructure. This segment exhibits substantial growth potential, reflecting ongoing digital transformation within industries including banking and financial services, which is anticipated to reach a value of USD 584.7 billion by 2033.
This segment serves businesses with fewer than 500 employees, addressing the need for flexible and cost-effective SME cloud services. Rapid digital transformation drives demand, enabling these enterprises to scale operations without significant upfront investments. Compared to larger firms, small and medium-sized enterprises pursue cloud services for their agility and ability to innovate quickly. The market sees heightened interest in Software as a Service (SaaS) offerings, which provide essential tools for collaboration and productivity at lower costs. Growth in this segment stands out, reflecting a faster expansion rate than that of large enterprises, influenced by the quest for efficiency and competitive advantage. Adoption barriers include limited IT resources and expertise; however, the potential for streamlined operations and improved service delivery fuels continuous interest in these solutions.
Valued at USD 170.1 billion in 2026, this segment is projected to reach USD 584.7 billion by 2033, at a CAGR of 19.3% during the forecast period. Institutions in the banking, financial services, and insurance sectors employ cloud services to enhance operational efficiency, improve data management, and ensure compliance with regulatory requirements. The demand for advanced data analytics and risk management capabilities drives this segment forward. Compared to other segments, this area exhibits a higher focus on security and compliance due to the sensitive nature of financial data. In contrast, the retail segment, while experiencing growth, has a lower CAGR of 19.2%. Cloud services in finance address stringent regulatory standards, presenting a unique challenge not prevalent in sectors including retail.
IT and Telecommunications segment is estimated to reach USD 522.2 billion by 2033, at a CAGR of 19.2% during the forecast period. This segment enables connectivity and digital communication for businesses and consumers, using cloud solutions to handle large datasets and real-time processing. Demand in this segment is driven by the increasing need for digital transformation across various sectors, where organizations rely on cloud services to enhance operational efficiency and reduce costs. Compared to other segments, this sub-segment demonstrates a strong growth trajectory, supported by advancements in technology and the rising adoption of innovative applications. The IT and Telecommunications segment experiences distinct challenges, including security concerns and regulatory compliance, which impact swift adoption. Overall, the market benefits from the ongoing shift toward cloud-based infrastructures and services.
Retail and Consumer Goods segment is expected to reach USD 356.1 billion by 2033. This segment caters to businesses involved in selling products directly to consumers, leveraging cloud solutions for inventory management, customer relationship management, and e-commerce operations. The increasing emphasis on digital transformation drives demand, with retailers seeking innovative solutions to enhance customer experience and streamline operations. Competitive pressures prompt a shift towards cloud services that enable agile responses to market trends. Rapid adoption of e-commerce further distinguishes this segment, leading to a higher growth trajectory compared to other segments. The segment is projected to grow at a compound annual growth rate (CAGR) of 19.2%, supported by the rising integration of technology in retail strategies and the expansion of online shopping platforms. Cloud services enable these businesses to adapt to changing consumer behaviors and preferences.
The manufacturing segment is projected to grow at a CAGR of 21.7% during the forecast period. This segment involves the use of cloud services to optimize production processes, enhance supply chain management, and facilitate real-time data analysis. Key players in this sector include manufacturers of various sizes seeking solutions for increased operational efficiency and reduced costs. Technological advancements, particularly in automation and data analytics, drive this segment forward. This segment experiences faster growth due to the rapid adoption of Industry 4.0 practices, which integrate advanced technologies into manufacturing processes. The market sees rising demand for cloud-based solutions that enable manufacturers to streamline operations and improve product quality through enhanced data insights.
This segment focuses on the integration of cloud solutions in healthcare and life sciences. Organizations in this field leverage cloud services for data management, patient care optimization, and regulatory compliance. The significant push toward digital transformation drives demand, with the adoption of cloud technologies enhancing operational efficiencies and enabling better patient outcomes. Compliance with stringent healthcare regulations presents a challenge, necessitating advanced data security measures and interoperability standards. Compared to other segments, the urgency for innovation and compliance in healthcare and life sciences creates a unique demand dynamic, focusing on high-quality service and security. Growth in this area outpaces other fields, particularly due to rapid advancements in telehealth and personalized medicine, shaping the future of care delivery in the Cloud Services market.
This segment primarily addresses services provided by governmental bodies and public sector organizations. These entities employ cloud services for enhanced operational efficiency, data management, and public service delivery. Demand in this segment is driven by improved citizen engagement and operational cost-effectiveness. Regulatory compliance requires strong security and data governance frameworks, which increase service costs. Compared to other segments, the Government and Public Sector segment exhibits slower growth, influenced by stringent procurement processes and funding cycles. While sectors including retail and financial services quickly adopt innovative technologies, public sector adoption tends to lag, reflecting unique operational challenges and budget constraints. The market continues to evolve as public entities increasingly recognize the potential of cloud solutions to transform service delivery and enhance operational resilience.
Media and Entertainment serves a diverse range of content creators and distributors, including film studios, television networks, and streaming platforms. This segment focuses on delivering digital content, enhancing user experiences, and facilitating production processes through cloud-based solutions. The primary force driving this segment reflects the increasing demand for high-quality content and easy access to entertainment across multiple devices. Rapid advancements in streaming technology and content delivery networks significantly influence market dynamics, driving competition among providers to enhance service offerings. Compared to other segments, the Media and Entertainment segment experiences unique challenges related to copyright and licensing, affecting pricing and adoption rates. Entities involved in this sector require flexible and scalable solutions to accommodate fluctuating content consumption patterns, distinguishing it from other segments with more stable usage demands.
This segment focuses on the integration of cloud technologies in the Energy and Utilities sector. Key players in this domain include energy providers and utility companies that leverage cloud solutions to enhance operational efficiency, manage resources more effectively, and support renewable energy initiatives. The increasing demand for clean energy solutions and the need for real-time data analytics significantly drive growth in this segment. Adoption is influenced by regulatory pressures aimed at reducing carbon emissions and improving energy efficiency. Energy and Utilities differ from other segments in the market due to a unique focus on sustainability and regulatory compliance, along with the potential for slower growth compared to sectors including IT and Telecommunications.
Education leverages cloud services to enhance learning experiences and streamline administrative processes. Institutions adopt these services for online learning platforms, student information systems, and collaborative tools. Factors influencing growth in this segment include increasing demand for remote learning solutions and the need for scalable infrastructure to support a growing number of users. Educational organizations face unique challenges, including budget constraints and the integration of new technologies into existing systems. Unlike sectors including banking or retail, the education segment experiences varying levels of cloud adoption, driven by institutional policies and funding availability. The rise in online education initiatives positions this segment for substantial growth, contributing to the overall expansion of the cloud services market.
This sub-segment encompasses Transportation and Logistics, Hospitality, and Professional Services, addressing diverse needs across industries. Organizations in these sectors leverage cloud services to enhance operational efficiency, improve customer engagement, and facilitate data management. Demand for these services stems from the increasing emphasis on digital transformation and the growing necessity for real-time analytics. The Transportation and Logistics sector, in particular, benefits from cloud solutions that optimize supply chain management and streamline operations. In contrast to larger segments including Banking, Financial Services and Insurance, this sub-segment experiences slower growth due to varying levels of adoption and investment in technology across different industries. However, the ongoing trend toward modernization and automation drives interest in cloud services, establishing a solid foundation for future expansion. Investment in these technologies supports enhanced service delivery and operational flexibility, contributing to the overall growth within the Cloud Services market.
Based on geography, the Global Cloud Services market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Strong demand for cloud solutions in North America stems from various sectors, including banking, financial services, and insurance, driven by the need for secure and scalable IT infrastructure. The region benefits from advanced technological infrastructure and a high level of digital adoption among consumers and enterprises. Significant investment in public cloud services highlights the region's commitment to embracing digital transformation. North America accounted for 38.3% of the global market share in 2025, positioning it as a leader in the Cloud Services market. North America is projected to reach USD 993.5 billion by the end of 2033, reflecting strong growth across multiple industries, including IT, telecommunications, and retail.
Growth in the Cloud Services market in Europe is driven by increased digital transformation efforts across various industries, particularly in finance and telecommunications. Countries including Germany, France, and the UK focus on adopting cloud technologies to enhance operational efficiency and customer engagement. The region's regulatory environment encourages innovation, with initiatives aimed at modernizing information technology infrastructure. This regulatory support, combined with a preference for scalable solutions among small and medium-sized enterprises, significantly boosts demand. The market is expected to continue evolving, driven by a broad spectrum of industries leveraging cloud capabilities to streamline operations and improve service delivery.
The Asia-Pacific region accounts for 28.2% of the total Cloud Services market in 2025. Countries including China, Japan, and India drive demand, primarily due to rapid digital transformation and increased investment in IT infrastructure. The region experiences strong growth in the Software as a Service (SaaS) sector, where businesses seek scalable solutions to enhance operations. Strong interest in Infrastructure as a Service (IaaS) arises from enterprises looking to optimize costs while maintaining high performance. Government initiatives in South Korea and Australia further support the market by promoting cloud adoption among businesses. Increased internet penetration and mobile device usage across Southeast Asia further enhance the demand for cloud solutions, influencing the growth trajectory in the coming years.
Demand for the Cloud Services market in South America benefits from growing adoption among businesses in Brazil and Argentina, particularly within industries including banking, financial services, and retail. The increasing reliance on digital solutions drives organizations to seek efficient cloud-based services. Infrastructure enhancements, including investments in internet connectivity, contribute to the region's digital transformation. South America’s market share reached 4.7% in 2025, indicating a solid foundation for growth. By 2033, the region is projected to experience substantial expansion, leading to greater competition among service providers. The market’s trajectory reflects a commitment to enhancing technological capabilities across various sectors, enabling improved operational efficiencies and service delivery.
Demand for cloud solutions in the Middle East and Africa derives primarily from sectors including banking, financial services, and telecommunications. Rapid digital transformation initiatives in these industries drive growth, spurred by increasing reliance on data analytics and cloud infrastructure. Countries like Saudi Arabia and the UAE actively invest in developing smart cities and enhancing digital capabilities, further contributing to market expansion. Regulatory support aims to create a secure environment for cloud adoption, emphasizing data protection and privacy. South Africa experiences a surge in cloud adoption across various sectors, including retail and manufacturing, reflecting a growing recognition of the operational efficiencies achieved through cloud technologies. The market in this region is projected to experience significant growth by 2033.
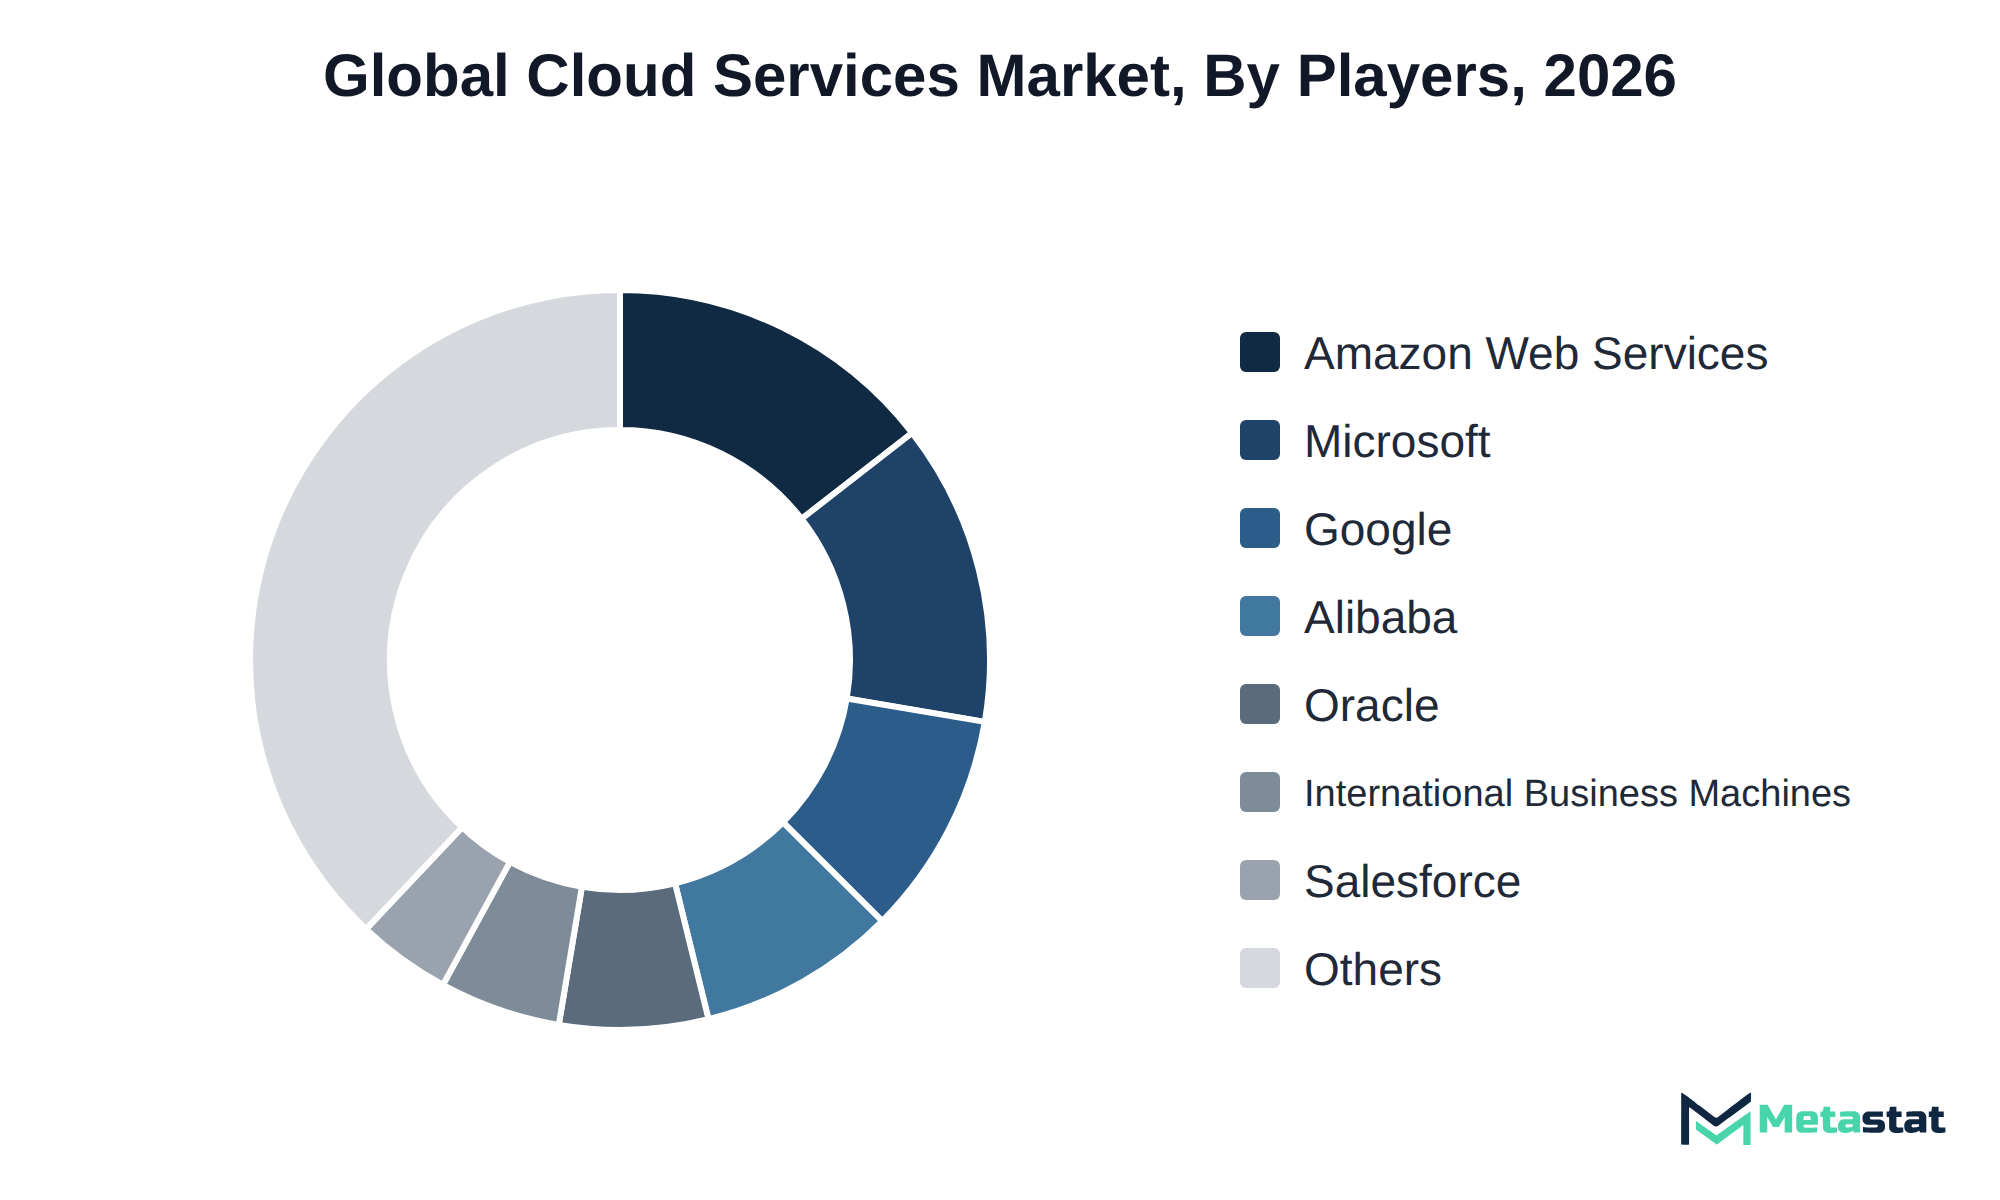
Competition in the Cloud Services market involves various strategies related to service offerings, pricing, and customer engagement. Companies differentiate themselves through service models including Software as a Service (SaaS), Infrastructure as a Service (IaaS), and Platform as a Service (PaaS). This segmentation allows buyers to select solutions that align with their specific operational requirements and budget constraints.
Pricing influences buyer decisions, alongside factors including service customization and the overall ecosystem provided by each vendor. Amazon Web Services, Inc., for example, prioritizes a broad service ecosystem tailored for enterprises, enhancing operational flexibility. Meanwhile, Salesforce, Inc. focuses on customer relationship management solutions, integrating various tools to enhance user experience and client engagement.
Companies like Alibaba Group Holding Limited leverage their strengths in e-commerce, providing extensive cloud services that cater to businesses seeking scalability and adaptability. In contrast, Oracle Corporation emphasizes database management and enterprise resource planning, targeting large organizations seeking robust data solutions and integration capabilities. Such strategic positioning enables firms to address diverse buyer needs within the evolving landscape of the Cloud Services market.
Achieving this growth relies on several key developments within the Cloud Services market. One significant factor is the increasing adoption of Software as a Service (SaaS), projected to grow significantly from USD 389.5 billion in 2026 to USD 1,298.3 billion by 2033, reflecting a compound annual growth rate of 18.8%. Another critical element is the expansion of Public Cloud services, anticipated to reach USD 1,545.4 billion by 2033, driven by a CAGR of 19.5%.
However, challenges remain that could hinder this trajectory. Economic uncertainties or shifts in regulatory frameworks could impact investment and adoption rates across various regions, particularly in North America, which represents 38.3% of the market share. Addressing these risks will be vital for sustaining growth momentum and capitalizing on the opportunities within the Cloud Services market.
By Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud
By Organization Size: Large Enterprises, Small and Medium-Sized Enterprises
By End-Use Industry: Banking, Financial Services and Insurance, IT and Telecommunications, Retail and Consumer Goods, Manufacturing, Healthcare and Life Sciences, Government and Public Sector, Media and Entertainment, Energy and Utilities, Education, Others (Transportation and Logistics, Hospitality, Professional Services)
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Cloud Services market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 20.3% from 2026 to 2033 |
|
Revenue Unit |
USD billion |
|
Segmentation |
By Service Model, Deployment Model, Organization Size, End-Use Industry, and Region |
|
By Region |
North America (By Service Model, Deployment Model, Organization Size, End-Use Industry, and Country)
|
|
Europe (By Service Model, Deployment Model, Organization Size, End-Use Industry, and Country)
|
|
|
Asia Pacific (By Service Model, Deployment Model, Organization Size, End-Use Industry, and Country)
|
|
|
South America (By Service Model, Deployment Model, Organization Size, End-Use Industry, and Country)
|
|
|
Middle East and Africa (By Service Model, Deployment Model, Organization Size, End-Use Industry, and Country)
|
Find answers to common questions about this report
The Cloud Services market size was valued at USD 637.3 billion in 2025.
The market is projected to grow at a CAGR of 20.3% during the forecast period from 2026 to 2033.
The North America Cloud Services market size is estimated to reach USD 993.5 billion by 2033.
The leading segment in the Cloud Services market is Software as a Service (SaaS), with a projected value of USD 1,298.3 billion by 2033. This segment surpasses others in growth potential, driven by increasing demand for cloud-based applications.
The pursuit of cost efficiency drives organizations to adopt cloud solutions, optimizing operational expenditures while accessing advanced technologies. the transition to digital platforms among Small and Medium-Sized Enterprises (SMEs) accelerates demand for cloud offerings, enabling them to compete effectively while minimizing upfront costs.
North America holds the dominant share of the Cloud Services market, with a projected value of USD 993.5 billion in 2033, representing 38.3 percent of the total market. This figure surpasses the shares of other regions, including Europe and Asia Pacific.
Complex regulatory environments hinder widespread adoption, particularly among large enterprises. Challenges related to talent acquisition affect suppliers' ability to maintain service quality and profitability.
Factors favoring adoption in the Cloud Services industry include the pursuit of cost efficiency and flexibility among Small and Medium-Sized Enterprises (SMEs). The shift to digital platforms enables these businesses to leverage Software as a Service (SaaS) and Infrastructure as a Service (IaaS), enhancing operational efficiency while minimizing upfront costs.
The Cloud Services market is estimated to reach a valuation of USD 2,801.6 billion by 2033.
Key players operating in the Cloud Services market include Amazon Web Services, Inc., Microsoft Corporation, Google LLC, Alibaba Group Holding Limited, Oracle Corporation, and International Business Machines Corporation.
The analysts below cover Information & Technology research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Evaluating sensor fusion reliability across harsh operating environments can be tricky without field-validated data. The study on agricultural autonomous guidance systems clearly separated stereo vision setups from automotive-grade solid-state LiDAR. We appreciated the regional infrastructure analysis, specifically around RTK network density across North America and South America. During our follow-up consultation, the MetaStat Insight team walked through tier-two perception software partnerships, giving our engineering leads a practical basis for vendor shortlisting.
Analyzing the transition from natural gas to green hydrogen in iron ore reduction requires realistic infrastructure timelines. Meta stat insight supplied a detailed regional assessment of DRI plant conversion costs and scrap metal availability in North America and Western Europe. Their report carefully examined pellet quality specs and electrical grid access constraints without making oversimplified market assumptions. The research material served as a practical reference during internal technology roadmap discussions.
Integrating zero-trust access controls across legacy electronic health record systems involves complex compliance overhead. Team produced an analysis that clearly separated identity governance and administration tools from privileged access management platforms. Their evaluation of HIPAA and GDPR compliance features across cloud native solutions gave our architecture group clear baseline criteria. The custom data request regarding biometric authentication adoption in hospital networks was returned promptly with clear documentation.
Explore related market intelligence reports worth reading alongside this one.