
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Home Fitness Equipment Market Size, Share, By Product Type (Treadmills, Exercise Bikes, Elliptical Trainers, Rowing Machines, Steppers and Climbers, Free Weights, Strength Training Machines, Weight Benches and Power Racks, Pilates Equipment, Others), By Price Range (Budget-Friendly Equipment, Mid-Range Equipment, Premium/High-End Equipment), By End-User (Male, Female), By Distribution Channel (Direct-to-Consumer Online Sales, Third-Party Online Retail, Specialty Fitness Stores, Mass Merchandisers and Sporting Goods Stores, Direct Offline Sales), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-3371
Published
October, 2026
Pages
286 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
Market Valuation: Valued at $12.8 Billion in 2025, projected to reach $20 Billion by 2033 at a 5.7% CAGR.
Dominant Segment: Treadmills lead the Home Fitness Equipment market, driven by their enduring demand among fitness enthusiasts and their effectiveness for cardiovascular exercise.
Geographic Lead: North America holds the largest market share at 37.2% in 2025, with the US expected to maintain its leadership position due to a strong fitness culture and consumer willingness to invest in quality equipment.
What's Inside: The report provides a comprehensive analysis of market dynamics, competitive landscape, and detailed forecasts covering the period from 2026 to 2033.
Emerging Trends: Connected home fitness equipment and subscription-based training models are gaining traction, enhancing user engagement and driving market growth.
Price Sensitivity: Price sensitivity remains a significant barrier to adoption, particularly among budget-conscious consumers, influencing their purchasing behaviors and preferences.
Choose Your License
Global Home Fitness Equipment Market
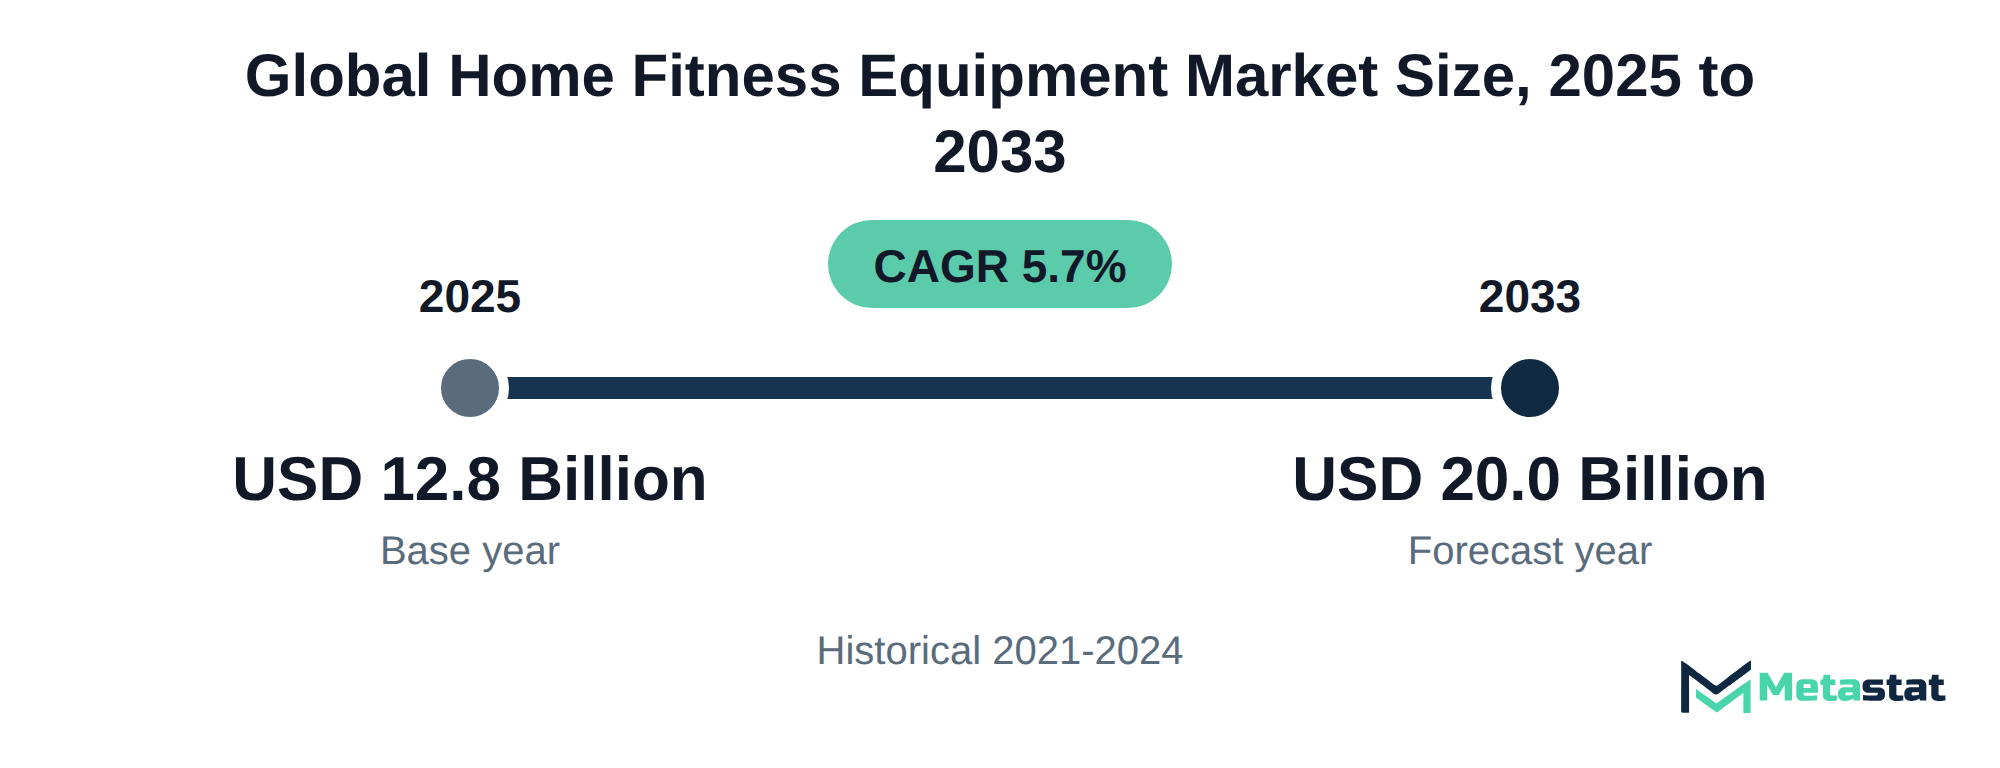
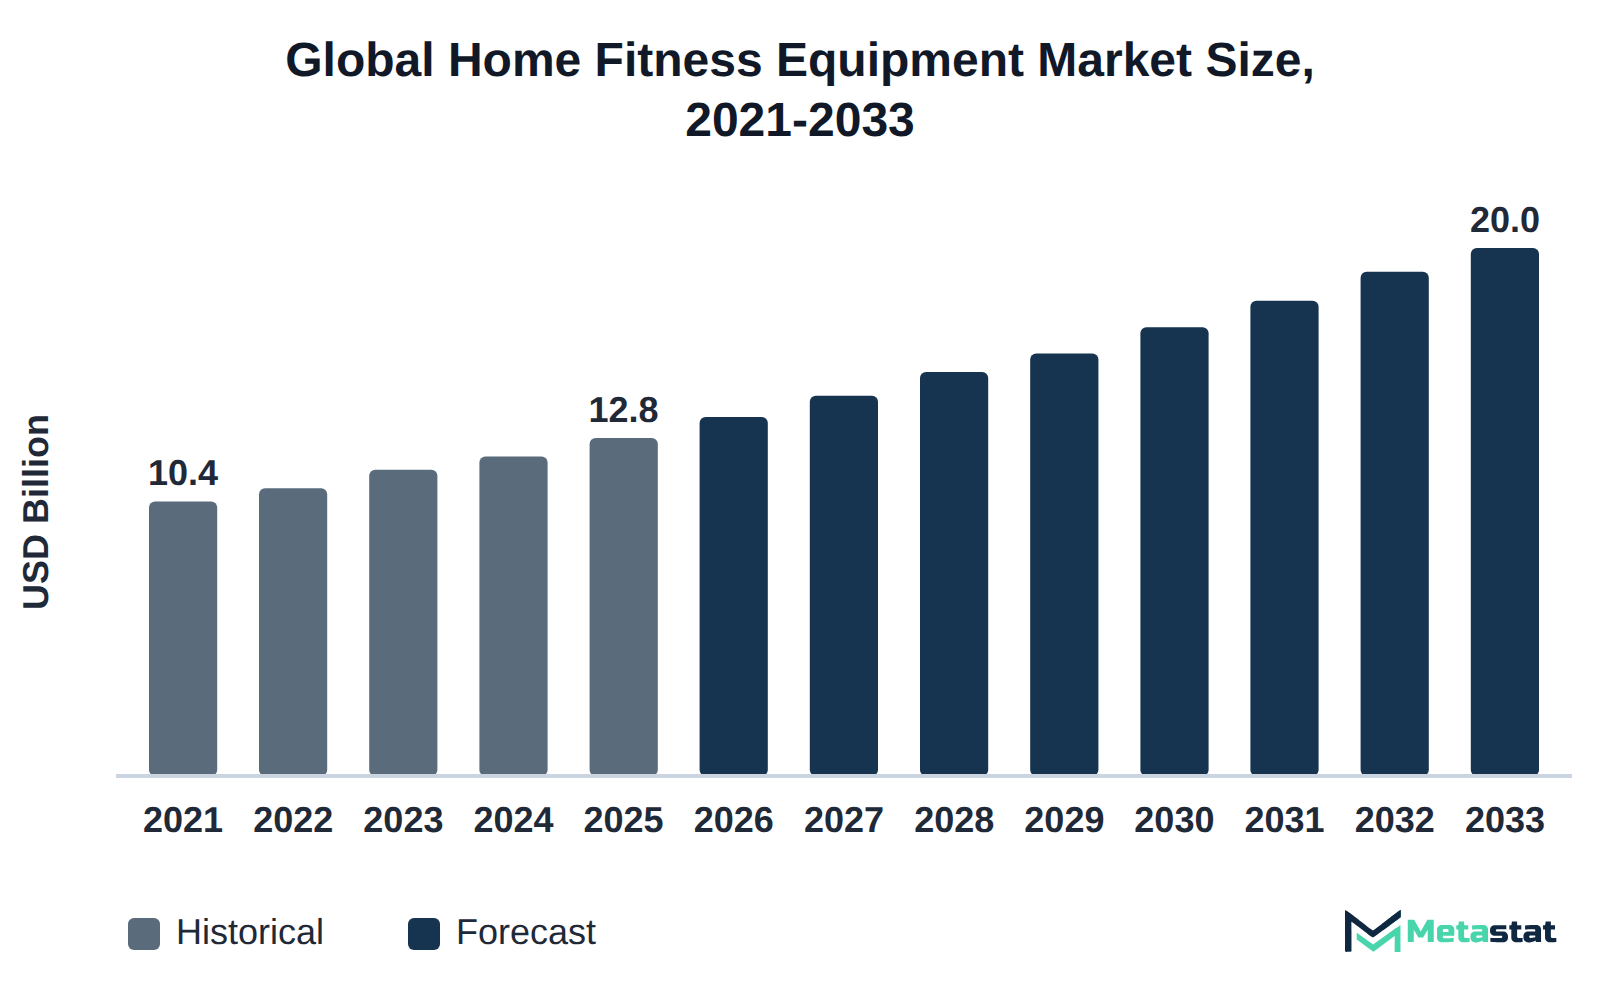
The global Home Fitness Equipment market was valued at USD 12.8 billion in 2025 and is projected to reach USD 20 billion by 2033, growing at a CAGR of 5.7% over the forecast period.
The Home Fitness Equipment market covers products designed to support exercise and physical activity within home environments. Buyers invest in this market due to the increasing focus on personal health and fitness, driven by lifestyle changes and the growing prevalence of sedentary behavior. The convenience of home-based fitness solutions significantly appeals to consumers, who seek alternative means to maintain their fitness routines without the necessity of gym memberships or external training facilities.
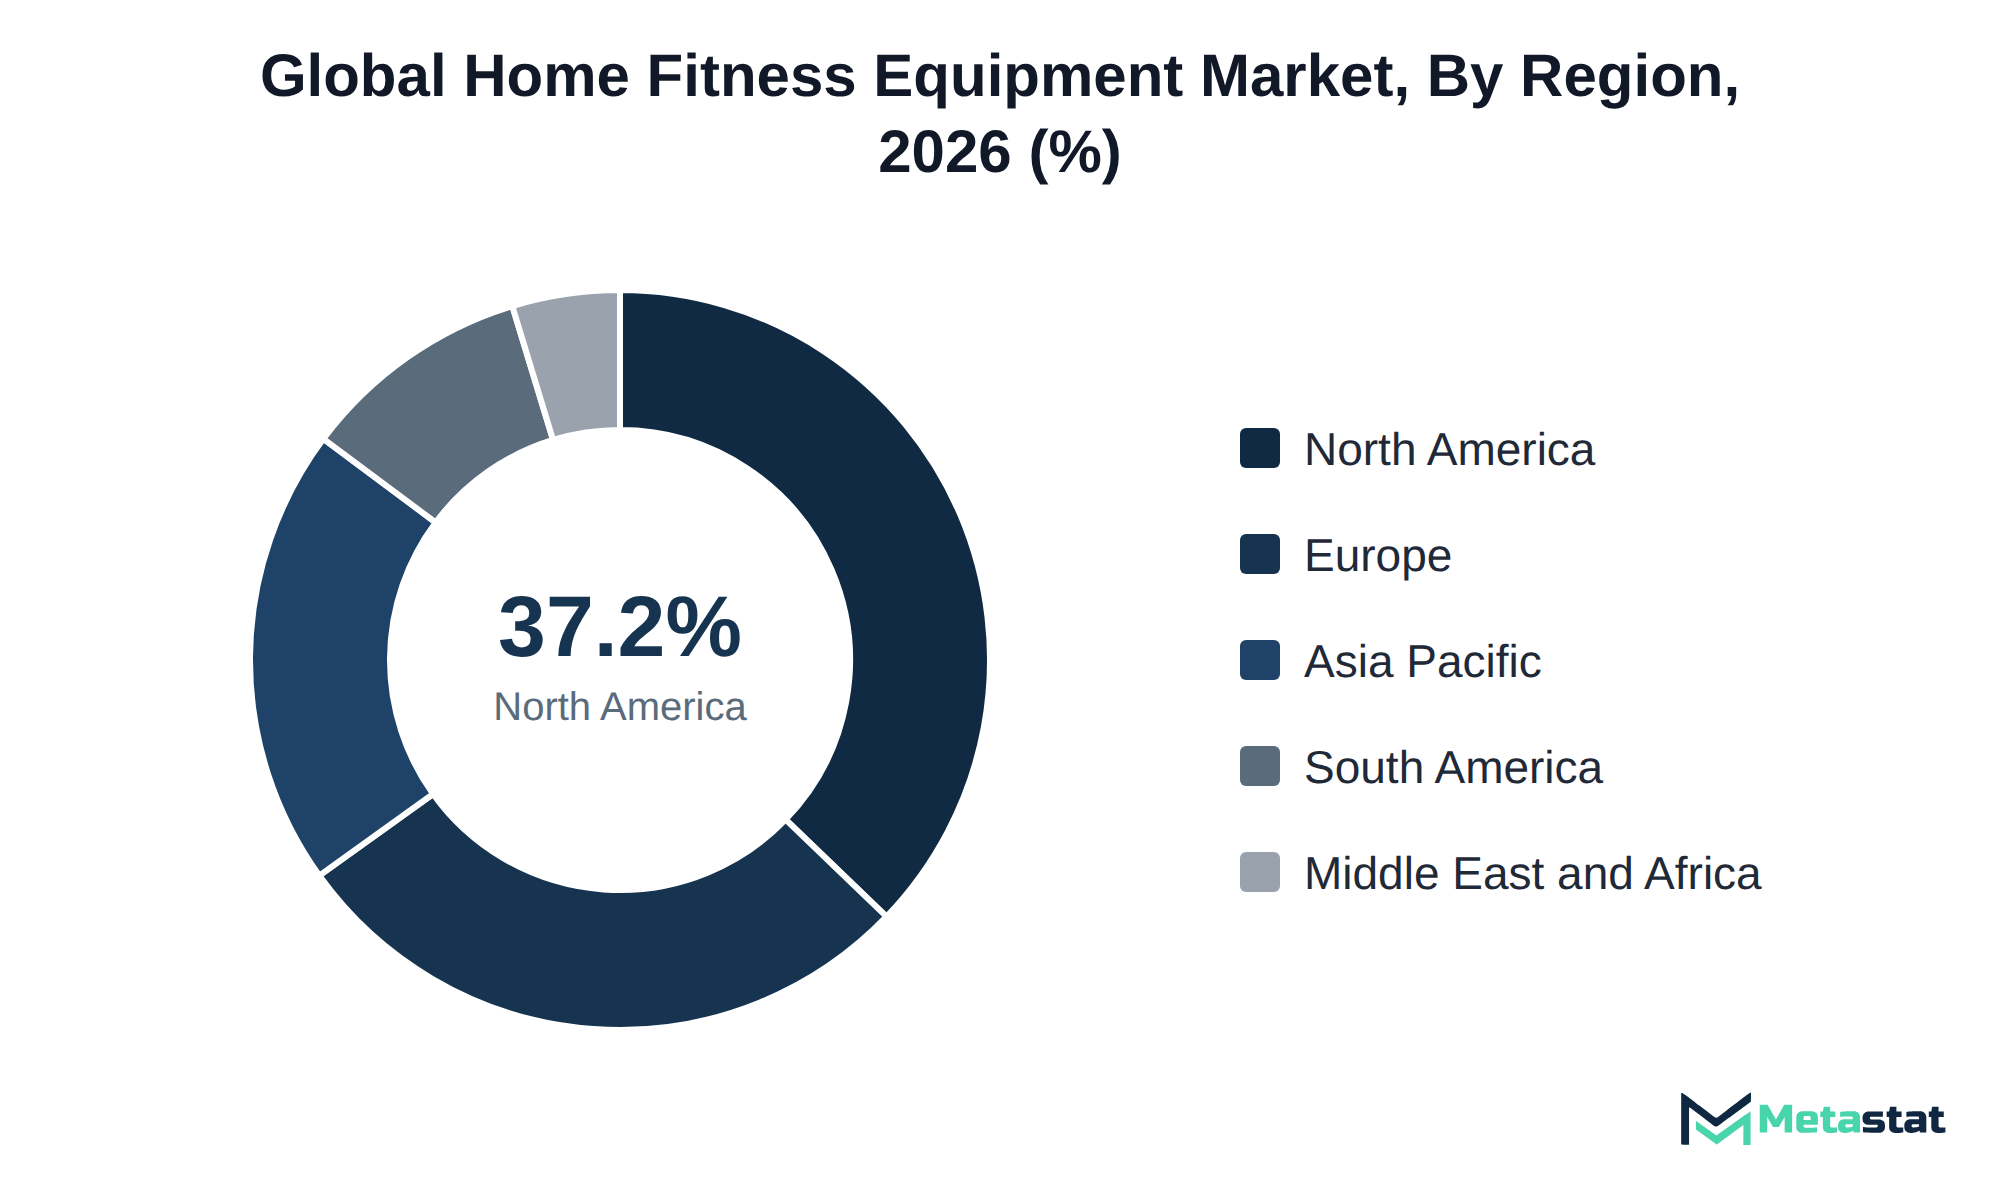
Growth within the market is propelled by the rising popularity of fitness activities and the expanding awareness of health benefits associated with regular exercise. Among the various segments, treadmills represent the largest share, reflecting their enduring demand among fitness enthusiasts. North America holds 37.2% of the market in 2025, with the US leading in 2026. This region benefits from a well-established fitness culture and a strong consumer base willing to invest in quality fitness equipment.
A primary driver of market expansion is the increasing adoption of technology-integrated fitness solutions. Consumers are drawn to smart equipment that offers connectivity, personalized training programs, and performance tracking. This trend signals a shift toward more interactive and engaging fitness experiences, enhancing overall user satisfaction and encouraging further investment in home fitness solutions.
The Home Fitness Equipment market supports various buyer groups, including fitness enthusiasts, casual users, and rehabilitation patients. Spending on fitness equipment results from an increasing awareness of health and wellness, along with a desire for convenience in achieving fitness goals. Buyers turn to home fitness solutions to save time and avoid the challenges associated with gym memberships, including travel and crowded facilities.
Growth in the market is driven by a rising demand for convenience and personalized fitness experiences. Treadmills represent the segment with the highest value, catering to a broad range of users from beginners to advanced athletes. North America holds 37.2% of the market in 2025, with the US leading in 2026, while Europe follows with a significant share, reflecting strong consumer interest in fitness and health-oriented lifestyles.
The market is expected to expand significantly throughout the forecast period, driven by innovations in technology and an increase in product offerings that meet diverse consumer needs. Enhanced connectivity features in fitness equipment, including smart technology and integrated workout programs, contribute to greater user engagement and satisfaction. These advancements strengthen the market's position within the fitness industry.
The emergence of connected home fitness equipment significantly alters consumer engagement within the Home Fitness Equipment market. This technology enables users to track performance metrics in real-time and interact with virtual fitness communities, thus enhancing motivation and adherence to workout regimens. The integration of smart devices into fitness routines has increased the appeal of in-home workouts, particularly among younger demographics who prioritize technological features.
Subscription-based training models complement this trend, providing users with access to diverse classes and personalized coaching from the comfort of their homes. The coaching element overlaps with the wider personal fitness trainer industry. The market for subscription services is expanding, with direct-to-consumer online sales projected to grow from USD 2.5 billion in 2026 to USD 4.5 billion by 2033, reflecting a compound annual growth rate of 8.8%. This growth reflects strong demand for convenient and flexible fitness solutions.
Investments in connected equipment and subscription services facilitate a more dynamic fitness experience, enhancing long-term customer loyalty. While consumers increasingly seek innovative and engaging fitness solutions, the proliferation of connected devices alongside subscription models positions suppliers favorably within the competitive environment of the market.
Compact strength systems and adjustable weights represent a significant trend within the Home Fitness Equipment market, particularly for consumers with limited space in their homes. These systems provide versatile workout options without requiring the footprint of traditional weight equipment. Buyers typically favor budget-friendly equipment due to its accessibility and reduced financial commitment. For instance, budget-friendly equipment is projected to grow from USD 4.4 billion in 2026 to USD 6 billion in 2033, reflecting a compound annual growth rate (CAGR) of 4.8%. This trend indicates a shift toward more affordable solutions that do not compromise on functionality.
Flexible payment models further enhance the attractiveness of compact strength systems and adjustable weights. Retailers increasingly offer financing options, allowing customers to acquire equipment through monthly installments. Installment plans of this kind are closely related to buy now pay later services. This approach makes fitness more accessible, catering to a broader audience. This growth signifies a strong buyer preference for convenience and affordability, shaping the purchasing landscape in the market.
Direct-to-consumer (DTC) sales strategies in the Home Fitness Equipment market have gained traction among brands aiming to cater to specific buyer groups. Fitness enthusiasts increasingly prefer purchasing equipment online, prioritizing convenience and product variety. This growth reflects shifting consumer behavior toward online purchasing.
Pricing strategies within DTC channels strongly influence customer acquisition. Brands frequently implement tiered pricing structures to accommodate diverse budgets, ranging from budget-friendly options to premium high-end equipment. By balancing quality and affordability, companies effectively address the distinct needs of their target audience while enhancing their competitive position in the market.
Durability significantly impacts purchasing decisions in the Home Fitness Equipment market. Buyers prioritize equipment that withstands rigorous use while maintaining functionality and aesthetics. High durability contributes to long-term investment value, reducing the need for frequent replacements. This factor is particularly important for male users, who typically seek reliable and robust equipment. In the segment of exercise bikes, which is anticipated to reach a value of USD 3.4 billion by 2033, durability is a significant factor in consumer preference.
Another critical feature is technology integration, which enhances the user experience. Equipment with advanced connectivity features, performance tracking, and personalized workout plans appeals to tech-savvy consumers. For example, smart treadmills equipped with interactive workout programs attract a growing demographic interested in fitness technology. The integration of technology into fitness equipment is expected to drive higher sales, particularly in direct-to-consumer online sales channels, projected to grow to USD 4.5 billion by 2033.
The rising focus on health and fitness drives demand for home fitness solutions among various consumer segments. Fitness enthusiasts and individuals seeking convenient exercise options increasingly purchase equipment for home use. The shift toward home workouts reflects broader lifestyle changes, including the prioritization of health and the flexibility of exercising at home. Budget-friendly equipment appeals to consumers looking for affordable fitness solutions. Increased participation in fitness activities contributes to higher volumes of sales, significantly impacting the overall market dynamics.
This shift indicates that consumers increasingly value the accessibility and convenience that home fitness options provide.
Innovative technologies transform equipment design and user experience within the market. Advanced features, including interactive displays and integrated workout programs, attract consumers seeking personalized workout solutions. These innovations enhance engagement, motivating users to maintain fitness routines. Fitness equipment equipped with smart technology, including progress tracking and virtual coaching, addresses the increasing demand for effective home workouts.
Technological advancements lead to the introduction of versatile machines that combine multiple functionalities, appealing to space-conscious consumers. Products that offer features including built-in heart rate monitoring and app connectivity attract tech-savvy buyers. The integration of artificial intelligence in home fitness equipment allows for tailored workout plans, further driving sales growth. Manufacturers investing in these advancements position themselves to capture significant market share and stay competitive. The continuous evolution of fitness technology supports sustained expansion within the home fitness equipment market.
Price sensitivity presents a significant barrier to adoption within the Home Fitness Equipment market, particularly among budget-conscious consumers. Many individuals prioritize affordability when selecting fitness equipment, leading to slower uptake of premium products. This constraint restricts purchase frequency and order sizes among consumers seeking quality while adhering to financial limitations.
Budget-friendly equipment remains popular due to the lower financial commitment required, limiting the potential for higher-priced alternatives. Equipment manufacturers face challenges in promoting premium offerings, affecting overall market growth. The focus on cost-effectiveness influences purchasing behaviors, delaying equipment replacements and reducing investment in advanced fitness solutions. Ultimately, addressing price sensitivity among buyers is essential for manufacturers seeking to expand their market presence.
Rising input costs for raw materials significantly impact profit margins in the home fitness equipment market. Suppliers face challenges due to escalating prices for components and transportation, leading to increased production expenses. This situation creates pressure on manufacturers, compelling them to make strategic adjustments to maintain profitability. Suppliers respond by optimizing supply chain efficiencies and exploring alternative materials that balance performance and cost. Several companies invest in technology to enhance production processes, aiming to reduce waste and streamline operations. Innovations in design and engineering help mitigate costs while retaining product quality. These adaptations help sustain competitiveness and consumer appeal in a market marked by fluctuating expenses and rising consumer expectations. Margin pressure influences long-term investment decisions and growth strategies across the sector.
The segment of Direct-to-Consumer Online Sales presents a significant opportunity within the market, driven by changing purchasing behaviors. Increased consumer confidence in online shopping and the convenience of home delivery support this rise. Home delivery depends on courier, express, and parcel services. Buyers, particularly younger demographics, prefer purchasing fitness equipment via online platforms, seeking both variety and competitive pricing.
Brands that effectively engage consumers through targeted online marketing strategies benefit from this trend. By offering customized shopping experiences and using social media for outreach, companies enhance brand loyalty and drive higher sales volumes. The ongoing growth of this channel indicates a shift in how consumers access home fitness equipment, emphasizing the importance of adapting to evolving consumer preferences. This trend signifies an important aspect of the market's expansion in the coming years.
The Global Home Fitness Equipment market is segmented based on Product Type, Price Range, End-User, and Distribution Channel.
Treadmills are valued at USD 3.4 billion in 2026 and are projected to reach USD 4.6 billion by 2033, at a CAGR of 4.4% during the forecast period. Popular among fitness enthusiasts and individuals pursuing home workouts, treadmills serve as effective tools for cardiovascular exercise and weight management. The growing emphasis on fitness awareness and the convenience of indoor running drive demand in this segment. Compared to other product types, treadmills exhibit moderate growth, distinguishing themselves with a steady increase in consumer interest. Unlike exercise bikes, which have a higher CAGR of 5.1%, the treadmill segment maintains a stable appeal, attracting buyers seeking reliable and familiar exercise equipment. This segment's growth reflects changing consumer habits and preferences for at-home fitness solutions, highlighting its integral role in the market.
Exercise Bikes segment is estimated to reach USD 3.4 billion by 2033, at a CAGR of 5.1% during the forecast period. This equipment caters primarily to home users seeking effective cardiovascular workouts. Increasing awareness of fitness and health trends drives demand from fitness enthusiasts and casual users alike. The segment stands out due to its relatively lower price point compared to higher-end equipment like premium treadmills, making it more accessible for various consumer groups. Technological advancements in bike design, such as integrated screens and interactive cycling classes, significantly enhance user experience. These factors position the Exercise Bikes segment for steady growth, differentiating it from segments like rowing machines and elliptical trainers, which exhibit slower expansion rates.
Elliptical Trainers segment is expected to reach USD 1.6 billion by 2033. This equipment serves fitness enthusiasts who prefer low-impact workouts, allowing for effective cardiovascular training without putting excessive strain on joints. The upward trend in health awareness drives demand for elliptical trainers, with a growing number of consumers prioritizing home workouts to maintain fitness levels. The segment experiences a higher growth rate compared to other types, influenced by its user-friendly design and versatility. In particular, the segment's CAGR of 5.1% reflects strong market interest, differentiating it from segments including Exercise Bikes, which show a CAGR of 5.3%. Factors including technological advancements in design and functionality further enhance the appeal of elliptical trainers, contributing to their increasing adoption among various user demographics.
Rowing Machines segment is projected to grow at a CAGR of 7.3% during the forecast period. These machines are designed for full-body workouts and cater to fitness enthusiasts seeking low-impact exercise options. The growing emphasis on convenient home workouts significantly influences this segment, attracting both casual users and serious athletes. Rowing machines differentiate themselves from other equipment options through their effectiveness in providing cardiovascular and strength training simultaneously. Compared to other segments, Rowing Machines exhibit faster growth, driven by an increasing number of consumers prioritizing home fitness solutions. Technological advancements in rowing machine design enhance user experience, further driving demand within the market. As more individuals embrace fitness-oriented lifestyles, rowing machines are expected to grow in popularity, strengthening their position in the competitive landscape.
Steppers and Climbers are fitness equipment designed to simulate stair climbing and stepping motions, providing an effective cardiovascular workout. This segment attracts fitness enthusiasts and individuals seeking to enhance their home exercise routines. Growing health awareness among consumers supports the demand for this equipment, driven by a desire for convenient and efficient workout solutions. Innovations in design and technology fuel product development, making these machines more appealing. Compared to other segments, Steppers and Climbers typically occupy a lower price range, offering a budget-friendly alternative for buyers focused on compact, space-saving fitness options. This segment's unique position differentiates it from higher-priced equipment, allowing it to capture a diverse customer base focused on affordability and functionality.
Free weights encompass a variety of strength training tools, including dumbbells, kettlebells, and barbells, used by fitness enthusiasts for resistance training at home. This segment appeals to both serious weightlifters and casual users seeking to enhance muscle strength and overall fitness. The growing awareness of health and wellness fuels demand for strength training solutions, particularly among individuals aiming to maintain physical fitness without gym memberships. Price sensitivity influences this segment, with budget-friendly options gaining traction among consumers seeking affordable home workout solutions. Unlike other segments including treadmills and exercise bikes, which emphasize advanced technology and connectivity features, free weights focus on fundamental strength-building techniques, providing a straightforward, traditional approach to fitness. The distinct user base and differing market dynamics contribute to a unique position within the Home Fitness Equipment market.
Strength training machines provide targeted resistance training solutions for home users. These machines serve fitness enthusiasts seeking to enhance their strength training routines by offering various weight options and adjustable settings. A growing awareness of health and fitness trends drives demand for these products, particularly among individuals focused on building muscle and improving overall fitness. This sub-segment experiences significant competition from other equipment forms, including free weights, which appeal to budget-conscious consumers. Strength training machines typically represent a higher price point compared to budget-friendly alternatives, distinguishing their market position. The trend toward home fitness solutions influences purchasing behaviors, with consumers increasingly favoring versatile and efficient equipment that fits within their home environments.
Weight benches and power racks serve as essential components for strength training, allowing users to perform a variety of exercises targeting different muscle groups. Fitness enthusiasts, both male and female, utilize these tools for their effectiveness in building strength and improving overall fitness. The growth of this segment is driven by increasing interest in home fitness solutions, particularly among individuals seeking versatile equipment for strength training. This segment stands out due to its strong appeal to dedicated weightlifters and fitness-focused consumers. Price considerations influence purchasing behavior, with many seeking budget-friendly options to meet their workout needs. Compared to other segments, including exercise bikes and treadmills, weight benches and power racks cater specifically to strength training enthusiasts, reflecting distinct consumer preferences within the home fitness equipment market.
Pilates Equipment comprises a variety of tools designed to enhance flexibility, balance, and core strength through controlled movements. This equipment attracts fitness enthusiasts seeking low-impact workouts that promote well-being and rehabilitation. Reformer machines, a related equipment type, are covered in the Pilates reformer industry. Trends in health awareness drive interest among both men and women, with a growing emphasis on fitness approaches. Demand for Pilates Equipment is influenced by the increasing popularity of home workout solutions, especially among individuals seeking alternatives to traditional gym settings. Compared to other segments, Pilates Equipment targets a niche market, often appealing to consumers interested in specialized workouts rather than general fitness training. This segment experiences slower growth than others, reflecting a more established consumer base focused on specific fitness goals and preferences. With rising interest in wellness and self-care, Pilates Equipment contributes to the changing dynamics of the Home Fitness Equipment market.
Resistance bands, suspension trainers, and exercise mats embody a versatile category of fitness equipment for strength training, flexibility, and rehabilitation exercises. Rehabilitation use ties these products to the wider physiotherapy industry. These tools appeal to a diverse range of users, including fitness enthusiasts and those seeking low-impact workouts at home. The growing preference for home workouts drives demand for these products, with consumers prioritizing convenience and affordability. Resistance bands, for instance, offer a compact and cost-effective alternative to traditional weights, attracting budget-conscious individuals. This sub-segment distinguishes itself from larger equipment categories due to its accessibility and ease of use, appealing to both beginners and experienced users. The increasing awareness of functional training and rehabilitation methods drives growth in this area, positioning it uniquely within the competitive landscape of the home fitness equipment market.
This segment serves various consumers seeking affordable fitness solutions for home workouts. The increasing health consciousness among individuals drives demand for cost-effective fitness products. Compared to other segments, including Mid-Range Equipment with a projected CAGR of 5.3%, Budget-Friendly Equipment offers lower price points, making it appealing to budget-conscious consumers. This affordability factor often translates to higher sales volumes, despite potentially lower profit margins for manufacturers. Consumers within this segment typically prioritize accessibility and value, which differentiates their purchasing behavior from those seeking higher-end products in the market.
Mid-Range Equipment segment is estimated to reach USD 8.1 billion by 2033, at a CAGR of 5.3% during the forecast period. This segment appeals to a diverse range of consumers seeking quality fitness solutions without entering the premium price tier. Individuals focused on enhancing their home workout experience frequently opt for mid-range equipment, balancing performance with affordability. Demand within this segment primarily stems from the growing awareness of fitness and well-being, which drives consumers to invest in their health. Mid-Range Equipment typically features better durability and advanced functionalities compared to budget-friendly alternatives, while remaining more accessible than high-end products. With a focus on both performance and cost-effectiveness, this segment experiences consistent growth, distinguishing it from other price categories in the market. The ongoing expansion of e-commerce channels further supports its accessibility, making it easier for consumers to acquire these products from various platforms.
Premium/High-End Equipment segment is expected to reach USD 5.9 billion by 2033. This category includes high-quality fitness machines and tools that cater to those seeking advanced features, durability, and superior performance. Fitness enthusiasts and dedicated home users typically purchase this equipment for serious training purposes, focusing on strength, endurance, and overall fitness. Growth in this segment benefits from increasing consumer awareness regarding health and fitness, alongside rising disposable incomes. This segment experiences a faster growth rate, with a CAGR of 5.9%, compared to lower-priced segments. Premium/High-End Equipment stands apart due to its higher price point, attracting a more affluent demographic that values quality and innovation. Market dynamics shift in response to technological advancements in fitness equipment, prompting manufacturers to invest in high-end features and connectivity options to attract discerning buyers.
Valued at USD 7.6 billion in 2026, the male segment is projected to reach USD 10.8 billion by 2033, at a CAGR of 5.1% during the forecast period. This segment appeals primarily to male fitness enthusiasts seeking to improve strength and fitness levels through various training modalities. Factors driving growth include increasing awareness of health and fitness, alongside a growing preference for home workouts due to convenience and flexibility. Compared to female counterparts, the male segment exhibits a slightly lower growth rate, likely influenced by differing purchasing behaviors and preferences. The male segment's distinct characteristics present unique opportunities for brands targeting male consumers, leading to tailored marketing strategies and product offerings that connect with this demographic. While both segments exhibit growth, the emphasis on personal fitness among males suggests continued investment in targeted home fitness solutions.
The female segment is estimated to reach USD 9.2 billion by 2033, at a CAGR of 6.3% during the forecast period. This segment caters to women who engage in home workouts, using equipment designed specifically for their fitness needs. Growing health awareness and an increasing emphasis on personal wellness drive significant demand for home fitness equipment among female users. Compared to the male segment, which has a projected value of USD 10.8 billion by 2033, the female segment experiences slightly faster growth, indicating a rising interest in fitness among women. The availability of tailored equipment and targeted marketing strategies further enhance adoption, with brands focusing on aesthetics and usability to appeal to female consumers. The market reflects these trends, emphasizing the importance of addressing diverse preferences in fitness equipment.
This segment allows customers to purchase fitness equipment directly from manufacturers through online platforms, catering to a growing base of health-conscious individuals seeking convenient access to fitness solutions. The increase in home fitness activities drives demand, particularly among younger demographics who prefer online shopping. In comparison to other distribution channels, this segment exhibits faster growth, driven by technological advancements and the rise of e-commerce. The shift in consumer behavior toward online purchasing has created opportunities for brands to engage directly with customers, enhancing brand loyalty and customer satisfaction. These factors differentiate the segment from traditional retail avenues, contributing significantly to the overall growth of the market.
Third-Party Online Retail segment is estimated to reach USD 5.1 billion by 2033, at a CAGR of 8.1% during the forecast period. This segment primarily serves consumers looking to purchase fitness equipment through online platforms, which offer convenience and a wide selection. The increasing reliance on e-commerce driven by consumer preferences for home delivery significantly boosts this segment. Compared to other distribution channels, Third-Party Online Retail exhibits faster growth, supported by the rise in online shopping habits, particularly among younger demographics. The accessibility of fitness products through various online retailers makes this segment attractive for buyers who prioritize variety and competitive pricing. Market dynamics favor this segment due to a growing trend toward digital purchasing methods, reshaping the shopping experience for fitness enthusiasts.
Specialty Fitness Stores segment is expected to reach USD 5 billion by 2033. This segment caters to fitness enthusiasts seeking specialized equipment and expert guidance. Consumers prioritize quality and personalized service when purchasing from these stores. The rising trend of home workouts drives demand for high-quality fitness products, leading to increased traffic in specialty stores. Compared to other distribution channels, this segment enjoys a unique position due to the expert advice provided by staff and the ability to test equipment before purchase. The forecast indicates that this segment is projected to experience steady growth, supported by a greater focus on personalized fitness solutions. The market continues to evolve with consumers increasingly valuing the expertise available at these outlets.
Mass Merchandisers and Sporting Goods Stores segment is projected to grow at a CAGR of 3.6% during the forecast period. This segment serves fitness enthusiasts and casual users seeking a variety of home fitness equipment. Increasing consumer awareness of health benefits drives demand, while competition among retailers influences pricing strategies. Unlike segments including Direct-to-Consumer Online Sales, which shows a faster growth rate at 8.8%, this segment offers a more stable market presence. Consumers purchasing from mass merchandisers and sporting goods stores prioritize immediate availability and the ability to physically inspect products before purchase. This preference shapes the customer experience compared to online sales channels, where convenience holds significance. The market reflects a growing trend toward integrating fitness into everyday life, further supporting expansion and investment in this channel.
Direct Offline Sales involves traditional retail opportunities for home fitness equipment, providing customers with hands-on experiences before purchase. This channel serves a diverse group of buyers, including fitness enthusiasts and casual users seeking reliable products. One factor influencing this segment is the growing preference for in-person shopping experiences, where customers value the ability to physically test equipment. Compared to online channels, Direct Offline Sales employs a different pricing strategy, with potential cost advantages due to lower shipping expenses. This channel experiences relatively slower growth than Direct-to-Consumer Online Sales, which benefits from a higher CAGR of 8.8%. Shifts in consumer behavior toward online shopping impact the performance of this segment, challenging retailers to enhance their in-store offerings to attract customers. The Home Fitness Equipment market adapts to evolving consumer preferences, ensuring that various distribution channels meet diverse needs effectively.
Based on geography, the Global Home Fitness Equipment market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Strong consumer interest in fitness and wellness drives the demand for home fitness equipment in North America. The region benefits from a growing awareness of health and fitness, particularly among millennials and Gen Z consumers. This trend reflects a shift toward maintaining fitness routines at home, driven by the convenience and flexibility offered by home gym solutions. North America accounted for 37.2% of the market in 2025. North America is projected to reach USD 7 billion by the end of 2033. Increased penetration of e-commerce channels facilitates consumer access to a wide range of home fitness equipment, including treadmills and exercise bikes. Evolving buying patterns prioritize online purchasing, especially among younger demographics, further stimulating growth in the home fitness equipment market.
In Europe, the demand for fitness solutions continues to rise significantly, driven by increasing health consciousness among consumers. Countries including Germany and the UK lead in adopting innovative exercise technologies, creating a competitive market environment. Specific initiatives promoting physical health, alongside government-backed wellness programs, contribute to the growth landscape. The market benefits from strong retail infrastructure, enabling easy access to various fitness products across urban areas. By 2025, Europe is anticipated to hold a 27.9% share of the global market. Trends indicate a growing preference for online purchasing, with direct-to-consumer channels gaining momentum in the region. Rising disposable income among consumers supports higher spending on the Home Fitness Equipment market, leading to a diversified product offering that caters to varying user needs.
Asia-Pacific is a key region in the Home Fitness Equipment market, driven by increasing health consciousness and a growing inclination towards home-based workouts. In countries like China, Japan, and India, urbanization and lifestyle changes contribute to rising demand for fitness solutions. Infrastructure improvements, coupled with strong digital penetration, enable the expansion of online sales channels, making fitness equipment more accessible. The forecast indicates that the region will capture a 20.1% share of the global market in 2025, reflecting a strong trend towards personalized fitness solutions. Competition among local and international manufacturers intensifies, enhancing the variety of products available to consumers. Market growth is expected to gain momentum, supported by evolving consumer preferences and a desire for convenient training options.
In South America, the market demonstrates a growing interest in home fitness solutions, driven by changing lifestyles and increased health awareness among consumers. Brazil and Argentina emerge as key countries contributing to this demand, focusing on budget-friendly and mid-range fitness equipment. The market share for South America stands at 10.1% in 2025, highlighting the region's potential within the global landscape. Infrastructure development, particularly in urban areas, supports the accessibility of fitness products. Online sales channels, including direct-to-consumer platforms, gain traction as consumers seek convenient purchasing options. The Home Fitness Equipment market in this region is projected to experience steady growth, reflecting the broader consumer shift toward health and wellness.
In the Middle East and Africa, the market for home fitness equipment is expected to grow due to increasing health awareness among consumers. Countries like Saudi Arabia and the UAE exhibit rising interest in personal fitness and wellness, driving demand for various fitness solutions. South Africa's expanding fitness culture contributes to the market's growth; consumers invest in home fitness equipment. The region has unique infrastructural conditions, with a growing number of fitness-related retail outlets enhancing accessibility for consumers. With a market share of 4.7% in 2025, the home fitness equipment market in this region reflects a significant opportunity for manufacturers focusing on tailored products and services that meet local consumer preferences.
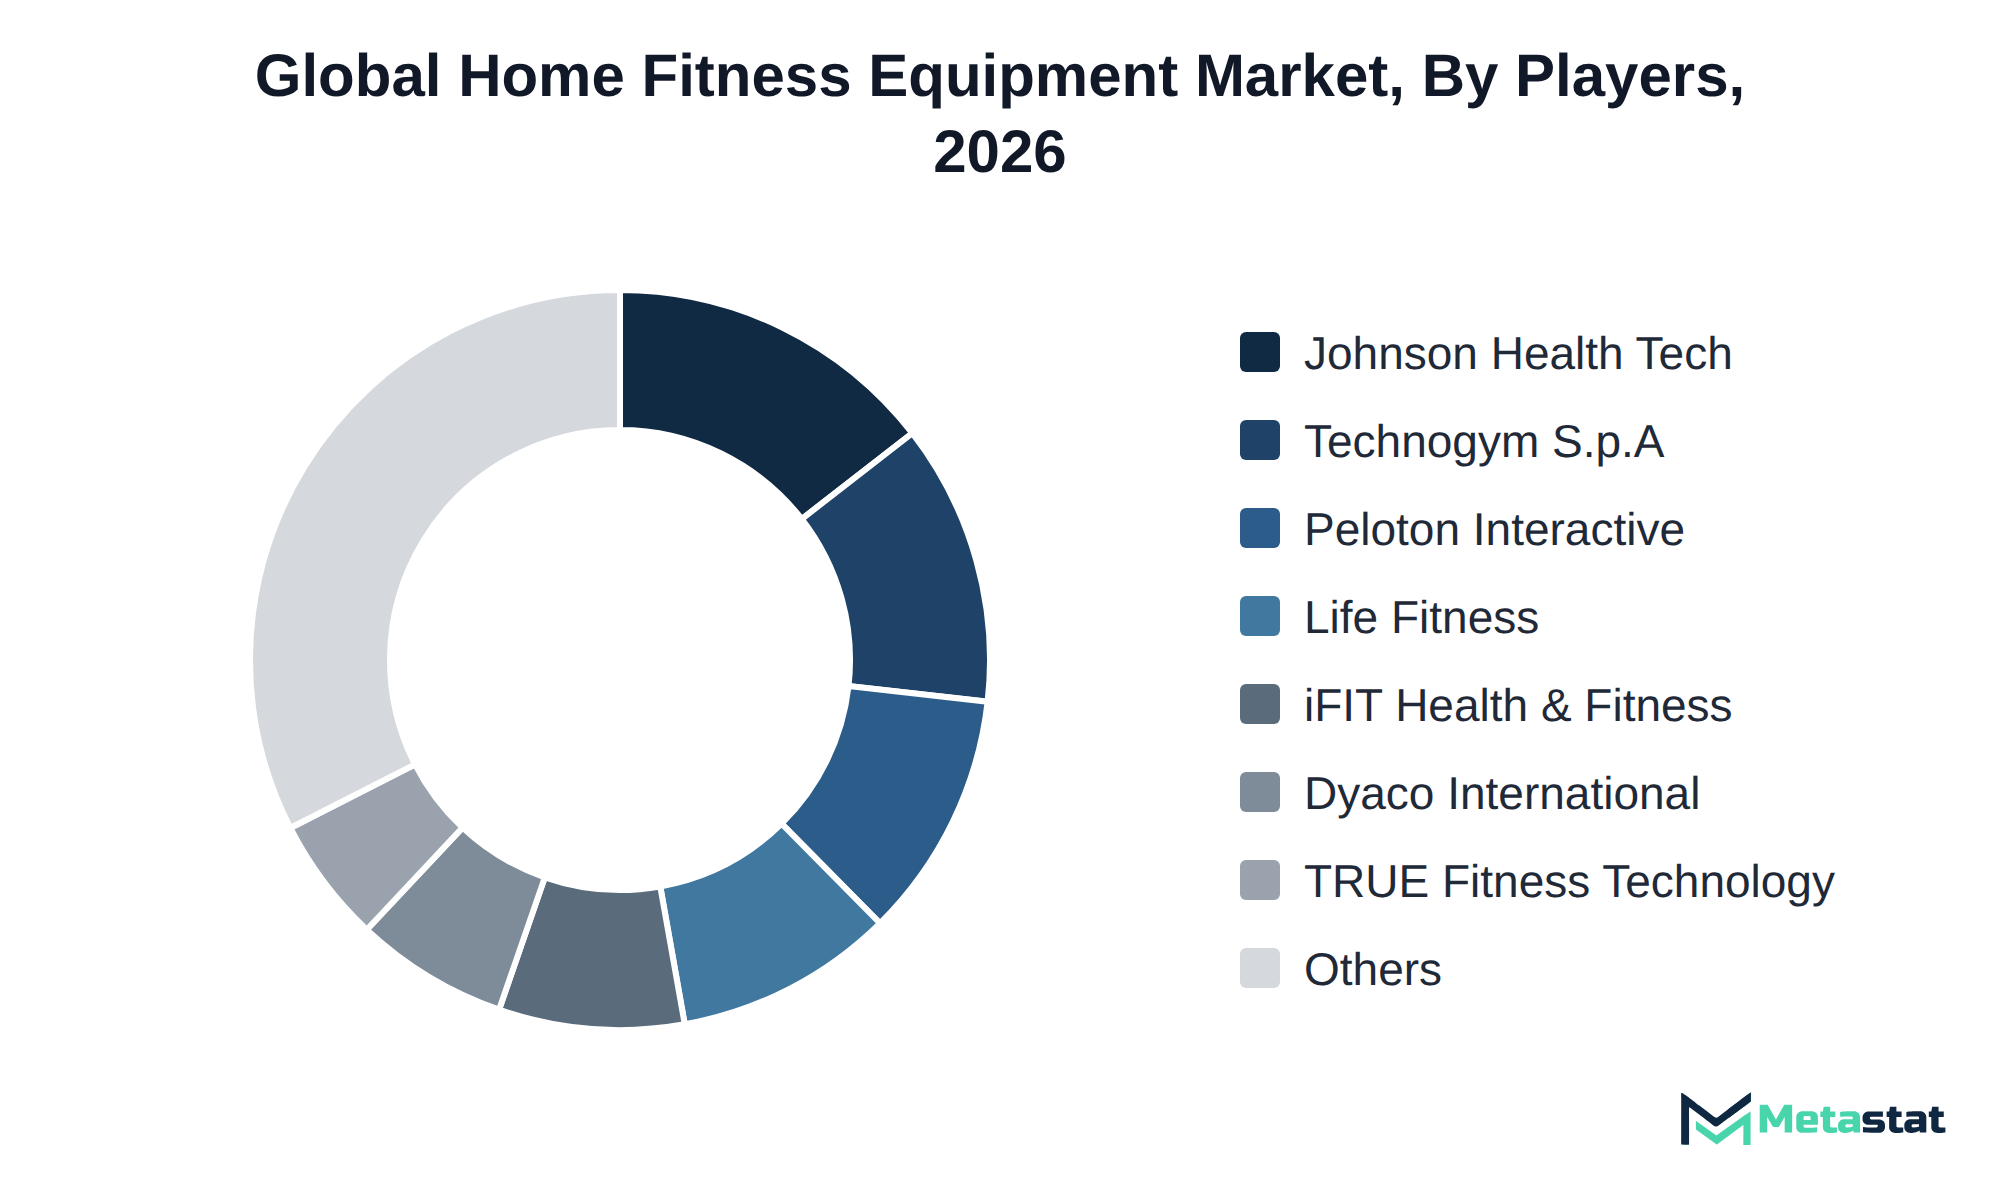
Companies in the Home Fitness Equipment market differentiate their offerings based on product type, price range, and distribution channel. Major segments include treadmills, exercise bikes, and rowing machines, with distinct pricing categories including budget-friendly, mid-range, and premium equipment. Buyers select products based on factors including price, customization options, and the reputation of manufacturers.
Johnson Health Tech Co., Ltd. emphasizes innovation with a diverse range of products tailored for various fitness levels. Peloton Interactive, Inc. focuses on integrating technology with fitness through connected equipment and subscription-based services. Technogym S.p.A. prioritizes premium wellness solutions that combine fitness and lifestyle, appealing to health-conscious consumers seeking quality. Each company's strategy reflects its positioning within the market, targeting specific consumer needs and preferences.
Achieving this growth requires several key developments, particularly in the Direct-to-Consumer Online Sales segment, which is projected to experience a strong CAGR of 8.8%. Increased consumer preference for purchasing fitness equipment online drives this trend. The growth of the male end-user segment, expected to grow from USD 7.6 billion in 2026 to USD 10.8 billion by 2033, will significantly contribute to market expansion, reflecting a broader acceptance of home fitness solutions among this demographic. Conversely, potential economic downturns pose risks that hinder growth, particularly in the Premium/High-End Equipment segment. Declining consumer spending weakens demand for higher-priced fitness equipment, impacting overall market revenue. The Home Fitness Equipment market stands to benefit from rising health awareness and the convenience of home workouts, but external economic conditions will play a critical role in determining the growth trajectory.
By Product Type: Treadmills, Exercise Bikes, Elliptical Trainers, Rowing Machines, Steppers and Climbers, Free Weights, Strength Training Machines, Weight Benches and Power Racks, Pilates Equipment, Others (Resistance Bands, Suspension Trainers, Exercise Mats)
By Price Range: Budget-Friendly Equipment, Mid-Range Equipment, Premium/High-End Equipment
By End-User: Male, Female
By Distribution Channel: Direct-to-Consumer Online Sales, Third-Party Online Retail, Specialty Fitness Stores, Mass Merchandisers and Sporting Goods Stores, Direct Offline Sales
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Home Fitness Equipment market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 5.7% from 2026 to 2033 |
|
Revenue Unit |
USD billion |
|
Segmentation |
By Product Type, Price Range, End-User, Distribution Channel, and Region |
|
By Region |
North America (By Product Type, Price Range, End-User, Distribution Channel, and Country)
|
|
Europe (By Product Type, Price Range, End-User, Distribution Channel, and Country)
|
|
|
Asia Pacific (By Product Type, Price Range, End-User, Distribution Channel, and Country)
|
|
|
South America (By Product Type, Price Range, End-User, Distribution Channel, and Country)
|
|
|
Middle East and Africa (By Product Type, Price Range, End-User, Distribution Channel, and Country)
|
Find answers to common questions about this report
The Home Fitness Equipment market size was valued at USD 12.8 billion in 2025.
The market is projected to grow at a CAGR of 5.7% during the forecast period from 2026 to 2033.
The North America Home Fitness Equipment market size is estimated to reach USD 7 billion by 2033.
Treadmills lead the Home Fitness Equipment market with a projected value of USD 4.6 billion by 2033, based on the highest growth rate among product types.
The rising focus on health and fitness drives demand for home fitness solutions among various consumer segments. Increased participation in fitness activities contributes to higher volumes of sales, significantly impacting overall market dynamics.
North America holds the dominant share of the Home Fitness Equipment market, with a value of USD 7 billion projected for 2033. This region accounts for 37.2 percent of the total market share.
Price sensitivity presents a significant barrier to adoption in the Home Fitness Equipment market. Budget-conscious consumers prioritize affordability, impacting the purchase frequency of premium products. Rising input costs for raw materials further restrict profit margins, compelling manufacturers to adjust strategies to maintain profitability.
The rising focus on health and fitness, coupled with the increasing availability of budget-friendly equipment, supports adoption in the home fitness equipment market. the growth of Direct-to-Consumer Online Sales enhances accessibility and convenience for consumers, driving further interest in home fitness solutions.
The Home Fitness Equipment market is estimated to reach a valuation of USD 20 billion by 2033.
Key players operating in the Home Fitness Equipment market include Johnson Health Tech Co., Ltd., iFIT Health & Fitness Inc., Technogym S.p.A., Life Fitness, Peloton Interactive, Inc., and Core Health & Fitness LLC.
The analysts below cover Consumer Goods research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
Most industry reports on warehouse automation bundle autonomous mobile robots and fixed conveyor installations into the same top-level numbers, which complicates advisory work. This study split the market cleanly by payload tiers, navigation technology, and fleet management software layers. The regional forecast for Western Europe gave our team defensible adoption benchmarks when evaluating capital allocation for logistics clients, saving us days of secondary data scrubbing.
Analyzing the transition from natural gas to green hydrogen in iron ore reduction requires realistic infrastructure timelines. Meta stat insight supplied a detailed regional assessment of DRI plant conversion costs and scrap metal availability in North America and Western Europe. Their report carefully examined pellet quality specs and electrical grid access constraints without making oversimplified market assumptions. The research material served as a practical reference during internal technology roadmap discussions.
Integrating zero-trust access controls across legacy electronic health record systems involves complex compliance overhead. Team produced an analysis that clearly separated identity governance and administration tools from privileged access management platforms. Their evaluation of HIPAA and GDPR compliance features across cloud native solutions gave our architecture group clear baseline criteria. The custom data request regarding biometric authentication adoption in hospital networks was returned promptly with clear documentation.
Explore related market intelligence reports worth reading alongside this one.