
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Engineering, Procurement, and Construction Management (EPCM) Market Size, Share, By Service Type (Engineering and Design, Procurement Management, Construction Management, Project Management and Controls, Commissioning Support), By End-Use Industry (Oil and Gas, Mining and Metals, Chemicals and Petrochemicals, Power and Utilities, Industrial Manufacturing, Pharmaceuticals and Biotechnology, Semiconductors and Electronics, Infrastructure), By Project Type (Greenfield Projects and Brownfield Projects), By Project Ownership (Private, Public and State-Owned, Public-Private Partnerships), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-3793
Published
October, 2026
Pages
255 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
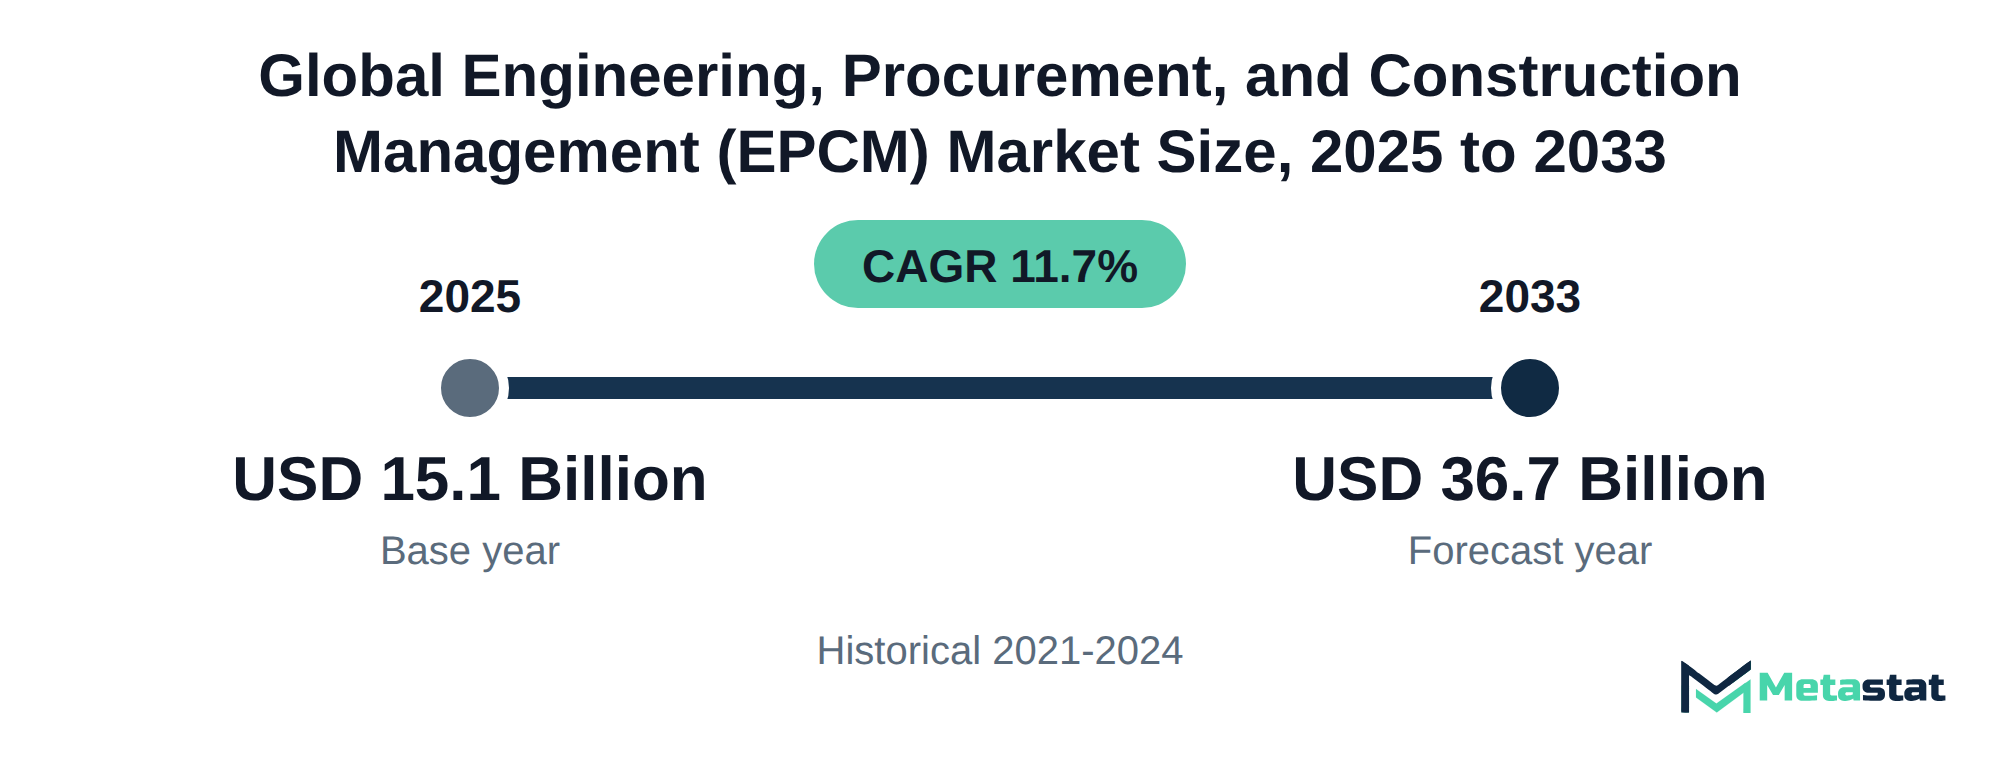
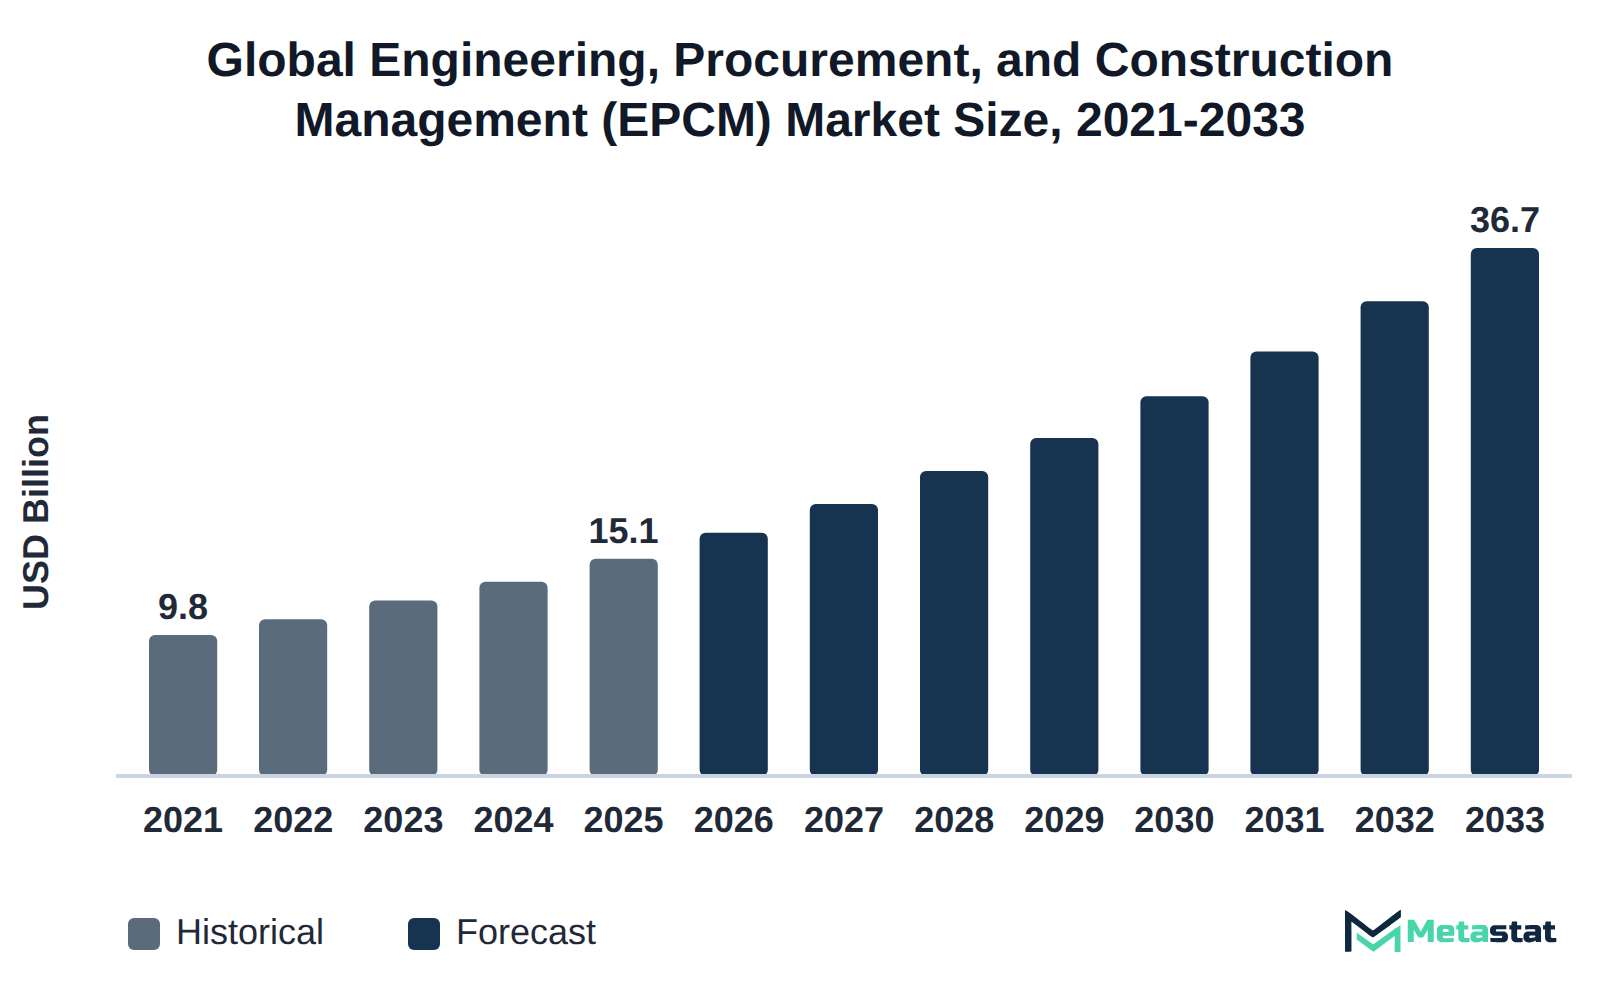
Market Valuation: Valued at $15.1 Billion in 2025, projected to reach $36.7 Billion by 2033 at a 11.7% CAGR.
Dominant Segment: The engineering and design segment leads the market, driven by increasing demand for innovative solutions that address contemporary construction challenges.
Geographic Lead: North America holds the largest market share, with the US expected to lead in growth due to a robust project pipeline and significant investments in infrastructure.
What's Inside: The report provides comprehensive coverage of market dynamics, competitive landscape, and detailed analyses of service types and end-use industries, along with forecasts through 2033.
Emerging Demand for Project Management S: Project management and controls are projected to grow rapidly, with a CAGR of 12.7%, driven by the increasing complexity of construction projects across various industries.
Investment in Innovative Technologies: Adoption of advanced technologies such as AI and automation is reshaping project execution, enhancing efficiency, and driving long-term operational savings.
Choose Your License
Global Engineering, Procurement, and Construction Management (EPCM) Market
The global Engineering, Procurement, and Construction Management (EPCM) market was valued at USD 15.1 billion in 2025 and is projected to reach USD 36.7 billion by 2033, growing at a CAGR of 11.7% over the forecast period.
The Engineering, Procurement, and Construction Management (EPCM) market encompasses services that are essential to the successful execution of construction projects. Buyers invest in this market to enhance efficiency, minimize risks, and ensure compliance with industry standards. The growing complexity of projects and the need for integrated solutions drive expenditure in this sector, as companies seek expertise in managing project phases from design to completion.
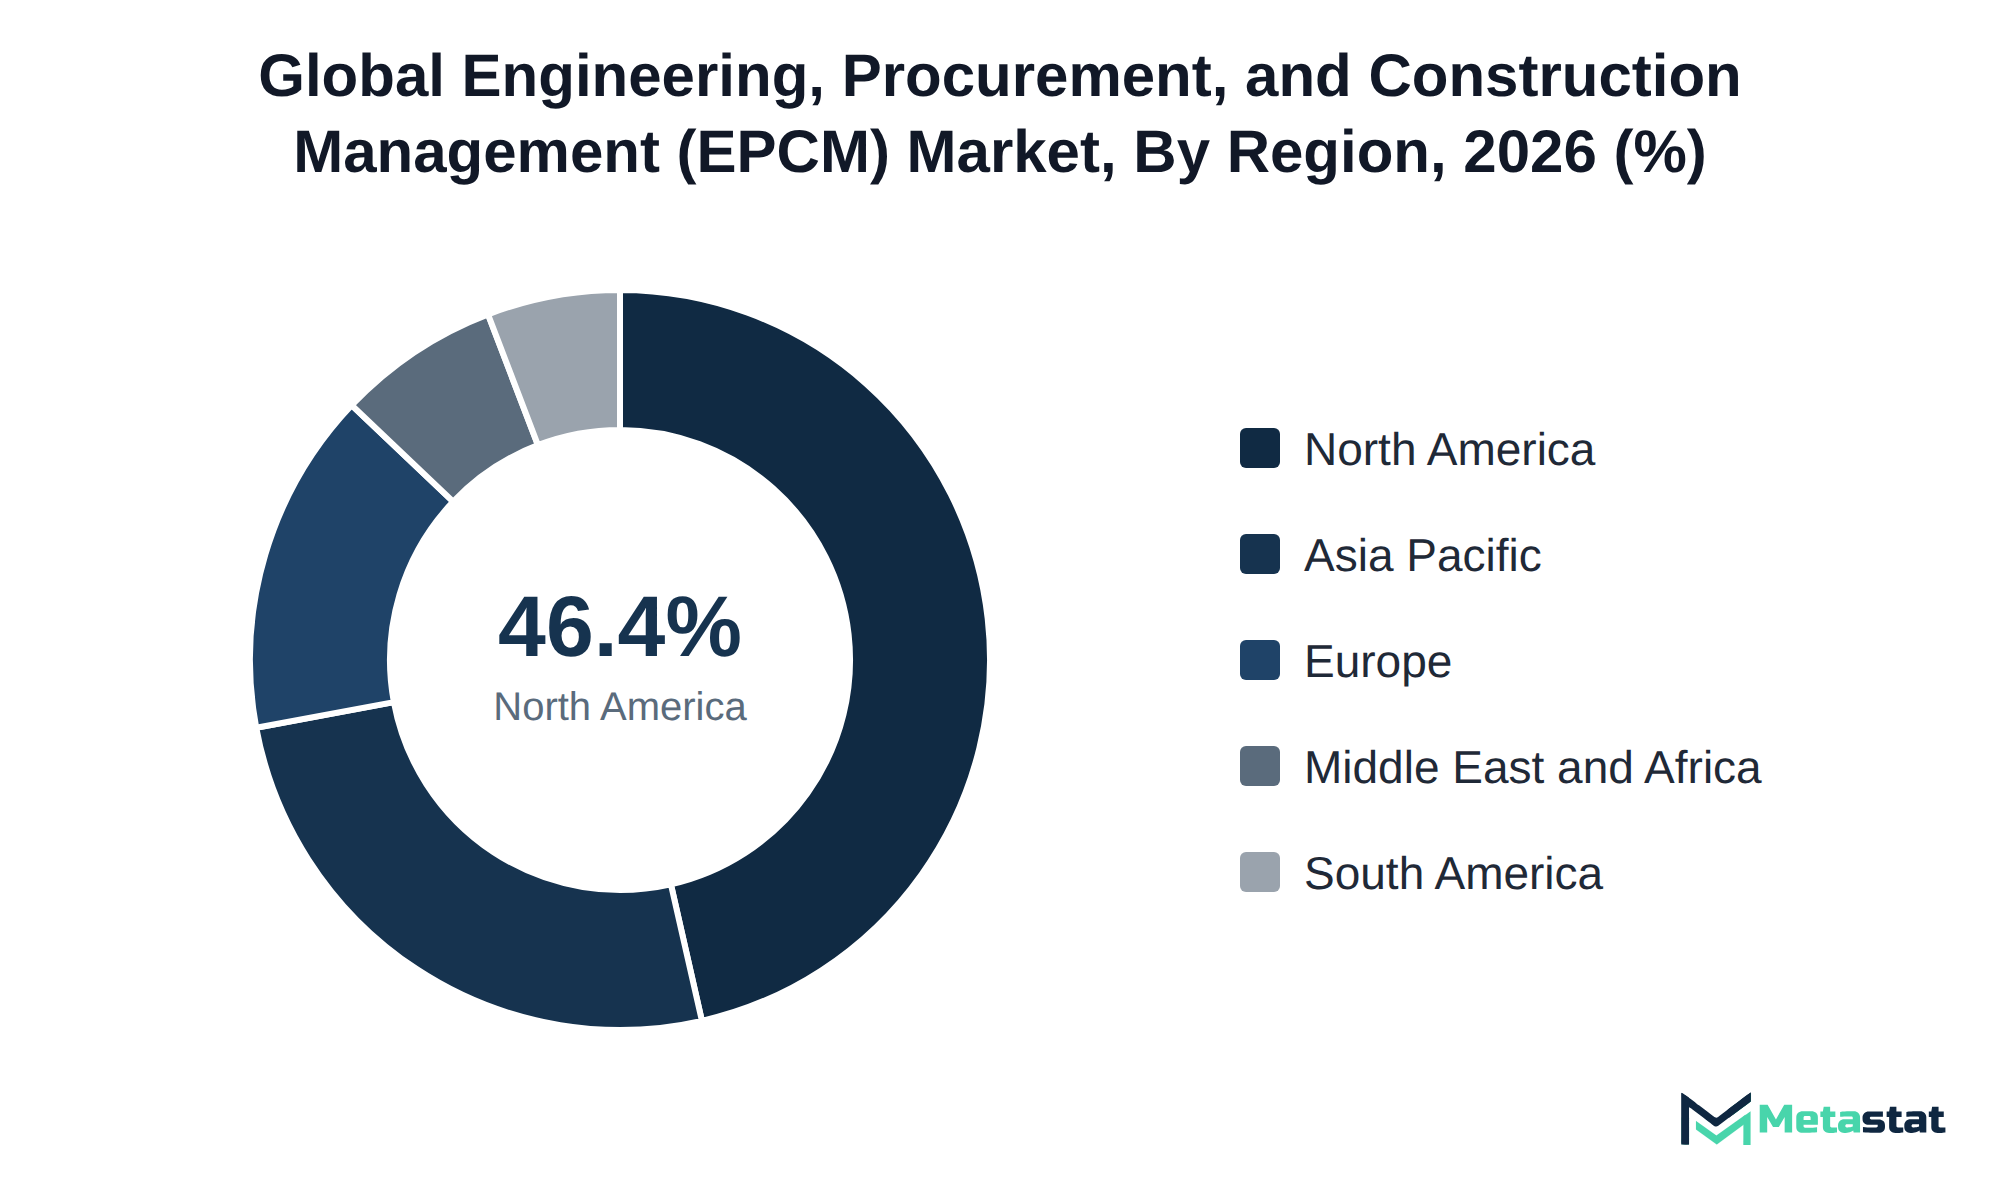
Growth in the market is fueled by several factors, including increasing investments in infrastructure and energy projects. The engineering and design segment represents the largest share of the market, reflecting the demand for innovative solutions that address contemporary challenges. North America holds 46.4% of the market in 2025, with the US leading in 2026. This significant share highlights the region's robust project pipeline and investment climate, supporting sustained growth in the EPCM sector.
The ongoing transition towards sustainable energy sources acts as a primary growth driver, prompting investment in renewable energy projects and environmentally friendly construction practices. Companies across various industries, including oil and gas, mining, and utilities, recognize the importance of adapting to these changes. Consequently, the Engineering, Procurement, and Construction Management (EPCM) market is projected to experience significant expansion in the coming years.
Investment in the Engineering, Procurement, and Construction Management (EPCM) market stems from its role in optimizing project delivery and ensuring cost-efficiency. Buyers across various sectors prioritize these services to enhance operational effectiveness and manage complex project requirements. The market provides essential support in engineering design, procurement management, and construction oversight, creating value for clients while facilitating timely project execution.
Growth in the market is driven by increasing infrastructure investments and a shift towards sustainable project management practices. The engineering and design segment represents the largest portion of the market, reflecting the rising demand for specialized design services that align with evolving industry standards. This region's robust construction activities and a strong focus on advanced technologies significantly contribute to its market dominance.
Investments in renewable energy and smart infrastructure projects are anticipated to further accelerate market growth. The need for innovative solutions to address environmental challenges and enhance project efficiency shapes demand. Organizations seek to improve their operational capabilities, and the Engineering, Procurement, and Construction Management (EPCM) market serves as a vital component of their strategic initiatives.
The shift towards critical minerals processing drives increased demand for integrated Engineering, Procurement, and Construction Management (EPCM) solutions. Industries seek sustainable practices, and the extraction and processing of essential minerals including lithium, cobalt, and rare earth elements significantly influence project complexity and scale. In 2023, the mining and metals sector demonstrates a strong trajectory, with a projected value of USD 9.1 billion by 2033, reflecting a compound annual growth rate of 12.3%. This trend highlights the growing need for specialized EPCM providers equipped to handle the unique challenges associated with critical minerals projects.
Technological advancements in mining techniques and processing technologies enhance efficiency and lower operational risks. EPCM firms adopt innovative methods to streamline processes, reduce costs, and ensure compliance with environmental regulations. These developments create competitive advantages and support the expansion of project portfolios aimed at meeting rising global demand for renewable energy technologies.
Integrating advanced solutions with full management services enables EPCM providers to deliver tailored strategies for stakeholders. With ongoing investment in critical minerals, the market experiences sustained growth, increasing opportunities for EPCM firms to enhance their service offerings and capture a larger share of the evolving landscape.
Investment in brownfield decarbonization projects generates sustained demand for engineering and construction management work within the Engineering, Procurement, and Construction Management (EPCM) market. The shift towards decarbonization highlights the necessity for existing facilities to upgrade infrastructure and implement sustainable practices. Brownfield projects are expected to reach USD 17.1 billion by 2033, driven by the ongoing transformation within industries including oil and gas, and chemicals and petrochemicals.
Contract models in this context often involve performance-based pricing structures, enabling clients to tie payment to project milestones and performance outcomes. This approach ensures that contractors focus on effective delivery and adherence to timelines while promoting accountability in project execution. Given that brownfield projects frequently involve complex, multi-phase developments, clients favor models that emphasize transparency and risk-sharing between parties.
The rising emphasis on sustainability in engineering and construction management translates into heightened competition among contractors to demonstrate expertise in decarbonization strategies. Consequently, firms that effectively use innovative technologies and sustainable practices increase their appeal to clients seeking to meet regulatory standards and corporate sustainability goals. This alignment impacts overall project profitability and establishes a foundation for future growth in the market.
Digital engineering and project controls transform capital project coordination, particularly for the oil and gas industry. This sector faces distinct challenges, including complex regulatory environments and the need for efficient resource management. The Engineering, Procurement, and Construction Management (EPCM) market offers innovative solutions that enhance project visibility and streamline workflows.
From 2026 to 2033, the Oil and Gas industry is expected to exhibit a compound annual growth rate (CAGR) of 9.3%, increasing from USD 4.2 billion to USD 7.8 billion. This growth results from rising global energy demands and the push for sustainable energy solutions. Implementing digital tools enhances decision-making capabilities, reduces delays, and drives cost savings. Real-time data analytics enables stakeholders to monitor project progress, optimize resource allocation, and mitigate risks effectively.
Investing in advanced project controls and digital engineering tools leads to improved project outcomes and operational efficiencies within the EPCM market. The Oil and Gas sector increasingly embraces these technologies, while competition intensifies, requiring firms to adapt and innovate. The integration of digital solutions represents a significant opportunity for stakeholders, ensuring successful project execution and long-term profitability.
Project owners often select Engineering, Procurement, and Construction Management (EPCM) over turnkey EPC when flexibility and control are essential. Unlike turnkey EPC, which delivers a complete project solution with a single contract, EPCM allows owners to maintain a higher level of involvement throughout the project lifecycle. This involvement proves critical in complex projects where requirements evolve over time.
Rising demand for tailored solutions favors EPCM, which lets project owners adjust strategies mid-project based on changing market dynamics or regulatory requirements.
Choosing EPCM leads to reduced risks associated with unforeseen changes, ensuring projects meet budgetary constraints and timelines effectively. As project complexity increases, the preference for EPCM among various sectors highlights its strategic advantage in improving operational efficiency and aligning projects with long-term goals.
Investment in greenfield projects drives significant growth in the Engineering, Procurement, and Construction Management (EPCM) market. Firms in sectors including oil and gas, mining and metals, and power and utilities actively pursue new infrastructure development to meet rising demand for energy and resources. The growing emphasis on sustainability and innovation enhances the volume of projects, positioning these industries to seek specialized EPCM services that streamline execution and reduce costs. The anticipated growth rate for greenfield projects reaches a compound annual growth rate (CAGR) of 10.5%, illustrating the market's expansion potential. This trend reflects a broader shift in investment strategies, where stakeholders prioritize long-term project viability and environmental considerations. The evolving landscape highlights the increasing reliance on EPCM expertise to deliver complex projects efficiently.
Adoption of innovative technologies significantly influences the Engineering, Procurement, and Construction Management (EPCM) market. Advanced technologies including artificial intelligence, machine learning, and automation streamline project execution and enhance overall efficiency. Enhanced design tools enable teams to produce more precise project plans, resulting in reduced rework and minimizing delays. Integrated project management software provides real-time data analytics, allowing for improved decision-making and risk management.
Industries like Oil and Gas seek these technological advancements to optimize operations and increase productivity amid rising project complexities. Investment in these technologies incurs initial costs, but long-term operational efficiencies and cost savings lead to substantial financial returns. The shift toward innovative technology adoption is projected to drive market growth significantly during the forecast period. Enhanced productivity and reduced project timelines contribute to greater competitiveness among EPCM firms in a changing market.
Compliance with stringent regulatory requirements presents a significant restraint on project timelines within the market. Many stakeholders, particularly in the oil and gas and chemicals industries, face challenges in navigating the complex frameworks governing environmental, health, and safety standards. This complexity leads to slower project approvals and results in increased costs related to legal consultations and administrative processes. Stakeholders often incur delays in initiating and completing projects due to lengthy compliance verification processes. This situation restricts the overall growth potential of the Engineering, Procurement, and Construction Management (EPCM) market, impacting investment decisions and project timelines. As regulatory frameworks evolve and become more rigorous, companies involved in the market allocate resources to ensure compliance, diverting funds away from project innovation and development.
The Engineering, Procurement, and Construction Management (EPCM) market faces significant challenges related to rising costs, particularly in talent acquisition and retention. Suppliers encounter increasing demands for skilled personnel, driving up labor expenses. Labor shortages in key regions force companies to enhance compensation packages to attract qualified professionals. This pressure on talent costs directly impacts project budgets and profit margins, creating challenges in maintaining competitive pricing for services.
In response, suppliers implement strategies including investing in training programs to upskill existing employees and enhance productivity. Firms increasingly prioritize automation and technology to optimize workforce efficiency, reducing reliance on manual labor while maintaining service quality. These adaptations build resilience in the face of rising operational costs, supporting continued growth and competitiveness in the market.
Project management and controls stand out as a significant growth segment within the Engineering, Procurement, and Construction Management (EPCM) market, projected to expand at a compound annual growth rate (CAGR) of 12.7% through 2033. This rapid growth stems from increasing complexity in construction projects, necessitating enhanced oversight and coordination. Industries including Oil and Gas, Chemicals and Petrochemicals, and Power and Utilities drive demand for these services, focusing on efficiency and effective project delivery.
By addressing specific challenges related to cost management and scheduling, project management services provide critical solutions to stakeholders. The emphasis on precision and timely execution in high-stakes environments results in heightened reliance on these services, enabling companies to optimize their project outcomes. Overall market expansion is anticipated, with significant implications for investment and competitive dynamics within the EPCM landscape.
The Global Engineering, Procurement, and Construction Management (EPCM) market is segmented based on Service Type, End-Use Industry, Project Type, and Project Ownership.
The Engineering and Design segment is valued at USD 6.6 billion in 2026 and is projected to reach USD 13.9 billion by 2033, at a CAGR of 11.2% during the forecast period. This segment focuses on the planning and development of construction projects, serving various industries including oil and gas, mining, and infrastructure. Increasing investment in infrastructure projects drives demand for these services, particularly in emerging markets. The segment distinguishes itself from others in the service type category, exhibiting a higher growth rate compared to Procurement Management, which is anticipated to achieve a CAGR of 11.2%. Competitive pressures in the market necessitate innovation and efficiency in engineering processes, further increasing the importance of this segment in delivering cost-effective solutions for clients.
Procurement Management segment is estimated to reach USD 5.2 billion by 2033, at a CAGR of 11.2% during the forecast period. This segment functions to oversee the acquisition of materials and services essential for various projects, primarily serving industries including oil and gas, mining, and construction. Key demand drivers include the growing complexity of projects and the necessity for efficient resource allocation. Compared to other segments within the service type category, Procurement Management exhibits strong growth due to the increasing trend of procurement outsourcing. This segment's expected growth rate of 11.2% aligns with a heightened focus on optimizing procurement processes and reducing costs, which is critical in projects where margins are tight. Its strategic importance in facilitating timely and cost-effective project execution distinguishes it from other segments, including Engineering and Design, which reflect different operational dynamics and growth trajectories.
Construction Management segment is expected to reach USD 10.2 billion by 2033. This segment oversees the construction phase of projects, ensuring they adhere to planned timelines, budgets, and quality standards. Clients in industries including Oil and Gas, Mining and Metals, and Power and Utilities apply construction management services to enhance operational efficiency and project execution. The anticipated growth of this segment reflects a compound annual growth rate (CAGR) of 12.7%, driven by rising project complexity and the demand for specialized management skills. Compared to other service types, including Procurement Management and Engineering and Design, which exhibit lower growth rates, construction management highlights a stronger market position. The ongoing focus on infrastructure development further fuels demand, reinforcing its significance in the Engineering, Procurement, and Construction Management (EPCM) market.
Project Management and Controls segment is projected to grow at a CAGR of 12.7% during the forecast period. This segment helps projects meet their goals through effective planning, execution, and monitoring. It serves construction companies and project owners who require structured oversight to deliver projects on time and within budget. Increasing complexity in construction projects drives demand for advanced project management techniques, which is crucial for mitigating risks and enhancing productivity. Compared to other service types, this segment exhibits faster growth due to its essential nature in navigating project intricacies. The overall effectiveness in project delivery hinges on the capabilities found within project management and controls, highlighting its value relative to engineering and construction management services in the market.
Commissioning support ensures that projects are completed according to specifications and operational standards. This service is provided primarily by project owners and operators in various industries, particularly in Oil and Gas, Power and Utilities, and Infrastructure. Increasing project complexity drives demand for commissioning support, owing to the heightened need for operational efficiency and regulatory compliance. This segment differentiates itself from others within the service type by focusing on the final steps of project execution, emphasizing thorough testing and validation processes before project handover. Given the high level of expertise required, commissioning support often incurs higher costs compared to other service types, reflecting its specialized nature. This emphasis on quality assurance enhances overall project performance and reduces risk, contributing to the broader objectives of the Engineering, Procurement, and Construction Management (EPCM) market.
This segment serves companies focused on oil extraction, refining, and distribution. Significant investment in renewable energy initiatives drives demand for enhanced operational efficiency and reduced costs. The push for sustainability leads to increased investment in technologies that minimize environmental impact, creating opportunities for growth. Compared to other segments, including Mining and Metals, Oil and Gas experiences relatively slower growth due to stricter regulations and fluctuating commodity prices. However, substantial ongoing demand for energy sources ensures that the segment remains a critical area in the Engineering, Procurement, and Construction Management (EPCM) market.
Mining and Metals segment is estimated to reach USD 9.1 billion by 2033, at a CAGR of 12.3% during the forecast period. This segment is essential in the extraction and processing of minerals and metals, serving various industries including construction and manufacturing. The rising global demand for metals, driven by infrastructure development and renewable energy projects, significantly influences growth in this segment. Investment in mining projects, combined with advancements in extraction technologies, supports operational efficiency and enhances production capacity. Compared to other segments, including Oil and Gas, the Mining and Metals segment exhibits faster growth, with a robust CAGR of 12.3%, reflecting a stronger market response to increasing mineral demand and an expanding industrial base. While challenges related to environmental regulations persist, the focus on sustainable practices drives innovation and investment within the market.
The Chemicals and Petrochemicals segment is expected to reach USD 4.4 billion by 2033. This segment primarily serves the production of chemical products and petrochemical derivatives, applied across various industries including automotive, construction, and consumer goods. Growth in this area derives from increasing global demand for chemicals, driven by industrial expansion and rising consumer needs. The segment differentiates itself through a relatively slower growth rate, with a compound annual growth rate (CAGR) anticipated at 4.4% during the forecast period. In contrast, other segments, including Mining and Metals, exhibit higher growth potential with a CAGR of 12.3%. The market experiences pricing pressures due to fluctuating raw material costs, complicating project budgets and timelines.
Power and Utilities segment is projected to grow at a CAGR of 13.3% during the forecast period. This sector supports the provision of essential energy services, including electricity generation, water supply, and waste management, serving municipalities, industrial facilities, and large commercial enterprises. The increasing demand for renewable energy sources significantly influences this segment, driving investments in green and sustainable technology projects. Regulatory support for energy transition initiatives enhances the creation of infrastructure necessary for power generation and distribution. Compared to other segments, the growth rate in Power and Utilities stands out, reflecting a strong response to the global push for energy efficiency and sustainability. Other segments do not face this challenge to the same extent. The anticipated value of the segment reaches USD 4.4 billion by 2033, positioning it as a key area of focus in the Engineering, Procurement, and Construction Management (EPCM) market.
Industrial manufacturing encompasses a wide variety of production processes, from assembly lines to complex manufacturing systems. This sector serves industries including automotive, electronics, and consumer goods, relying heavily on engineering, procurement, and construction management services to optimize efficiency and reduce costs. Demand within this segment is driven by technological advancements and the ever-increasing emphasis on automation and digitization. Unlike other segments, industrial manufacturing typically sees slower growth, influenced by heavy competition and fluctuating raw material prices. The need for innovative solutions and efficient project delivery remains critical for players in this sector to maintain a competitive edge. Regulatory compliance presents unique challenges in industrial manufacturing, where adherence to safety standards and quality assurance is essential.
The Pharmaceuticals and Biotechnology segment is essential in the development and production of medications and medical technologies. This segment serves pharmaceutical companies and biotechnology firms that require specialized engineering, procurement, and construction management services to support complex projects, including drug manufacturing facilities and laboratory environments. Investment in research and development significantly influences this segment, driving innovation and rapid advancements in biopharmaceutical production. Competition for skilled labor and advanced technologies presents challenges that affect project timelines and budgets. Compared to other segments, the Pharmaceuticals and Biotechnology segment typically demands higher precision and compliance with stringent regulatory standards, leading to more complex project dynamics. This distinct need for quality and regulatory adherence sets it apart from other segments, highlighting its significance within the Engineering, Procurement, and Construction Management (EPCM) market.
Semiconductors and electronics involve the design and production of components essential for various electronic devices. Key players in this segment include manufacturers of integrated circuits, microprocessors, and various electronic assemblies. Demand for these components stems from the growing need for advanced technology in areas including consumer electronics, telecommunications, and automotive applications. Rapid advancements in technology drive innovation and investment in new semiconductor designs and production methods. This sub-segment differentiates itself from others in the end-use industry by focusing on advanced technology and high-volume production, often leading to larger projects than found in traditional sectors. Factors influencing growth include increasing integration of electronics in everyday products and the push for more energy-efficient technologies, creating significant opportunities for suppliers within the Engineering, Procurement, and Construction Management (EPCM) market.
Infrastructure encompasses the foundational facilities and systems vital for economic activity, including transportation networks, utilities, and public works. This segment attracts investment from government entities, private developers, and public-private partnerships aiming to enhance societal infrastructure. Growth is driven by increasing urbanization, which intensifies the demand for modern infrastructure solutions. Regulatory factors, including government incentives and funding for infrastructure projects, significantly influence investment decisions. Unlike other segments, infrastructure often involves longer project timelines and higher initial costs, making it a different proposition for stakeholders. This sub-segment's focus on large-scale projects contrasts with the faster growth projected in sectors including mining and metals, which appeal to different buyer profiles and project types. The Engineering, Procurement, and Construction Management (EPCM) market continues to adapt to these dynamics, emphasizing the importance of infrastructure for sustainable development.
Data centers and commercial facilities encompass a growing area focused on providing infrastructure for digital operations and physical spaces for commerce. This segment is used by technology firms, commercial real estate developers, and service providers looking to enhance their operational capabilities. Demand for these facilities derives from the increasing reliance on cloud computing and the expansion of online services, driving construction efforts to meet modern standards. While segments like Oil and Gas and Power and Utilities experience more rapid growth, the unique requirements of data centers, including advanced cooling systems and power management, set it apart. Infrastructure needs differ significantly from other segments, often resulting in a higher cost per project, reflecting the specialized nature of the construction involved. The Engineering, Procurement, and Construction Management (EPCM) market evolves to accommodate these specialized demands while addressing the increasing complexity of compliance and technological integration.
Greenfield Projects segment is valued at USD 9.7 billion in 2026 and is projected to reach USD 19.5 billion by 2033, at a CAGR of 10.5% during the forecast period. This segment caters to industries seeking to develop new sites for production or infrastructure, focusing on construction, initial facility establishment, and operational readiness. Major contributors to growth include increased investments in renewable energy and infrastructure projects, particularly in emerging economies. Compared to other project types, including Brownfield Projects, Greenfield Projects typically require higher initial capital and longer timelines but present opportunities for innovation and modern standards in design and execution. The market benefits from a shift toward sustainable practices, propelling demand for eco-friendly construction methods and technologies. Growth in this segment significantly influences overall market dynamics, attracting investment and enhancing competition among key players in the market.
Brownfield Projects segment is estimated to reach USD 17.1 billion by 2033, at a CAGR of 13.1% during the forecast period. This segment focuses on the renovation, upgrading, or expansion of existing facilities, often requiring specific expertise in understanding the complexities of the current infrastructure. Industries including oil and gas, mining, and power utilities heavily invest in these projects to enhance operational efficiency and extend the lifespan of their assets. Demand for brownfield projects is driven by the increasing need for modernization and compliance with environmental regulations. Compared to greenfield projects, which typically involve new construction, brownfield projects entail lower costs and shorter timelines due to the existing infrastructure. This segment exhibits a faster growth rate than others, reflecting heightened investment in improving and optimizing existing sites.
Private project ownership is valued at USD 11.5 billion in 2026 and is projected to reach USD 24.5 billion by 2033, at a CAGR of 11.4% during the forecast period. This segment encompasses projects funded and owned by private entities, including corporations and individual investors, who seek to maximize returns on investment through strategic development. The growth of this segment is driven by an increasing focus on infrastructure development and the expansion of private sector participation in various industries. Compared to other ownership categories, private project ownership typically experiences faster growth, with a more significant emphasis on innovative and efficient project delivery methods. In particular, the private segment stands out for its ability to respond rapidly to market demands and capitalize on emerging opportunities, positioning it favorably within the EPCM market.
Public and State-Owned segment is estimated to reach USD 9.9 billion by 2033, at a CAGR of 12% during the forecast period. This segment typically includes projects funded or owned by government entities, which strive to deliver essential services and infrastructure to the public. Demand grows due to increased government spending on infrastructure development and public utilities, boosting investment in construction projects. Compared to other ownership types, this segment often experiences a more stable demand pattern due to government backing. Regulatory frameworks supporting public projects create opportunities for growth, particularly in regions prioritizing infrastructure upgrades. The higher CAGR of 12% reflects a robust investment environment driven by government focus on modernization and sustainability initiatives, which drives the expansion of this segment in the Engineering, Procurement, and Construction Management (EPCM) market.
Public-Private Partnerships segment is expected to reach USD 2.3 billion by 2033. This segment facilitates collaboration between government entities and private sector companies to deliver public infrastructure projects. Such partnerships are commonly used for transportation, utilities, and other public services, allowing for shared investment and risk management. Growth in this segment is driven by increasing demand for efficient public services and limited government budgets. The projected CAGR of 12% highlights its rising importance compared to other ownership types, which tend to grow at slower rates. By focusing on innovative financing structures and enhanced project delivery methods, this segment differentiates itself through its collaborative approach to project ownership. The Engineering, Procurement, and Construction Management (EPCM) market benefits from this model, enhancing project execution and optimizing resource allocation.
Based on geography, the Global Engineering, Procurement, and Construction Management (EPCM) market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Strong demand for the Engineering, Procurement, and Construction Management (EPCM) market in North America derives from critical sectors including oil and gas, mining and metals, and power and utilities. The region's advanced infrastructure supports extensive energy projects, enhancing operational efficiency and supporting growth in associated industries. North America is projected to reach USD 15.6 billion by the end of 2033, reflecting significant investment in energy and natural resource sectors. The focus on sustainable practices and green technology influences project management strategies, aligning with regulatory frameworks that support environmental standards. The share of the global market in 2025 stands at 46.4%, highlighting North America's crucial position within the overall industry landscape. Investment in brownfield and greenfield projects increases capacity, catering to increasing energy demands and modernization initiatives.
The European market for Engineering, Procurement, and Construction Management (EPCM) demonstrates significant activity driven by robust industries including Oil and Gas and Mining and Metals. Countries including Germany, France, and the UK are key players, with investments focused on improving energy efficiency and sustainability. Increased infrastructure development and government initiatives promote growth in this region, particularly in the context of green technologies. Key projects in Italy and Spain align with broader strategies aimed at reducing carbon emissions, enhancing market demand. The market holds a share of 15.00% in 2025. Continuous advancements in project management and controls contribute to the overall growth trajectory of the market, especially in addressing complex regulatory requirements within the region.
Rapid industrialization in Asia-Pacific significantly influences the Engineering, Procurement, and Construction Management (EPCM) market. Countries including China and India drive demand through large-scale infrastructure projects and energy sector expansions. Increased investments in renewable energy projects, particularly in Australia and Southeast Asia, contribute to this growth. Skilled labor availability and cost-effective construction methods enhance project feasibility, attracting both public and private investments. The region's share of the global market is projected at 25.6% in 2025. Ongoing urbanization and the rise in living standards create a compelling need for advanced construction solutions. Enhanced regulatory frameworks in these countries increase confidence in project execution, further fueling market expansion. Strong competition among local firms and international players positions the region as a dynamic hub for EPCM services.
Growth in the Engineering, Procurement, and Construction Management (EPCM) market within South America is driven primarily by the oil and gas sector, particularly in Brazil and Argentina. Investment in infrastructure development, along with a focus on renewable energy projects, influences demand. Brazil emerges as a key player in the EPCM landscape due to significant natural resource reserves. In Argentina, regulatory changes aimed at enhancing foreign investments in energy projects support market activity. The market is expected to benefit from increased public-private partnerships aimed at addressing infrastructure gaps and promoting economic growth.
Saudi Arabia and the UAE stand out as key players in the Engineering, Procurement, and Construction Management (EPCM) market, driven by substantial investments in infrastructure and energy projects. South Africa's expanding mining and metals sector further enhances regional demand for EPCM services. The Middle East and Africa region benefits from initiatives aimed at diversifying economies and boosting non-oil sectors, which create a competitive environment for project development. With a projected market share of 7.1% in 2025, growth in this region reflects ongoing efforts to enhance local capabilities and attract foreign investment. The market anticipates significant contributions from both public and private sectors, particularly in large-scale projects aimed at promoting sustainable development and technological advancements.
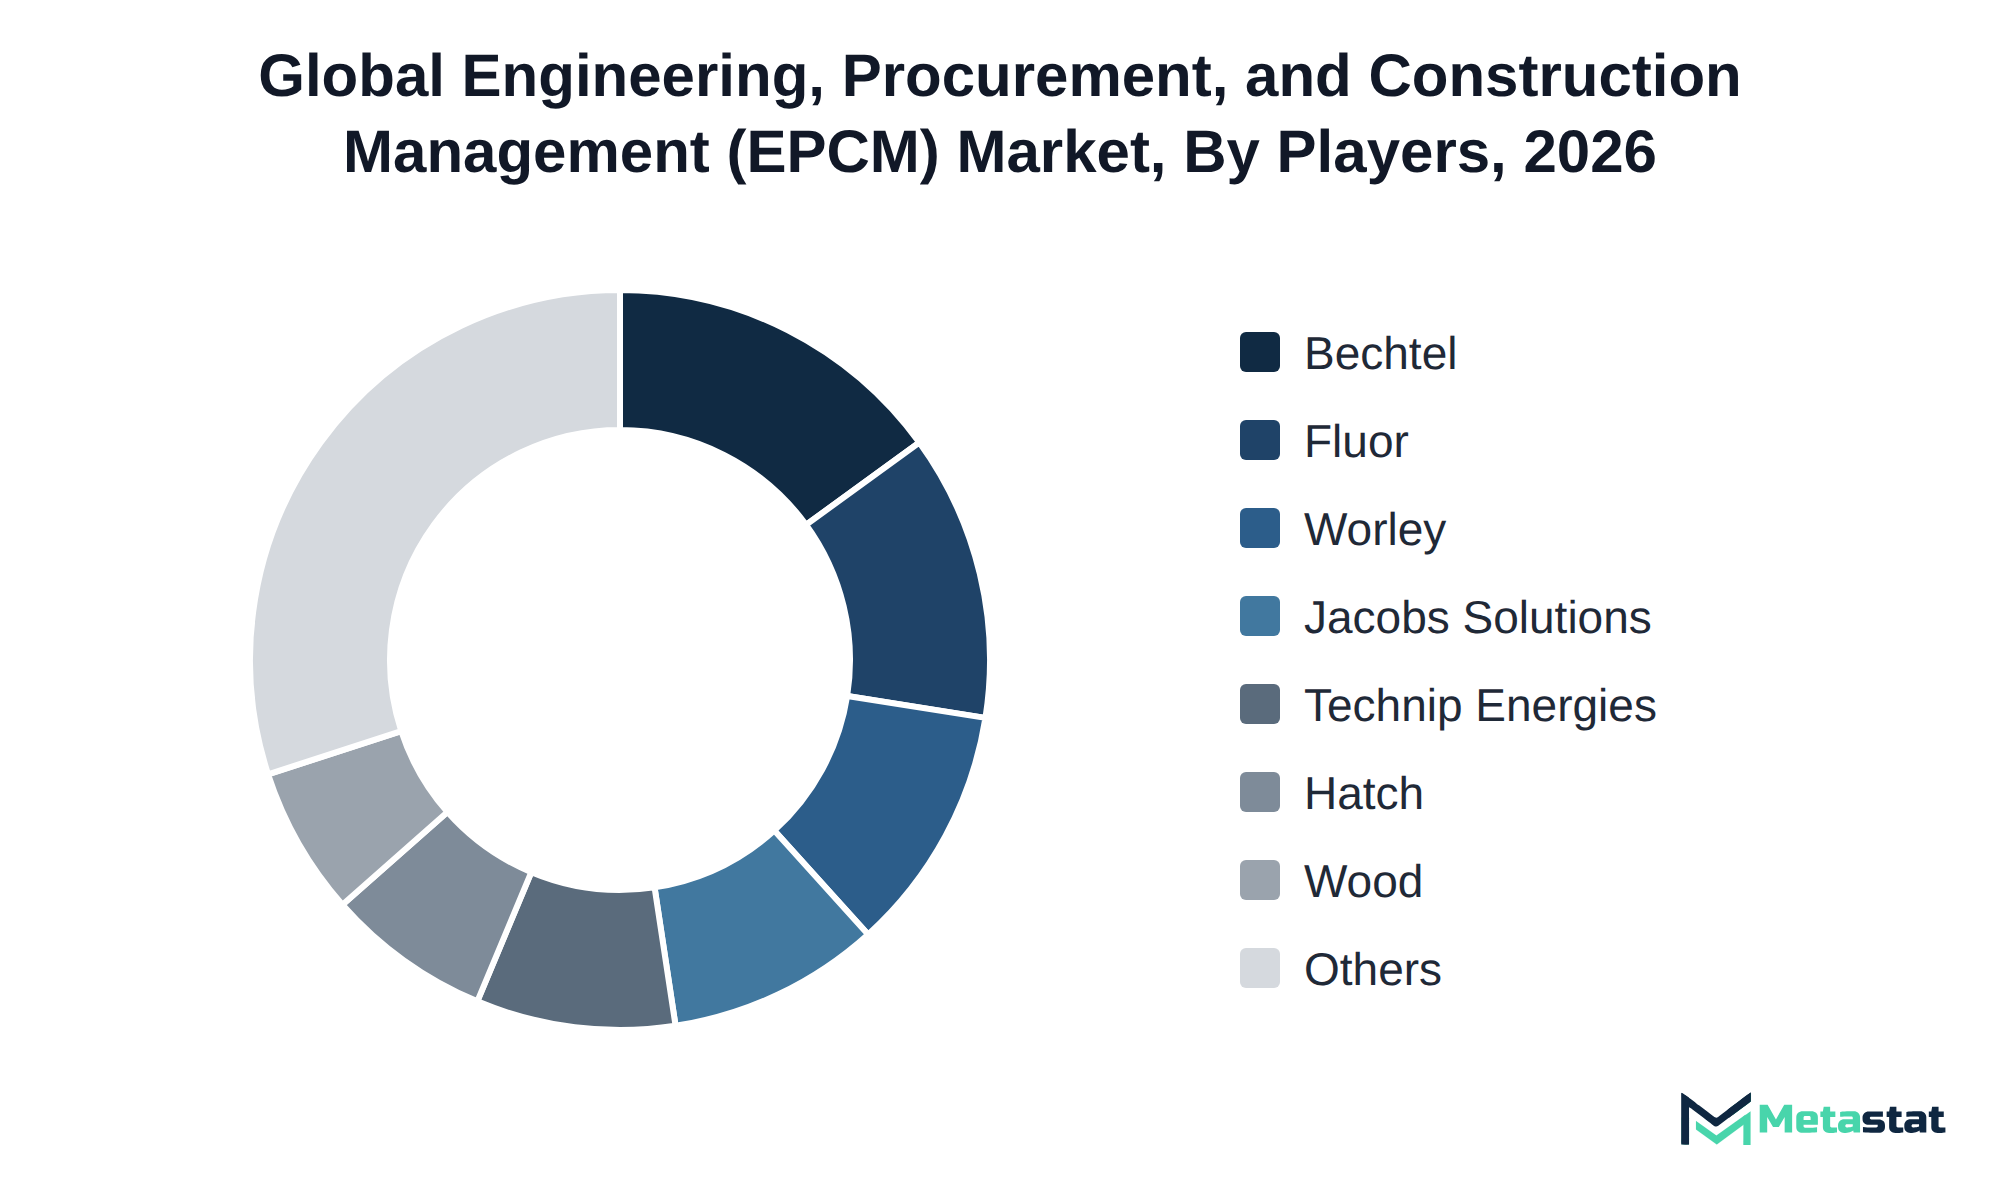
Companies in the Engineering, Procurement, and Construction Management (EPCM) market differentiate themselves based on service type, project ownership, and end-use industry. Service offerings include engineering and design, procurement management, construction management, and project management and controls, each addressing distinct client needs. For instance, Worley Limited focuses on engineering and design services, while Bechtel Corporation emphasizes construction management to support large-scale projects.
Buyers prioritize factors including price, service quality, customization, and certification when selecting EPCM providers. Technip Energies N.V. excels in offering tailored solutions for the oil and gas sector, catering to specific regulatory requirements and client preferences. Firms like Jacobs Solutions Inc. emphasize extensive experience across various industries, leveraging their reputation to attract clients seeking reliable project management support in complex environments.
Reaching the projected USD 36.7 billion by 2033 involves several developments within the Engineering, Procurement, and Construction Management (EPCM) market. This growth aligns with rising investments in infrastructure and new facility construction, particularly in North America, where spending is robust. Advancements in project management and controls are anticipated to enhance efficiency across various industries, strengthening the market's foundation. However, a primary risk involves potential delays or cost overruns linked to regulatory changes or supply chain disruptions that could impede project timelines. Such challenges could disproportionately affect industries including oil and gas, where project timelines are critical. Balancing these developments and risks will ultimately determine whether the market achieves its ambitious growth target.
By Service Type: Engineering and Design, Procurement Management, Construction Management, Project Management and Controls, Commissioning Support
By End-Use Industry: Oil and Gas, Mining and Metals, Chemicals and Petrochemicals, Power and Utilities, Industrial Manufacturing, Pharmaceuticals and Biotechnology, Semiconductors and Electronics, Infrastructure, Others (Data Centers and Commercial Facilities)
By Project Type: Greenfield Projects, Brownfield Projects
By Project Ownership: Private, Public and State-Owned, Public-Private Partnerships
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Engineering, Procurement, and Construction Management (EPCM) market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 11.7% from 2026 to 2033 |
|
Revenue Unit |
USD billion |
|
Segmentation |
By Service Type, End-Use Industry, Project Type, Project Ownership, and Region |
|
By Region |
North America (By Service Type, End-Use Industry, Project Type, Project Ownership, and Country)
|
|
Europe (By Service Type, End-Use Industry, Project Type, Project Ownership, and Country)
|
|
|
Asia Pacific (By Service Type, End-Use Industry, Project Type, Project Ownership, and Country)
|
|
|
South America (By Service Type, End-Use Industry, Project Type, Project Ownership, and Country)
|
|
|
Middle East and Africa (By Service Type, End-Use Industry, Project Type, Project Ownership, and Country)
|
Find answers to common questions about this report
The Engineering, Procurement, and Construction Management (EPCM) market size was valued at USD 15.1 billion in 2025.
The market is projected to grow at a CAGR of 11.7% during the forecast period from 2026 to 2033.
The North America Engineering, Procurement, and Construction Management (EPCM) market size is projected to reach USD 15.6 billion by 2033.
Engineering and Design leads the market with a projected value of USD 13.9 billion by 2033, based on its significant share compared to other service types.
Key drivers for the Engineering, Procurement, and Construction Management (EPCM) market include investment in greenfield projects, particularly in the oil and gas, mining and metals, and power and utilities sectors. Adoption of innovative technologies enhances project execution and overall efficiency, supporting market growth.
North America holds the dominant share of the Engineering, Procurement, and Construction Management market, with a value of USD 15.6 billion in 2033, representing 46.4 percent of the total market.
Compliance with stringent regulatory requirements restrains growth in the Engineering, Procurement, and Construction Management (EPCM) market by slowing project approvals and increasing costs. Rising expenses related to talent acquisition and retention challenge firms in maintaining competitive pricing for services.
Investment in greenfield projects and the adoption of innovative technologies significantly favor adoption in the Engineering, Procurement, and Construction Management (EPCM) industry. Enhanced project execution efficiency and the need for specialized services to navigate increasing project complexities drive demand among stakeholders in sectors including oil and gas, mining, and power.
The Engineering, Procurement, and Construction Management (EPCM) market is estimated to reach a valuation of USD 36.7 billion by 2033.
Key players operating in the Engineering, Procurement, and Construction Management (EPCM) market include Worley Limited, Fluor Corporation, Bechtel Corporation, KBR, Inc., Jacobs Solutions Inc., AECOM, Black & Veatch, and Burns & McDonnell.
The analysts below cover Professional Services research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.
PRINCIPAL CONSULTANT - QUALITY SYSTEMS & COMPLIANCE
Electronics and Semiconductor · Machinery & Equipment · Professional Services
Omkar Phadtare is an Industry Consultant at MetaStat Insight, specializing in quality systems, regulatory compliance, and standards benchmarking to drive data-driven market intelligence and strategic industry research.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Transitioning ultra-class mining haul trucks to alternative power requires concrete data on remote hydrogen refueling infrastructure economics. The report evaluated megawatt-scale electrolyzer installation expenses, onsite storage safety mandates, and heavy-duty fuel cell stack degradation under continuous duty cycles. That technical rigor helped our engineers benchmark realistic total operating cost horizons for off-highway fleet decarbonization.
Enterprise zero-trust network rollouts are often slowed down by multi-cloud transit latency and proprietary hardware retirement schedules. This study provided realistic total cost of ownership models comparing cloud-delivered security edge solutions against traditional hardware refreshes. The analysis of contract renewal lengths and software maintenance fees gave us clear visibility into enterprise replacement cycles over the next three to five years.
Scaling antibody-drug conjugate manufacturing hinges on contract manufacturing availability for high-potency active ingredients. The MetaStat Insight analysis looked closely at global cleanroom slot constraints, bioconjugation batch failure rates, and supply chain redundancies between the US, Europe, and India. The supplier capability matrix proved genuinely useful for our team when mapping secondary source options across our clinical pipeline.
Explore related market intelligence reports worth reading alongside this one.