
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Opto Semiconductors Market Size, Share, By Product Type (Light-Emitting Diodes, Image Sensors, Laser Diodes, Photodiodes and Phototransistors, Optocouplers and Optical Solid-State Relays), By Active Semiconductor Material (Silicon, Gallium Nitride and Indium Gallium Nitride, Gallium Arsenide and Aluminum Gallium Arsenide, Indium Phosphide, Aluminum Gallium Indium Phosphide), By Application (Imaging and Machine Vision, Lighting and Illumination, Displays and Backlighting, Optical Data Transmission, Non-Imaging Sensing and Ranging, Galvanic Isolation), By End-Use Industry (Consumer Electronics, Automotive and Transportation, Telecommunications and Data Centers, Industrial and Manufacturing, Building and Lighting, Healthcare and Life Sciences, Security and Surveillance), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-2443
Published
November, 2026
Pages
261 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
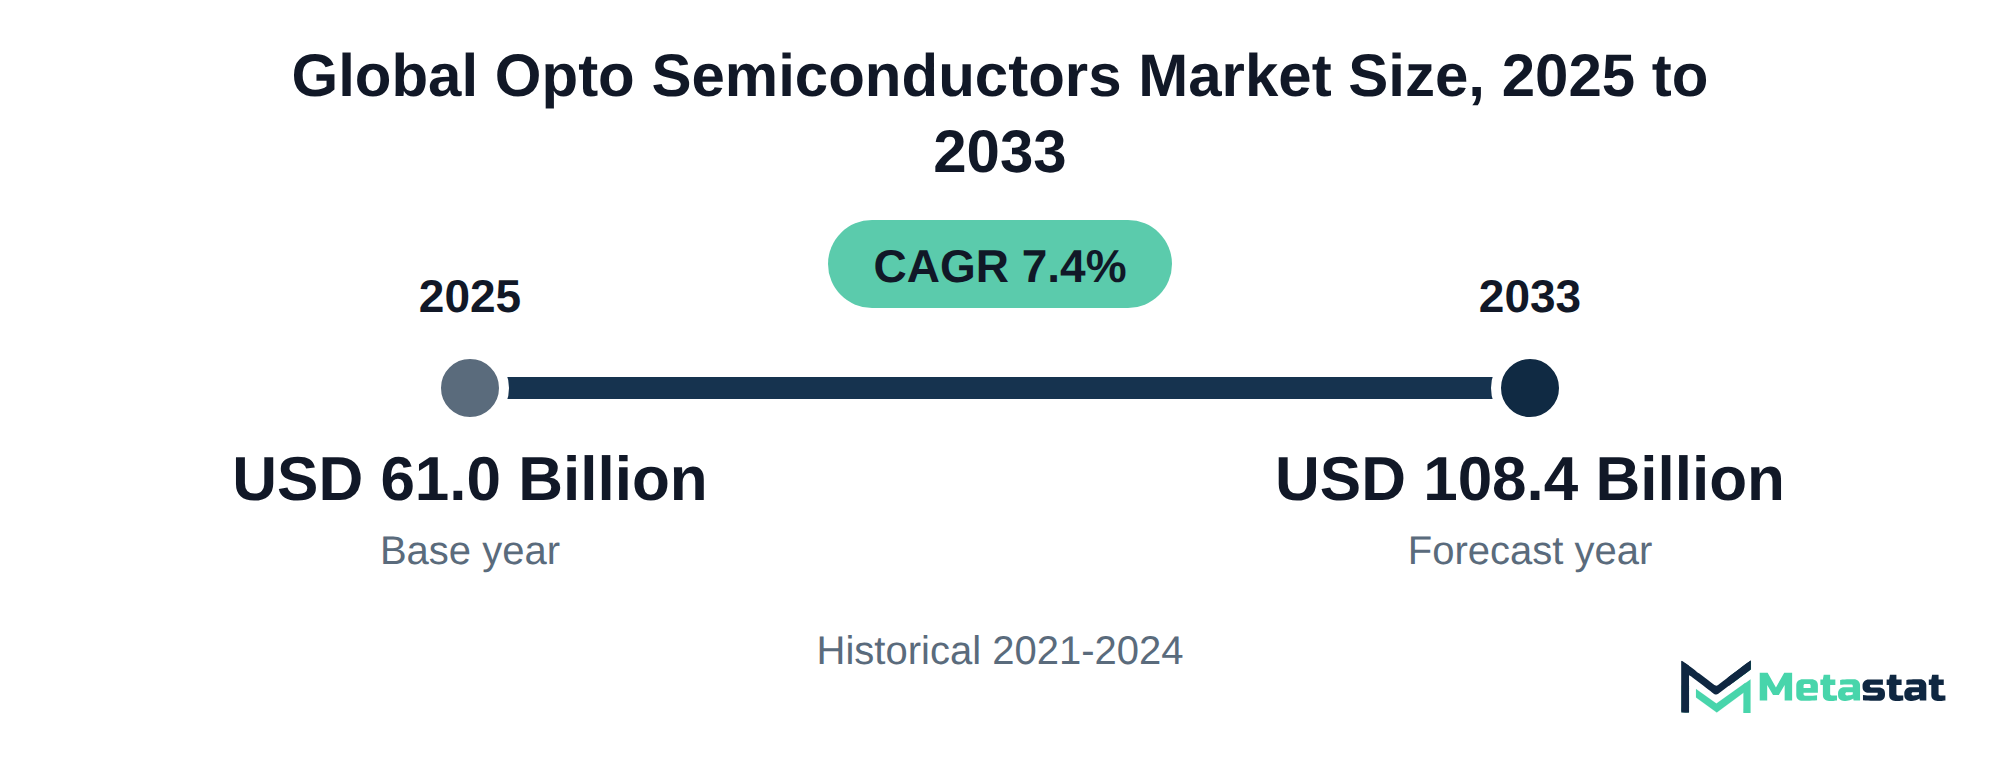
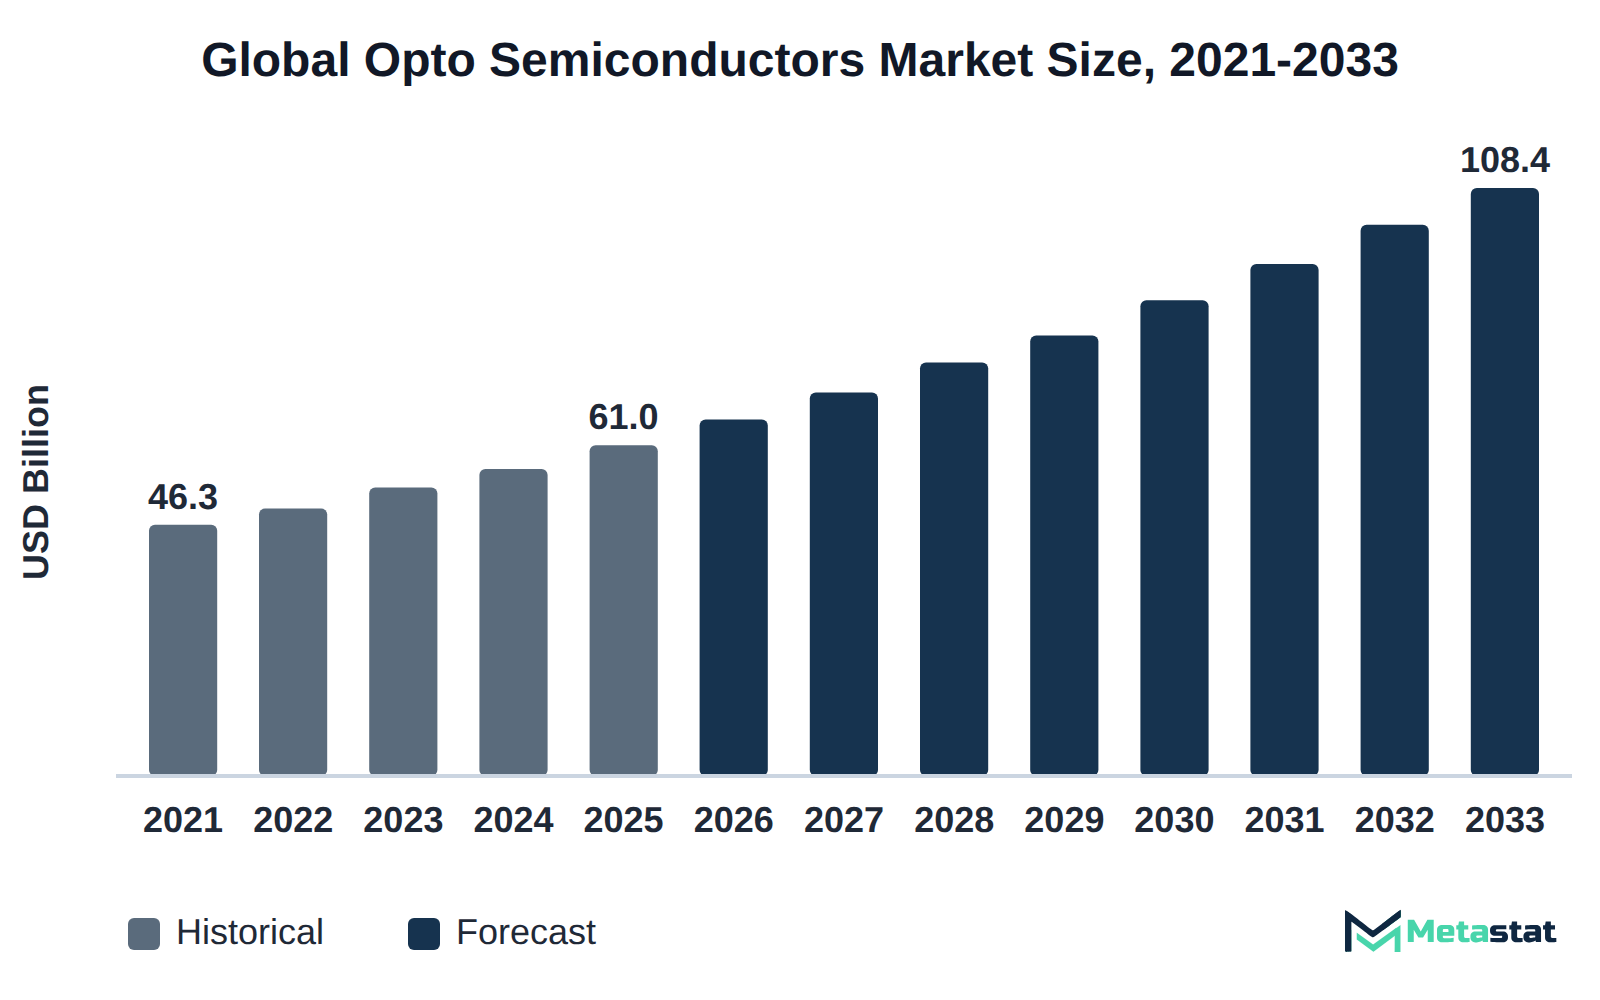
Market Valuation: Valued at $61 Billion in 2025, projected to reach $108.4 Billion by 2033 at a 7.4% CAGR.
Dominant Segment: The image sensors segment leads the market, driven by increasing demand for precision in automotive and machine vision applications.
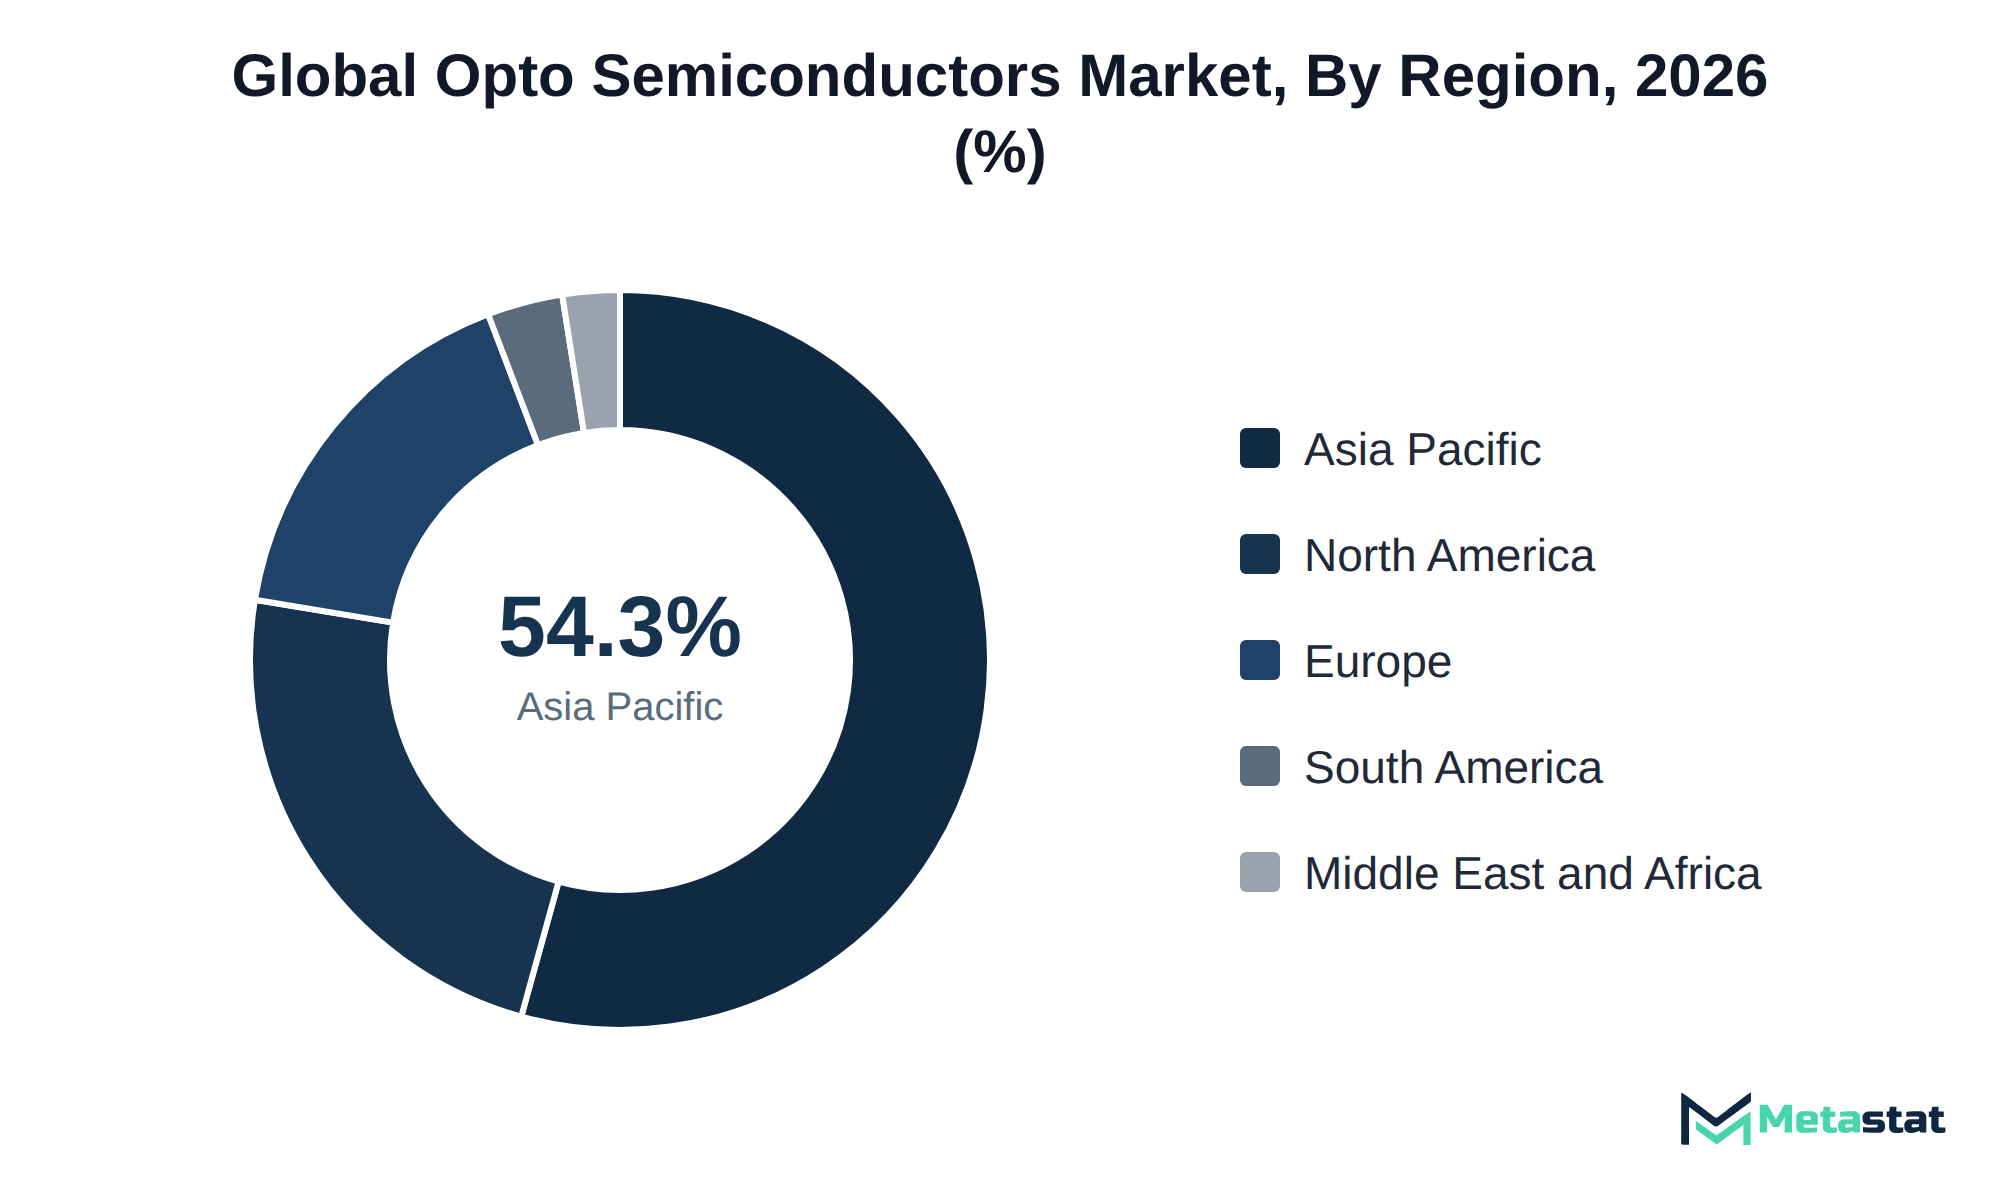
Geographic Lead: Asia Pacific commands the largest market share at 54.3%, supported by robust manufacturing capabilities and technological advancements.
What's Inside: This report provides comprehensive competitive coverage, detailed analyses, and forecasts from 2026 to 2033, focusing on various product types and applications.
Growing Demand for Imaging Applications: There is a notable surge in demand for imaging and machine vision applications, fueled by advancements in automation and artificial intelligence across multiple industries.
Advancements in Laser Diode Technology: Innovations in laser diode technology are driving significant growth, enhancing applications in telecommunications and industrial systems.
Choose Your License
Global Opto Semiconductors Market
The global Opto Semiconductors market was valued at USD 61 billion in 2025 and is projected to reach USD 108.4 billion by 2033, growing at a CAGR of 7.4% over the forecast period.
The Opto Semiconductors market encompasses various products, including light-emitting diodes, image sensors, and laser diodes, among others. Buyers invest in this market due to increasing demand for advanced electronic devices, which require high-quality opto semiconductor components for improved performance. Applications span consumer electronics, telecommunications, and automotive sectors, prompting significant spending on these technologies.
Growth in the market is driven by rising demand for imaging and machine vision applications, particularly in industrial automation and security systems. The image sensors segment represents the largest value within the market, contributing significantly to overall revenues. In terms of regional distribution, Asia Pacific dominates with a 54.3% share, reflecting robust manufacturing capabilities and technological advancements in this region.
North America holds 23.3% of the market in 2025, with the US leading in 2026. This region benefits from strong investments in research and development, which enhance innovation in opto semiconductor technologies. Industries increasingly adopt these components for various applications, and the market is projected to continue its upward trajectory throughout the forecast period.
The market includes a range of opto semiconductor components that serve various applications, which drives significant spending from buyers across multiple industries. Key sectors including consumer electronics, automotive, and telecommunications drive demand for these products, reflecting the critical role of opto semiconductors in modern technology. Buyers prioritize these components for their ability to enhance performance and efficiency in devices, contributing to overall operational success.
Growth in the market is fueled by rising demand for advanced imaging technologies and the increasing integration of opto semiconductor solutions in consumer devices. Image sensors represent the segment with the most value, leveraging advancements in technology to improve image quality and functionality. Meanwhile, the Asia Pacific region commands the largest share at 54.3%, highlighting its significance in global production and innovation.
A primary growth driver is the expansion of machine vision applications across industries, which improves automation and process precision. This trend reflects a broader shift towards smart manufacturing and interconnected systems, positioning the opto semiconductors market for sustained growth. Ongoing technology development encourages further investment in this sector.
Opto semiconductors enhance data transfer speeds within high-speed data center links. The shift towards higher bandwidth requirements in data centers reflects the growing demand for efficient optical communication systems. By 2033, the optical data transmission application segment is projected to experience significant growth, supported by a compound annual growth rate (CAGR) of 15.5%. This demand stems from the increasing need for rapid data processing and transmission, driven by advancements in cloud computing and big data analytics.
Image sensors, another major opto semiconductor segment, are expected to reach USD 54 billion by 2033, reflecting their role in enhancing high-speed data center links. These sensors enable real-time data capture and processing, ensuring integration with optical communication systems. The growth of these technologies leads to improved operational efficiencies for data centers, allowing for greater scalability and responsiveness to evolving market demands.
The adoption of opto semiconductors in high-speed data center links facilitates enhanced performance and influences competitive positioning within the market. While data centers upgrade their infrastructure to meet rising data traffic, investments in advanced optical technologies become essential. This trend shows the ongoing transition towards opto semiconductors and their importance to digital communication.
Purchasing arrangements for image sensors in the automotive and machine vision sectors often involve long-term contracts that ensure stability in supply and price. These contracts reflect the increasing demand for precision in imaging applications, driven by advancements in technology. Image sensors are essential for applications ranging from driver assistance systems to automated inspection processes. The segment of image sensors in the opto semiconductors market is projected to reach USD 54 billion by 2033, highlighting its significance in various industries.
Pricing models for image sensors typically range from fixed to variable structures, depending on factors including volume commitments and technological integration. Suppliers often provide tiered pricing, which rewards larger orders with lower per-unit costs. This structure incentivizes automotive manufacturers and machine vision providers to commit to higher volumes, ensuring consistent quality and innovation in their product offerings. Such purchasing strategies mitigate risks associated with fluctuating market prices, especially in a sector characterized by rapid technological advancements.
The growth of image sensor applications contributes significantly to revenue stability for suppliers in the market. Automotive manufacturers increasingly invest in advanced image processing capabilities, further driving demand for high-quality sensors. As the market expands, integrating advanced imaging technologies into automotive and machine vision applications is expected to strengthen partnerships between buyers and suppliers and improve market dynamics.
MicroLED technology is transforming displays and backlighting in the Opto Semiconductors market, delivering superior performance compared to traditional technologies. This advancement addresses the growing demand for high-resolution displays, particularly in consumer electronics, where image quality is critical. In the segment of displays and backlighting, MicroLED features high brightness, low power consumption, and high color accuracy, making it a favorable choice for manufacturers aiming to enhance user experience.
By 2033, the displays and backlighting segment is projected to reach a value of USD 9.4 billion, reflecting increasing adoption rates across various applications. Buyers in this market prioritize efficiency and quality, driving the need for innovative solutions that reduce energy consumption while improving visual performance. While these buyers seek advanced technologies, MicroLED becomes a compelling option, offering longer lifespans and improved durability compared to OLED and LCD alternatives.
The shift towards MicroLED adoption influences purchasing decisions and positions suppliers to capitalize on emerging trends in the Opto Semiconductors market. This technology's potential for integration in large-scale displays, including those used in advertising and public information, enhances commercial opportunities for businesses focused on high-quality visual solutions.
Opto semiconductors play a significant role in enhancing vehicle lighting and sensing systems. The integration of light-emitting diodes (LEDs) and image sensors significantly contributes to improved visibility and safety in vehicles. In 2026, the imaging and machine vision application segment, which includes these technologies, is expected to achieve a value of USD 32 billion, with projections indicating growth to USD 49.7 billion by 2033, reflecting a compound annual growth rate of 6.5%.
This growth stems from the increasing demand for advanced driver-assistance systems (ADAS) that employ opto semiconductors for features including adaptive headlights and collision avoidance. These systems enhance vehicle safety and driver convenience, creating a surge in demand among automotive manufacturers. The capability to employ opto semiconductors for high-resolution imaging enables vehicles to respond to their surroundings more effectively, improving overall performance and functionality.
Wider use of opto semiconductors in vehicle lighting and sensing improves the driving experience and shapes commercial strategies within the automotive industry. Manufacturers focusing on these technologies experience competitive advantages, positioning themselves favorably in a changing market. With the opto semiconductors market evolving, stakeholders are likely to prioritize investments in innovative lighting and sensing solutions that enhance vehicle safety and efficiency.
Growing demand for image sensors from sectors like automotive and machine vision drives significant investment in opto semiconductor solutions. Buyers in these industries seek advanced imaging capabilities for applications including driver assistance systems and robotics. This shift toward integrating sophisticated imaging technology has resulted in an increase in production volumes, leading to competitive pricing in the market. Image sensors are projected to reach a value of USD 54 billion by 2033, reflecting a compound annual growth rate of 6.9%. Investment in this segment signifies a strategic move to enhance efficiency and performance across various applications.
Innovations in laser diode technology drive significant growth in the Opto Semiconductors market. Enhanced efficiency and performance characteristics from new materials and designs enable superior functionality in applications including optical data transmission and industrial lasers. Increased interest in high-precision medical devices and advanced manufacturing processes requires more robust and versatile components, pushing demand for laser diodes upward. The integration of laser diodes in telecommunications and consumer electronics leads to rapid advancements in data transmission capabilities, enhancing overall market value.
Growing reliance on laser diodes for various applications influences manufacturers to invest in research and development. Companies focus on refining production techniques, resulting in higher-quality outputs and reduced costs. These advancements facilitate market penetration into emerging sectors, including augmented reality and automotive lighting systems. The continuous evolution of laser diode technology enhances operational efficiencies in existing applications and creates new opportunities within the Opto Semiconductors market.
Increasing costs for opto semiconductor components hinder purchasing decisions across various industries. Buyers, particularly in consumer electronics and automotive sectors, experience significant financial constraints that lead to smaller order quantities and slower adoption of new technologies. This restraint manifests through delayed product replacements and reluctance to invest in advanced opto semiconductor solutions. Rising prices for active materials, including Silicon and Gallium Nitride, contribute to this challenge, making it difficult for manufacturers to maintain profit margins while meeting customer demand.
The Opto Semiconductors market faces pressure from both raw material costs and increasing competition, which forces firms to optimize pricing strategies. Consequently, manufacturers find it challenging to balance competitive pricing with product quality. These dynamics significantly impact market growth, leading to a cautious approach among buyers when considering investments in opto semiconductor technologies.
Increasing costs for raw materials challenge profitability across the supply chain in the opto semiconductors market. Factors including inflation and supply chain disruptions contribute to rising prices, leading suppliers to adapt by seeking alternative materials or enhancing operational efficiencies. Many manufacturers are investing in advanced production technologies to reduce waste and lower energy consumption, aiming to mitigate the impact of these financial pressures. This strategy allows suppliers to maintain competitive pricing while addressing rising input costs. The strategic shift toward more sustainable practices and sourcing reflects a broader market trend focused on environmental responsibility. These measures support short-term profitability and align with long-term sustainability goals, which keeps suppliers resilient amid fluctuating market conditions. This evolving environment shapes competitive strategies and influences the overall health of the market, with suppliers prioritizing innovation and efficiency to secure their position.
Imaging and machine vision applications present a notable opportunity within the opto semiconductors market. The surge in demand is driven by advancements in automation and artificial intelligence across various industries, enhancing the need for high-performance imaging solutions. Sectors including healthcare, automotive, and security increasingly rely on imaging technologies for improved precision and efficiency. As these industries adopt more sophisticated imaging systems, opto semiconductor suppliers focused on imaging and machine vision applications stand to benefit significantly, positioning themselves for substantial revenue growth. These conditions point to continued investment in imaging technologies, which boosts overall market performance.
The Global Opto Semiconductors market is segmented based on Product Type, Active Semiconductor Material, Application, and End-Use Industry.
Light-Emitting Diodes segment is valued at USD 17.3 billion in 2026 and is projected to reach USD 22.6 billion by 2033, at a CAGR of 3.9% during the forecast period. Applications across consumer electronics, automotive, and general lighting industries drive demand for light-emitting diodes, which provide energy-efficient lighting solutions and contribute to overall product performance enhancements. This segment benefits from technological advancements in design and manufacturing processes. Competition pushes innovation, leading to lower costs and wider adoption among manufacturers. Compared to other segments, including image sensors, which have a higher CAGR of 6.9%, growth for light-emitting diodes is more moderate. Nevertheless, consistent demand from various end-use sectors ensures a stable revenue stream, providing manufacturers with opportunities to optimize their production capabilities and expand market reach. The market reflects an increasing trend towards energy-efficient lighting solutions, further enhancing the segment's relevance.
This segment is crucial for applications in consumer electronics, automotive, and industrial sectors where image capturing and processing is essential. Demand from automotive manufacturers and machine vision specialists drives growth, highlighting the importance of high-resolution imaging capabilities. Unlike other segments, including Light-Emitting Diodes, which exhibit a slower growth rate of 3.9%, Image Sensors see more robust adoption patterns due to advancements in technology and increasing needs for automation in various industries. The push for better imaging technology, along with competitive pricing strategies, positions this segment for sustained growth and makes it central to overall market strategy.
Laser Diodes segment is expected to reach USD 21.6 billion by 2033. These components find application in various fields including telecommunications, medical devices, and industrial systems, performing critical functions in data transmission, precision cutting, and sensing technologies. Innovations in laser diode technology, particularly in efficiency and output power, drive robust demand. This segment experiences a higher growth trajectory compared to others, with a compound annual growth rate (CAGR) of 6.9%. The increasing adoption of laser diodes in consumer electronics, including optical storage devices and laser printers, fuels this growth further. Unlike light-emitting diodes and image sensors, laser diodes often command a premium price due to their specialized applications and advanced capabilities. Such dynamics position the segment as a key driver in the overall market for opto semiconductors.
Photodiodes and Phototransistors segment is projected to grow at a CAGR of 8.7% during the forecast period. These components play essential roles in various applications, including imaging, sensing, and data transmission, primarily serving industries including consumer electronics and telecommunications. Demand for innovative sensing solutions drives growth in this segment, reflecting the increasing deployment of advanced technologies, including smart devices and automation systems. With a distinct growth trajectory, this segment displays a faster growth rate compared to other opto semiconductor segments, including Light-Emitting Diodes, which are projected to grow at a CAGR of 3.9%. Factors including reduced production costs and advancements in sensor technology contribute to the expanding market opportunities, establishing a robust foundation for future investments and development in the Photodiodes and Phototransistors segment.
Optocouplers and Optical Solid-State Relays serve critical functions in various electronic applications, providing isolation and signal transmission between different components. Industries including telecommunications, industrial automation, and consumer electronics use these components for their reliability and efficiency. The segment experiences growth driven by increasing demand for enhanced signal integrity and safety in electronic devices. This sub-segment exhibits distinct characteristics compared to others, including Image Sensors and Laser Diodes, which focus on imaging and light emission. While the latter segments see rapid advancements driven by technological innovation, Optocouplers and Optical Solid-State Relays often experience stable demand, reflecting a slower growth trajectory. The market's shift towards automation and smart technologies further underpins the persistent relevance of this segment.
The Silicon segment is valued at USD 37.7 billion in 2026 and is projected to reach USD 59.9 billion by 2033, at a CAGR of 6.9% during the forecast period. This semiconductor material is widely used in applications including consumer electronics and telecommunications, serving industries that heavily rely on efficient light emission and detection. The segment experiences growth due to increasing demand for advanced imaging systems and high-performance lighting solutions. Compared to other active semiconductor materials, including gallium nitride and indium gallium nitride, silicon exhibits a slower growth rate, reflecting a CAGR of 6.9% versus 5.9% for its counterpart. The lower price point of silicon, alongside established manufacturing processes, positions it advantageously, ensuring its relevance in the evolving landscape of the opto semiconductors market.
Gallium Nitride and Indium Gallium Nitride segment is estimated to reach USD 16.8 billion by 2033, at a CAGR of 5.9% during the forecast period. These materials are critical for high-efficiency power electronics and optoelectronic devices, serving markets that include telecommunications, consumer electronics, and automotive. Demand for Gallium Nitride and Indium Gallium Nitride is driven by the increasing need for compact, efficient components capable of handling high power levels. This segment presents higher growth potential compared to others within the Active Semiconductor Material category, with Silicon projected to grow at a CAGR of 6.9%. The unique properties of Gallium Nitride and Indium Gallium Nitride allow for advancements in applications including optical data transmission and imaging systems, which further distinguish this segment from others in the market.
Gallium Arsenide and Aluminum Gallium Arsenide segment is expected to reach USD 13.7 billion by 2033. This segment finds application in high-frequency and high-efficiency devices, primarily used in telecommunications, military, and space applications. The demand for Gallium Arsenide and Aluminum Gallium Arsenide is driven by the increasing adoption of wireless communication technologies that require efficient power transmission and reduced signal degradation. Compared to other semiconductor materials, this segment exhibits faster growth due to its superior electronic properties and ability to operate at higher frequencies. The projected growth rate highlights its significance, particularly in sectors focused on advanced communication systems, where performance and reliability are critical. The market continues to explore new applications for these materials, broadening their utility beyond traditional sectors.
Indium Phosphide segment is projected to grow at a CAGR of 14.9% during the forecast period. This segment finds applications primarily in high-speed telecommunications, fiber optics, and advanced sensors. The demand for Indium Phosphide is driven by the increasing need for faster data transmission and the expansion of communication networks. Compared to other active semiconductor materials, Indium Phosphide typically commands higher prices due to its specialized manufacturing processes and superior performance characteristics. This segment attracts buyers from telecommunications and data centers seeking enhanced efficiency and reliability in their systems. With unique properties including a direct bandgap and high electron mobility, Indium Phosphide serves applications requiring robust performance, distinguishing it from other semiconductor materials that do not provide similar advantages.
Aluminum Gallium Indium Phosphide is a critical active semiconductor material, primarily applied in high-frequency and optoelectronic applications. This material is commonly found in telecommunications, laser technology, and high-efficiency solar cells, appealing to industries that prioritize performance and efficiency. Demand for Aluminum Gallium Indium Phosphide is driven by the increasing need for advanced optical systems and communication technologies. Contrasting with other semiconductor materials, this segment typically commands a higher price point due to its specialized applications and materials processing requirements. The segment's growth outlook benefits from innovations in photonics and the rising adoption of LED technologies, positioning it distinctively against other materials like Silicon, which supports more general applications. The market reflects pronounced interest in enhancing energy efficiency and performance, prompting manufacturers to invest in technologies that leverage the unique properties of Aluminum Gallium Indium Phosphide.
This sub-segment includes materials including germanium and silicon carbide, which play essential roles in various opto semiconductor applications. These materials find usage in high-performance devices, particularly in optics and photonics. Industries including telecommunications, aerospace, and defense benefit from their unique properties, including high thermal conductivity and efficiency in light emission. Demand for high-precision components in these sectors drives the segment, with advancements in technology improving material performance. Compared to other segments, the growth trajectory for germanium and silicon carbide is slower, influenced by the more established presence of silicon and gallium-based materials. However, specialized applications and increasing requirements for high-performance products support continued interest in this sub-segment. The opto semiconductors market reflects a diverse material landscape, where each type serves distinct functional requirements.
The segment finds application in diverse fields, including automotive, healthcare, and industrial automation. Key drivers of growth include advancements in image processing technologies and increasing adoption of automated systems across industries. This segment exhibits a higher growth rate due to rising demand for enhanced imaging capabilities and automation solutions. The competitive landscape features various players focusing on innovation and product differentiation, reflecting the segment's importance in driving performance and efficiency in the market.
Lighting and Illumination segment is estimated to reach USD 14.6 billion by 2033, at a CAGR of 5.2% during the forecast period. This segment primarily serves the needs of various industries including residential, commercial, and automotive sectors. Increasing demand for energy-efficient lighting solutions drives growth, particularly due to stricter energy regulations. Compared to other segments like Imaging and Machine Vision, which is projected to grow at a CAGR of 6.5%, the Lighting and Illumination segment experiences moderate growth rates due to its established market presence and slower technological advancements. The ongoing transition toward LED technology further influences market dynamics, encouraging manufacturers to innovate while adapting to consumer preferences for sustainability and cost-effectiveness. This focus on efficiency aligns with broader trends in the opto semiconductors market, shaping future investment and development strategies.
This segment primarily serves consumer electronics, automotive displays, and commercial lighting applications, providing crucial illumination and visual enhancement. Demand for high-quality displays and energy-efficient backlighting solutions drives growth in this segment, particularly in smartphones, televisions, and automotive dashboards. The CAGR stands at 5.2%, reflecting slower growth compared to other segments in the application category. In contrast to Imaging and Machine Vision, which is projected to grow at a higher rate of 6.5%, Displays and Backlighting faces challenges related to cost management and technological advancements. Continued innovation in LED technology influences pricing dynamics, impacting adoption rates across various end-use industries. The market experiences increasing competition from alternatives, including OLED and microLED technologies, which present challenges and opportunities for manufacturers seeking to differentiate their offerings in a changing environment.
Optical Data Transmission segment is projected to grow at a CAGR of 15.5% during the forecast period. This segment focuses on high-speed data transfer technologies in telecommunications, data centers, and networking applications. Key players in these industries rely on optical data transmission for enhanced bandwidth and improved signal integrity. Demand for faster communication protocols significantly drives this segment, with continuous advancements in fiber optic technology fueling growth. Unlike other segments, optical data transmission experiences accelerated growth due to the increasing reliance on high-speed internet and cloud computing services, which require robust data transmission capabilities. The segment stands out due to its rapid expansion compared to traditional data transmission methods, ensuring that the market adapts to evolving digital communication needs.
Non-Imaging Sensing and Ranging involves technologies used for detecting and measuring distances without forming an image. Applications include industrial automation, robotics, and automotive safety systems, where precise distance measurement is critical. Demand for this segment is driven by advancements in automation and the growing importance of safety features in vehicles. Compared to other application segments, this sub-segment experiences different growth dynamics due to its specialized nature and technological requirements. The market includes a variety of buyers, including manufacturers of sensor systems and automotive companies, which invest in these technologies to enhance product functionality and ensure compliance with safety regulations. The focus on improving accuracy and reducing costs influences the development and adoption of Non-Imaging Sensing and Ranging technologies, shaping their competitive positioning in the broader opto semiconductors market.
Galvanic Isolation ensures reliable performance in sensitive applications by protecting various electronic components from voltage spikes and noise. This technology primarily finds usage in industrial automation, automotive systems, and telecommunications, where safe and efficient signal transmission is critical. Increased adoption of electrification and automation in industries drives demand for Galvanic Isolation solutions, because these technologies enhance safety and reliability in critical systems. Compared to other applications within the opto semiconductors market, Galvanic Isolation often commands a higher price due to its specialized function and the advanced materials required for effective isolation. This sub-segment stands out with its unique demand drivers, reflecting the evolving needs of end users who prioritize safety and system integrity in their operations.
This sub-segment includes applications related to optical pumping and direct laser processing, which contribute to advancements in various fields including telecommunications and manufacturing. Optical pumping serves critical functions in enhancing laser performance, while direct laser processing enables precise material manipulation. Industries including healthcare and defense apply these technologies for high-precision tasks. Demand for more efficient and compact laser systems drives growth in this sub-segment, pushing technological advancements and improved product offerings. Compared to other applications, this sub-segment focuses on specialized applications with unique requirements, resulting in distinct market dynamics. Overall, growing interest in innovative laser solutions for specific applications supports the expansion of the opto semiconductor market.
Consumer Electronics segment is valued at USD 26.8 billion in 2026 and is projected to reach USD 38.3 billion by 2033, at a CAGR of 5.2% during the forecast period. This segment primarily serves manufacturers of devices including smartphones, tablets, and home entertainment systems. The increasing consumer preference for advanced features and enhanced capabilities in electronics drives demand for opto semiconductors. Unlike the Imaging and Machine Vision segment, which has a higher CAGR of 6.5%, the Consumer Electronics segment experiences steadier growth due to market saturation and price sensitivity. Ongoing advancements in display technologies, along with rising adoption of smart home devices, significantly support growth in this area. With several manufacturers focused on integrating innovative technologies into consumer products, the market observes continuous evolution and adaptation to meet consumer expectations.
The Automotive and Transportation segment is estimated to reach USD 18.9 billion by 2033, at a CAGR of 8.7% during the forecast period. This segment focuses on applications in vehicle LED lighting, advanced driver assistance systems, and sensor technology, primarily adopted by automotive manufacturers and suppliers. The growing emphasis on vehicle safety and the introduction of electric and autonomous vehicles drive demand for advanced opto semiconductor technologies. Unlike other segments, the Automotive and Transportation segment experiences faster growth due to increased investments in smart vehicle technologies. Innovations in laser diodes and image sensors contribute significantly to this acceleration, enabling features including adaptive lighting and enhanced vehicle navigation systems. The adoption of stricter safety regulations and increasing consumer demand for innovative and intelligent transportation solutions reinforce the segment's importance in the broader opto semiconductors market.
The Telecommunications and Data Centers segment is expected to reach USD 19.9 billion by 2033. This segment focuses on the integration of opto semiconductor technologies in networking infrastructure, cloud computing services, and data storage solutions. Key players in this segment include telecommunications service providers and data center operators, who rely on these technologies for high-speed data transmission and efficient operations. Growth is driven by the increasing demand for bandwidth and the expansion of 5G networks, which require advanced opto semiconductor components. This segment exhibits a higher growth rate compared to others, with a CAGR of 8.7%, reflecting the urgency to enhance network capacity and performance. In contrast to segments including Consumer Electronics, which experience moderate growth, Telecommunications and Data Centers experience rapid advancements due to technological innovations and evolving consumer expectations within the market.
Industrial and Manufacturing segment is projected to grow at a CAGR of 7% during the forecast period. This segment encompasses a range of applications, including automation, process control, and quality assurance in manufacturing processes. Key users include manufacturers of industrial equipment, machinery, and robotics, who apply opto semiconductors for precision and efficiency enhancements. Demand is driven by the increasing automation of manufacturing processes and the integration of smart technologies, which require advanced opto semiconductor solutions. Compared to other segments, this segment features moderate growth rates, while it faces specific challenges including high initial investment costs and varying regulatory requirements that affect adoption. The market exhibits robust potential, benefiting from continued investments in infrastructure and the push toward Industry 4.0 initiatives.
Building and Lighting encompasses applications designed to enhance both residential and commercial spaces through effective illumination and design. Key users of this segment include architects, builders, and lighting designers who integrate these solutions into various projects. The demand for energy-efficient lighting solutions significantly influences this segment, reflecting a broader trend toward sustainability and reduced energy consumption. This segment differs from others in its group, with a unique emphasis on aesthetic design alongside functionality, appealing to a different customer base focused on long-term operational savings rather than immediate cost. The adoption of smart lighting technologies creates additional opportunities for innovation, setting this segment apart from applications including Imaging and Machine Vision, which prioritize performance metrics over design considerations. The Opto Semiconductors market continues to evolve, with advancements supporting the growing demand for intelligent and adaptable lighting solutions.
Healthcare and Life Sciences encompasses technologies designed for medical applications, including diagnostics and therapeutic devices. This segment attracts interest from healthcare providers, medical device manufacturers, and research institutions relying on advanced imaging technologies and sensors for patient care and research. Demand for enhanced diagnostic capabilities drives investments in opto semiconductor solutions. The segment experiences growth due to ongoing advancements in medical technology, particularly in areas like imaging and machine vision. Pricing pressures from emerging technologies result in differing buyer dynamics compared to other segments, with healthcare applications requiring compliance with stringent regulations and higher reliability standards. Unlike segments including Consumer Electronics, Healthcare and Life Sciences operates within a more specialized market framework, focusing on high-performance solutions tailored to medical needs.
Security and Surveillance encompasses applications essential for monitoring and protecting premises, assets, and people. This segment serves various buyers, including government agencies, private security firms, and businesses focused on enhancing safety through advanced surveillance technologies. Increased security threats and a growing emphasis on public safety drive the demand for high-quality imaging solutions. Technology advancements in image sensors and laser diodes contribute significantly to enhancing CCTV and other surveillance systems, enabling clearer images and improved performance in low-light conditions. Compared to other segments, this area experiences distinct growth dynamics, largely driven by rising investments in smart city initiatives and infrastructure development. The strong demand for reliable and efficient security solutions positions this segment uniquely within the broader context of the Opto Semiconductors market.
This sub-segment includes applications related to research institutions and agricultural equipment, which employ opto semiconductors for various advanced technologies. Research institutes leverage these semiconductors for imaging and sensing applications, while agricultural equipment enhances automation and precision in farming practices. Demand for these technologies is driven by the increasing push for automation in agriculture and the necessity for improved research methodologies in scientific studies. The segment features distinct characteristics compared to others, reflecting a blend of specialized applications and potentially lower volume sales. This differentiation drives unique pricing strategies and reflects the varied buyer landscape, which includes both government-funded research initiatives and private agricultural enterprises. Growth in the segment aligns with broader trends in technological advancement, emphasizing the need for innovative solutions in research and agricultural practices, contributing to the overall growth of the opto semiconductors market.
Based on geography, the Global Opto Semiconductors market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Strong demand in North America stems from the rapid adoption of advanced imaging technologies, particularly in the consumer electronics and automotive sectors. The presence of major manufacturers in the United States, Canada, and Mexico contributes significantly to the market dynamics. Image Sensors represent a key segment, projected to achieve substantial growth through 2033. North America is projected to reach USD 26.4 billion by the end of 2033. A robust infrastructure supporting telecommunications and data centers enhances opportunities for growth within the opto semiconductors market. This environment encourages innovation and investment, driving advancements in applications including optical data transmission and machine vision.
Germany, France, the UK, Italy, and Spain drive significant demand within the market, focusing on industries including consumer electronics and telecommunications. The increase in electronic device manufacturing, coupled with advancements in imaging technologies, increases the need for high-quality opto semiconductors. Regulatory frameworks promoting energy efficiency and sustainability contribute to market growth, particularly in the lighting sector. Overall, the European market holds a share of 16.6% in 2025, reflecting robust demand for both innovative and traditional opto semiconductor applications. The market's growth is expected to strengthen due to ongoing investments in research and development, ensuring competitiveness in global supply chains.
Strong demand for opto semiconductors stems from the flourishing consumer electronics sector throughout Asia-Pacific. China, Japan, and India represent key markets, with initiatives aimed at advancing technology and improving manufacturing capabilities driving growth. Automation in industrial processes enhances the adoption of opto semiconductor applications. Investment in infrastructure, including smart city initiatives, significantly increases demand for lighting and illumination technologies. The region holds a share of 54.3% of the global market in 2025. Companies within the opto semiconductors market are responding to the rising requirements for advanced imaging solutions and energy-efficient lighting.
The opto semiconductors market in South America demonstrates growth driven primarily by the consumer electronics and automotive sectors. Brazil and Argentina lead demand due to increasing investments in technology and infrastructure. The region's relatively low penetration of advanced imaging and lighting solutions presents opportunities for expansion. A focus on enhancing connectivity and modernization of transportation systems further supports this demand. South America, representing 3.3% of the global market share in 2025, is expected to experience increased adoption of opto semiconductors, particularly in applications related to imaging and illumination. The market's growth trajectory aligns with regional efforts toward technological advancement and modernization.
Saudi Arabia and the UAE emerge as key players in the opto semiconductors market, driven by increasing investments in smart city initiatives and advanced technology infrastructure. South Africa experiences a growing demand for opto semiconductors within its expanding telecommunications sector, which enhances connectivity and digital transformation efforts. With a share of 2.5% of the global market in 2025, the region reflects the expanding role of opto semiconductors in various applications, including imaging and lighting. Market growth in the Middle East and Africa supports diversification efforts within the technology landscape, promoting innovation and adoption across multiple industries. Emerging trends highlight the significance of regional infrastructure development in shaping future demand for opto semiconductors.
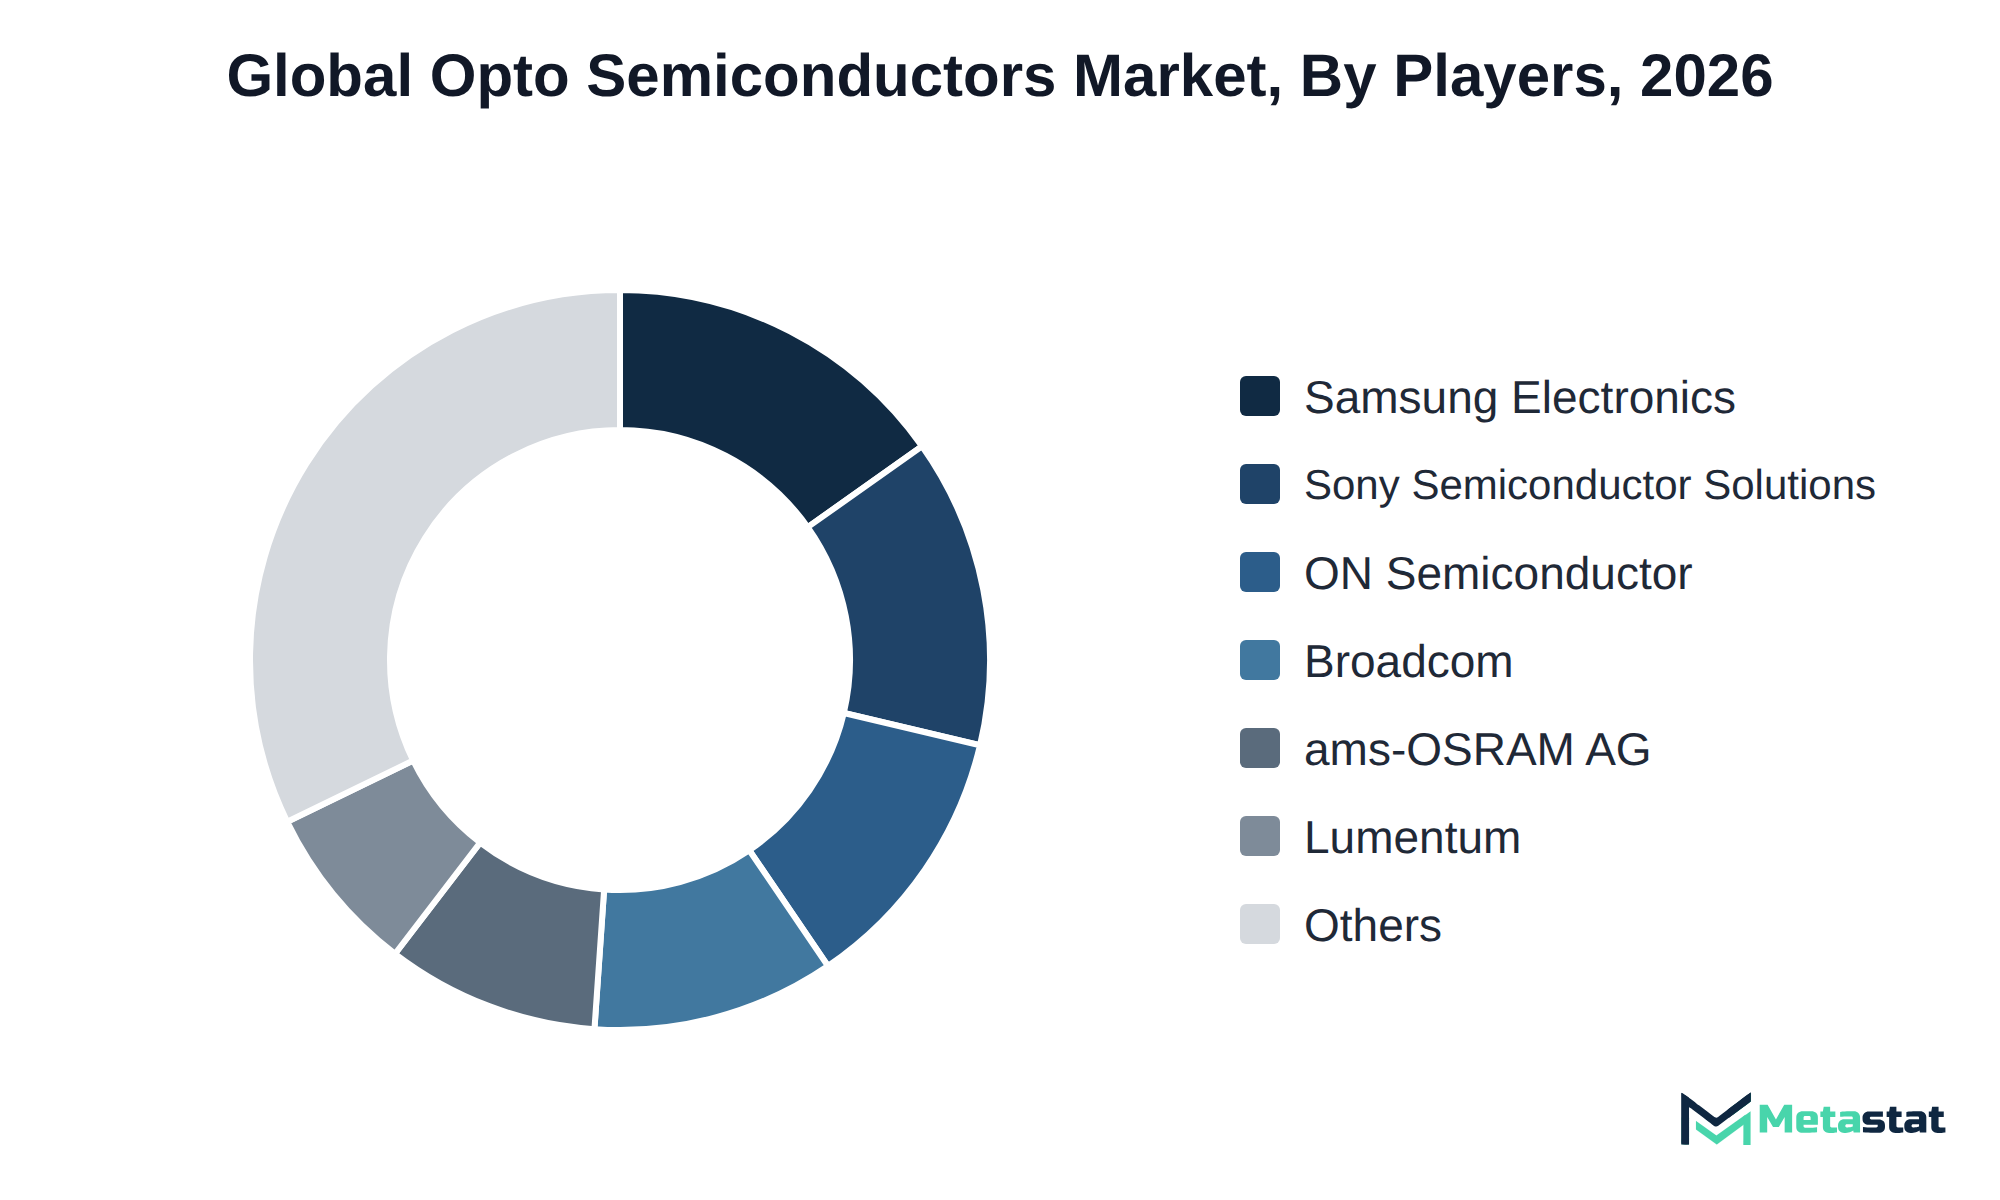
Competition in the Opto Semiconductors market is shaped by the strategies of key players. Companies emphasize technological advancement, product quality, and tailored solutions to meet specific buyer requirements, including price, certification, customization, service, and ecosystem integration.
For instance, Sony Semiconductor Solutions Corporation focuses on delivering high-performance image sensors, catering primarily to consumer electronics and automotive applications. Samsung Electronics Co., Ltd. prioritizes innovations in display technologies and laser diodes, enhancing visual experiences across multiple end-use industries. In contrast, Nichia Corporation specializes in light-emitting diodes, targeting sectors that demand energy-efficient lighting solutions.
This competitive environment drives ongoing advancements and differentiation. Companies invest in research and development to enhance their product portfolios and maintain relevance in the evolving market.
Growth in the Opto Semiconductors market relies on advancements in several key areas. First, the increasing demand for image sensors, particularly in consumer electronics and automotive applications, will drive revenue. Heightened investments in imaging technologies will lead to significant expansion in this segment. Second, the transition to advanced active semiconductor materials, especially silicon, will support growth, driven by their application in both industrial and consumer sectors. Lastly, enhancements in optical data transmission capabilities will facilitate innovation in telecommunications and data centers, further supporting the market. Despite these positive developments, risks remain that could impede growth. Supply chain disruptions and fluctuations in semiconductor material prices pose significant challenges, potentially delaying market expansion. Reaching the projected market size depends on managing these risks while capturing emerging opportunities across applications. Addressing these challenges effectively will determine the trajectory of the Opto Semiconductors market through 2033.
By Product Type: Light-Emitting Diodes, Image Sensors, Laser Diodes, Photodiodes and Phototransistors, Optocouplers and Optical Solid-State Relays
By Active Semiconductor Material: Silicon, Gallium Nitride and Indium Gallium Nitride, Gallium Arsenide and Aluminum Gallium Arsenide, Indium Phosphide, Aluminum Gallium Indium Phosphide, Others (Germanium, Silicon Carbide)
By Application: Imaging and Machine Vision, Lighting and Illumination, Displays and Backlighting, Optical Data Transmission, Non-Imaging Sensing and Ranging, Galvanic Isolation, Others (Optical Pumping, Direct Laser Processing)
By End-Use Industry: Consumer Electronics, Automotive and Transportation, Telecommunications and Data Centers, Industrial and Manufacturing, Building and Lighting, Healthcare and Life Sciences, Security and Surveillance, Others (Research Institutes, Agricultural Equipment)
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Opto Semiconductors market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 7.4% from 2026 to 2033 |
|
Revenue Unit |
USD billion |
|
Segmentation |
By Product Type, Active Semiconductor Material, Application, End-Use Industry, and Region |
|
By Region |
North America (By Product Type, Active Semiconductor Material, Application, End-Use Industry, and Country)
|
|
Europe (By Product Type, Active Semiconductor Material, Application, End-Use Industry, and Country)
|
|
|
Asia Pacific (By Product Type, Active Semiconductor Material, Application, End-Use Industry, and Country)
|
|
|
South America (By Product Type, Active Semiconductor Material, Application, End-Use Industry, and Country)
|
|
|
Middle East and Africa (By Product Type, Active Semiconductor Material, Application, End-Use Industry, and Country)
|
Find answers to common questions about this report
The Opto Semiconductors market size was valued at USD 61 billion in 2025.
The market is projected to grow at a CAGR of 7.4% during the forecast period from 2026 to 2033.
The North America Opto Semiconductors market size is estimated to reach USD 26.4 billion by 2033.
Image Sensors lead the Opto Semiconductors market with a projected value of USD 54 billion by 2033, based on revenue figures. This segment outpaces others in growth potential and market share.
Growing demand for image sensors from sectors like automotive and machine vision drives significant investment in opto semiconductor solutions. Innovations in laser diode technology enhance efficiency and performance, creating new opportunities within the market.
Asia Pacific holds the dominant share of the Opto Semiconductors market, accounting for 54.3% of the total market. This region's significant share reflects its strong manufacturing capabilities and demand across various applications.
Increasing costs for opto semiconductor components hinder purchasing decisions across various industries. Rising prices for active materials, including Silicon and Gallium Nitride, challenge profitability and lead to cautious investment approaches among buyers.
Increasing demand for imaging and machine vision applications drives adoption in the opto semiconductors industry. This trend results from advancements in automation and artificial intelligence, enhancing the need for high-performance imaging solutions across sectors including healthcare, automotive, and security.
The Opto Semiconductors market is estimated to reach a valuation of USD 108.4 billion by 2033.
Key players operating in the Opto Semiconductors market include Sony Semiconductor Solutions Corporation, Samsung Electronics Co., Ltd., OMNIVISION Technologies, Inc. (Will Semiconductor), ams-OSRAM AG, Nichia Corporation, Broadcom Inc., and ON Semiconductor Corporation.
The analysts below cover Electronics and Semiconductor research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.
PRINCIPAL CONSULTANT - QUALITY SYSTEMS & COMPLIANCE
Electronics and Semiconductor · Machinery & Equipment · Professional Services
Omkar Phadtare is an Industry Consultant at MetaStat Insight, specializing in quality systems, regulatory compliance, and standards benchmarking to drive data-driven market intelligence and strategic industry research.
ENERGY & INFRASTRUCTURE INDUSTRY CONSULTANT
Automotive and Transportation · Electronics and Semiconductor · Energy and Power · Machinery & Equipment
Saurabh Vasant Ganvir consults for Energy & Infrastructure Industry at MetaStat Insight, specializing in renewable energy, solar EPC, and electric vehicle (EV) infrastructure markets.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Scaling antibody-drug conjugate manufacturing hinges on contract manufacturing availability for high-potency active ingredients. The MetaStat Insight analysis looked closely at global cleanroom slot constraints, bioconjugation batch failure rates, and supply chain redundancies between the US, Europe, and India. The supplier capability matrix proved genuinely useful for our team when mapping secondary source options across our clinical pipeline.
Floating offshore wind feasibility relies heavily on specialized installation vessel availability and port crane limits, which most broad renewable energy forecasts ignore. The report delivered a thorough analysis of dry dock capacity, mooring chain supply constraints, and raw material pricing trends for deepwater anchor installations. It served as a solid independent sanity check for our offshore project capital expenditure assumptions.
Assessing commercial microgrid software adoption requires looking past top-level installation numbers and examining utility interconnection queues. The research provided verifiable data on average permitting timelines, tariff structures, and battery storage integration costs across regional utility territories. That grounded perspective was valuable for our team when building five-year demand projections for industrial microgrid controllers.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950