
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Open-Source Database Software Market Size, Share, By Database Type (Relational Databases, Key-Value Databases, Document Databases, Wide-Column Databases, Time-Series Databases, Graph Databases, Vector Databases and Others), By Delivery Model (Vendor-Managed Database Services and Customer-Managed Software Subscriptions and Licenses), By Organization Size (Large Enterprises and Small and Medium-Sized Enterprises), By End-Use Industry (IT and Telecommunications, Banking, Financial Services and Insurance, Retail and E-Commerce, Healthcare and Life Sciences, Manufacturing, Government and Public Sector, Media and Entertainment and Others), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-2412
Published
November, 2026
Pages
274 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
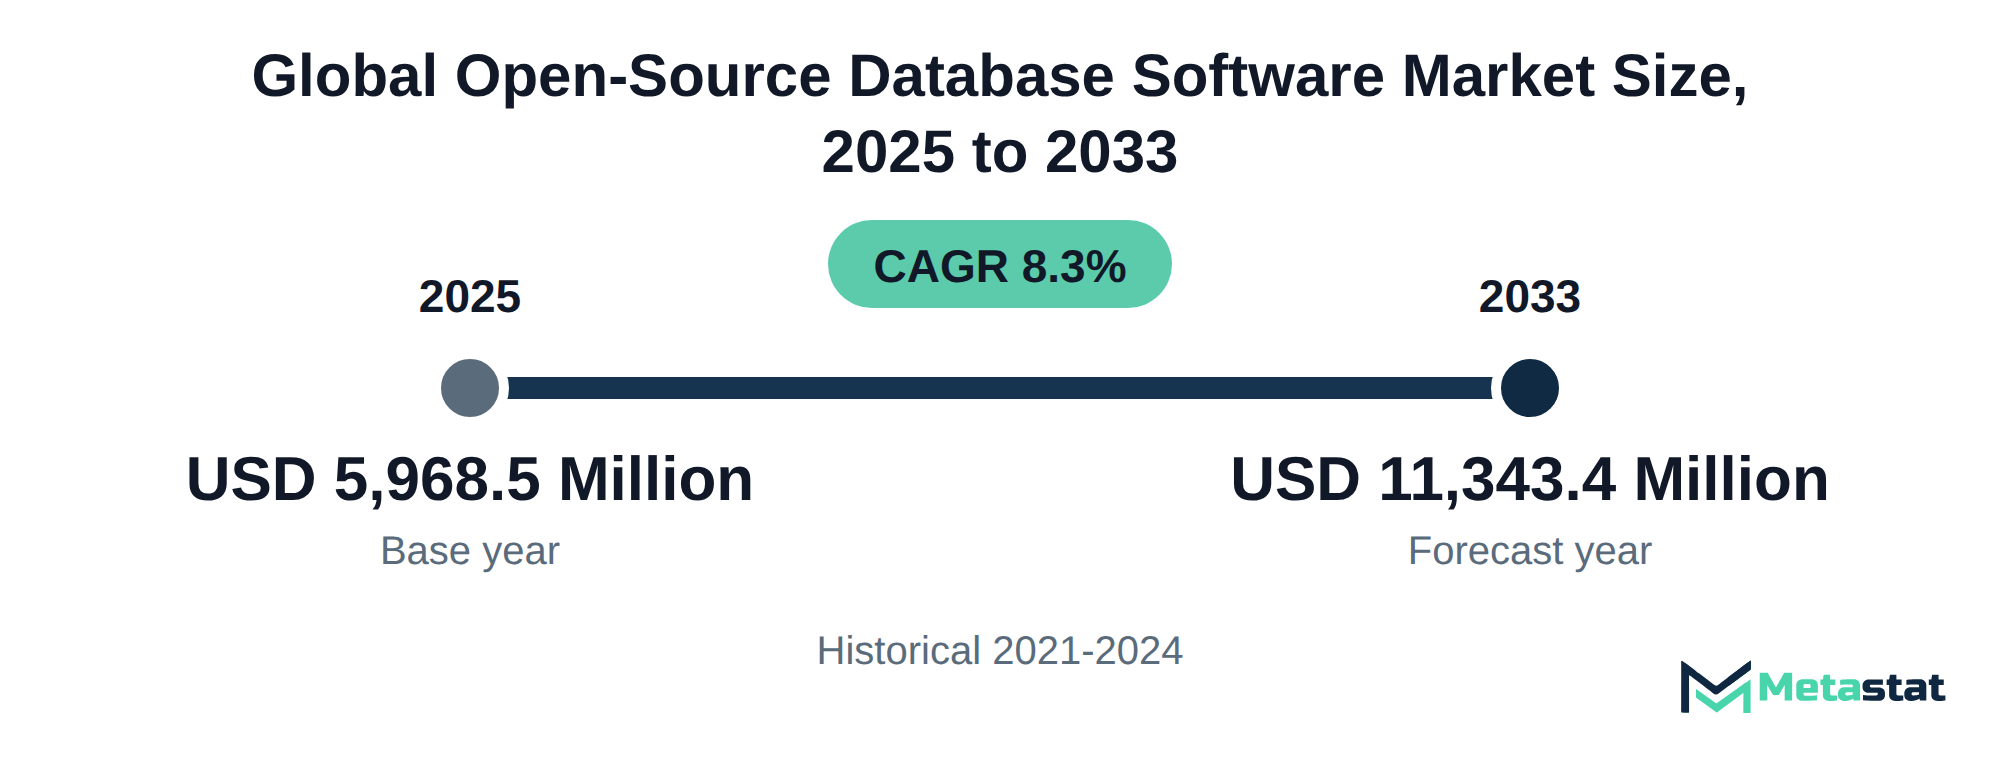
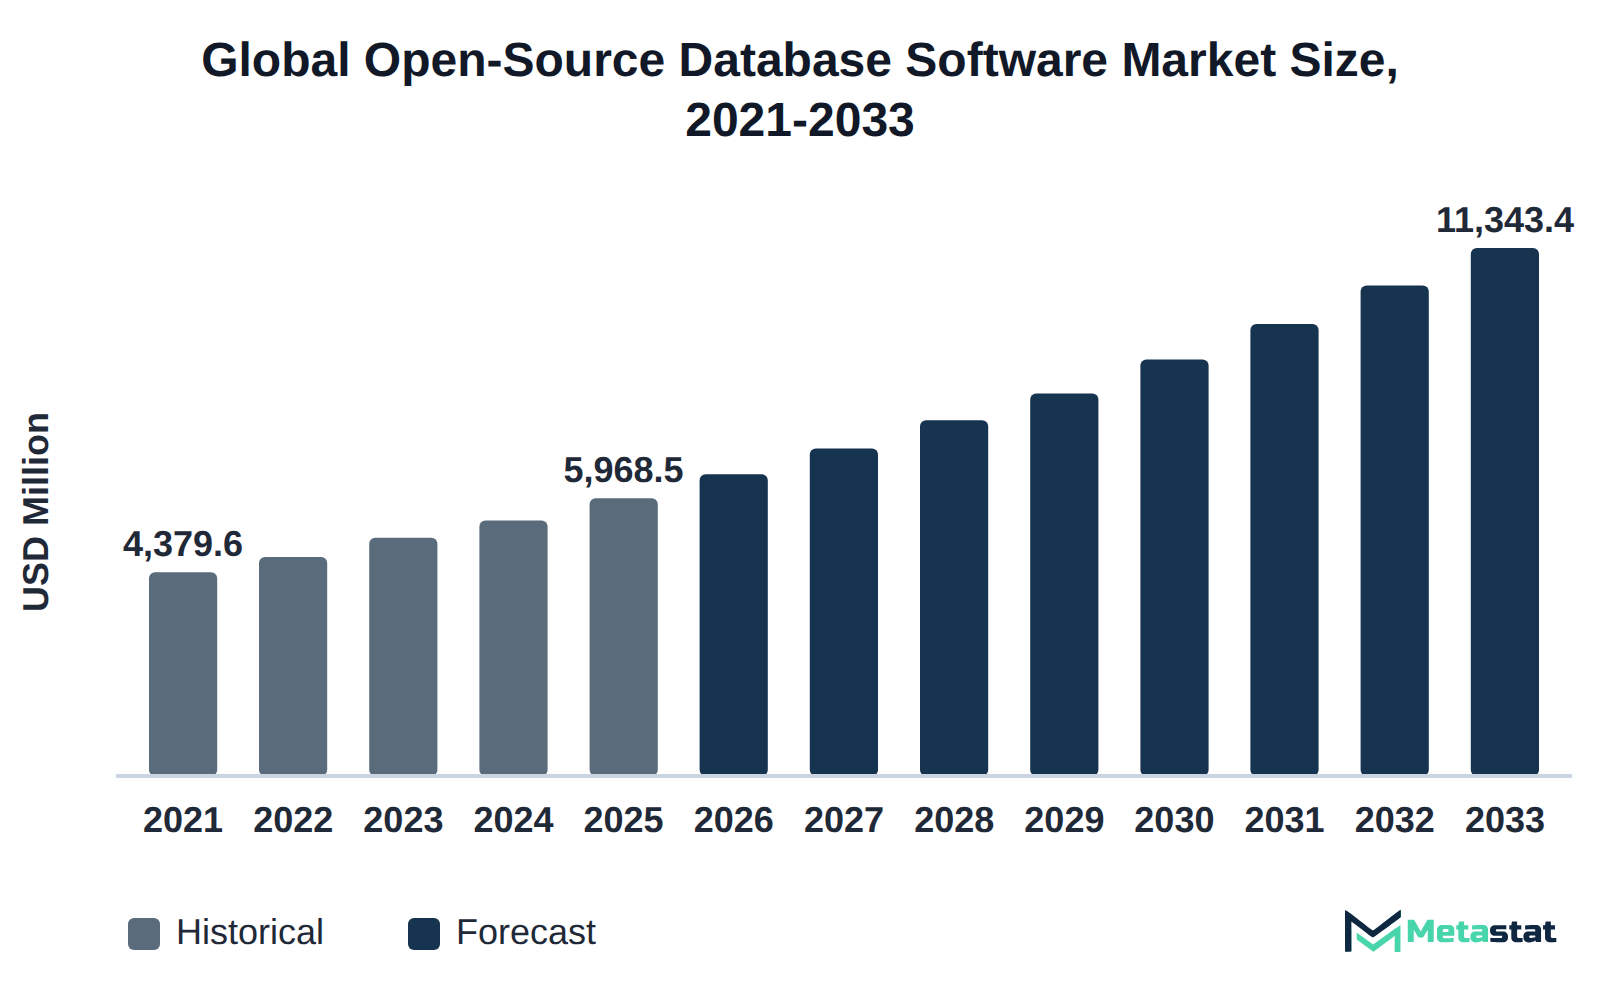
Market Valuation: Valued at $5,968.5 Million in 2025, projected to reach $11,343.4 Million by 2033 at a 8.3% CAGR.
Dominant Segment: Relational databases lead the market, projected to reach USD 7,534.3 million by 2033, driven by the increasing demand for structured data management and robust querying capabilities.
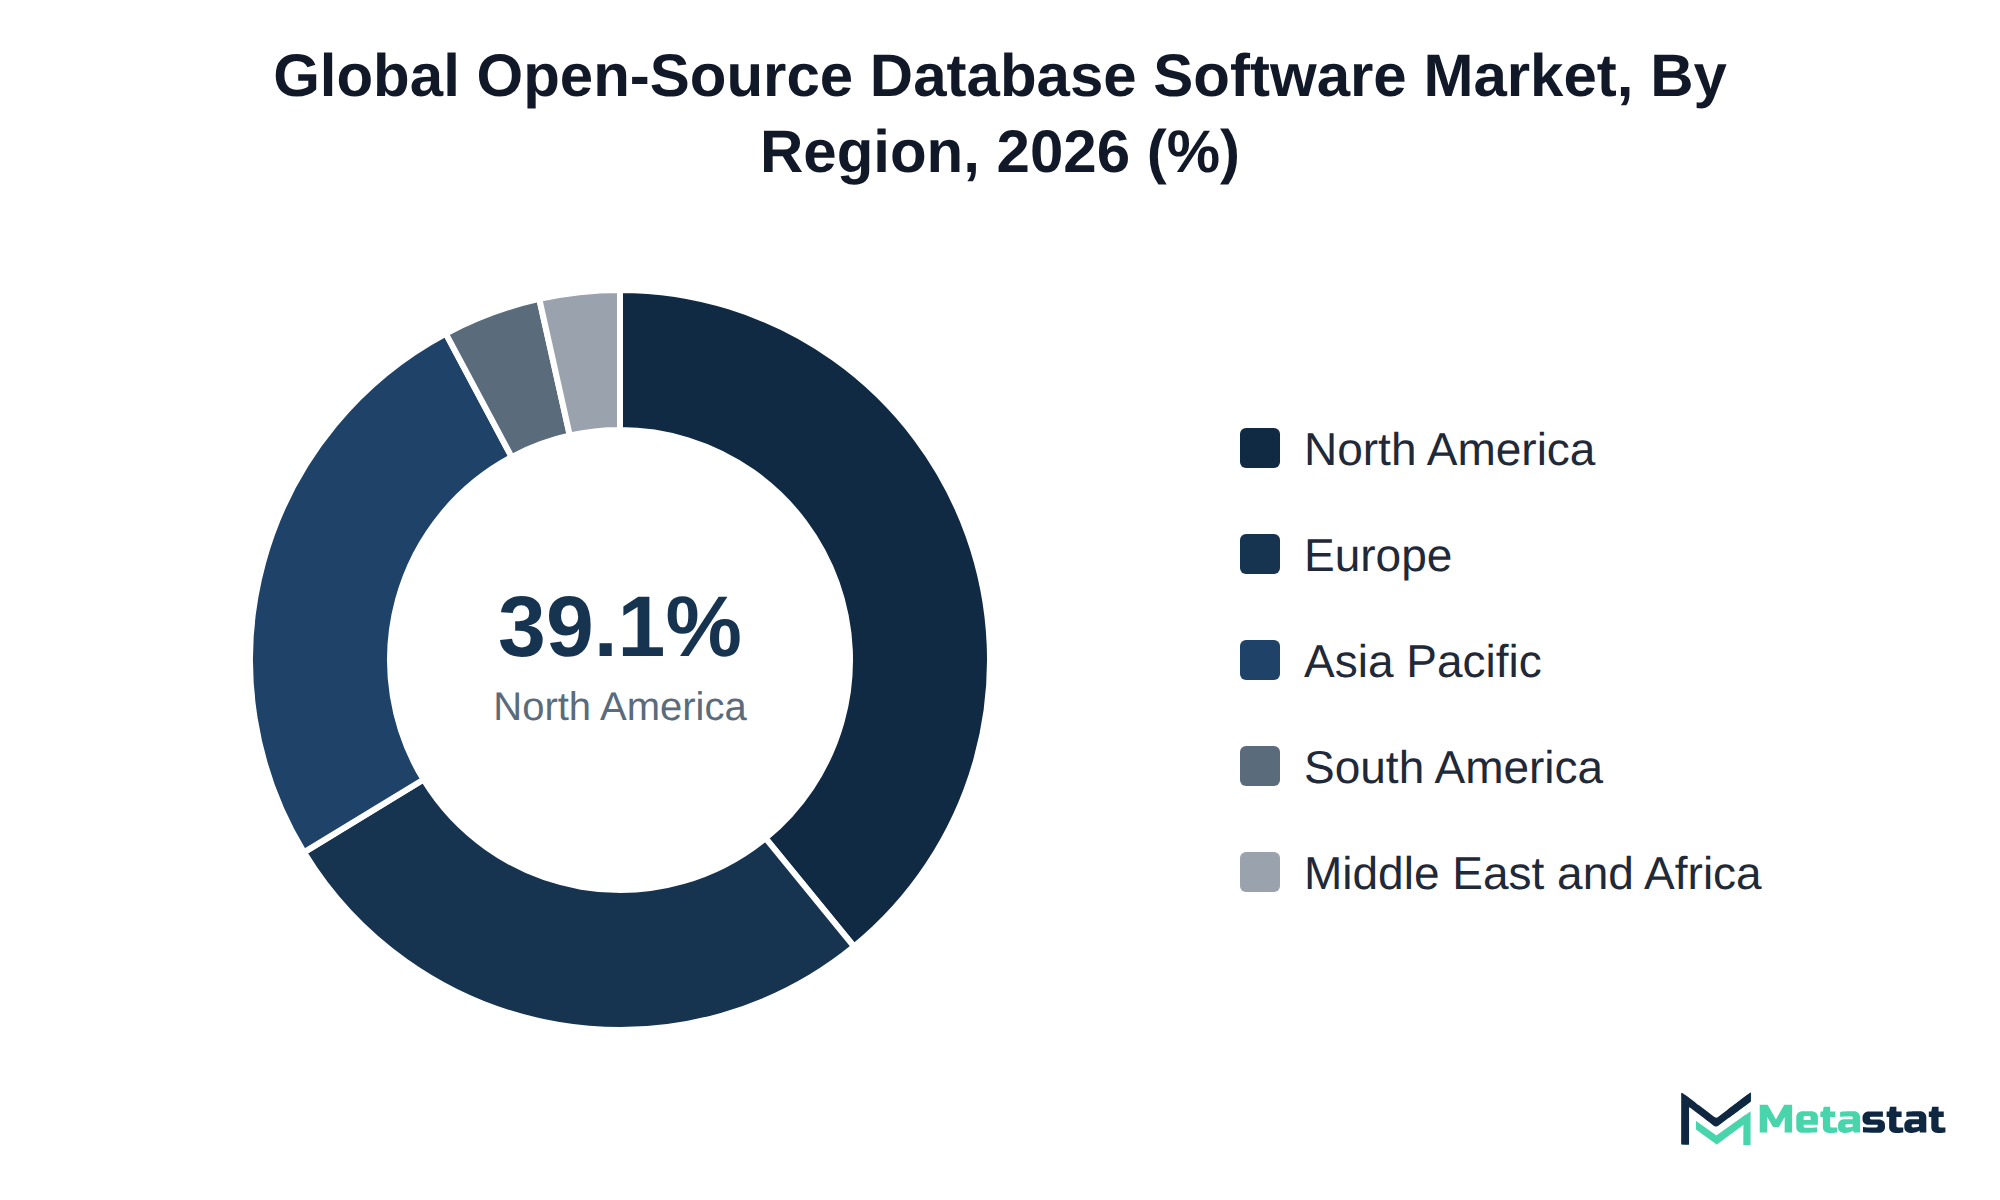
Geographic Lead: North America is the leading region, holding 39.1% of the market in 2025, with the US expected to maintain its dominance due to advanced technological infrastructure and significant investments in digital transformation.
What's Inside: The report provides comprehensive competitive coverage, detailed analyses of market dynamics, and forecasts extending to 2033, ensuring readers gain insights into current trends and future opportunities.
Increased adoption among small enterpris: The market is experiencing significant growth among small and medium-sized enterprises (SMEs), projected to reach USD 3,991.7 million by 2033, as these businesses seek cost-effective and flexible database solutions.
Increased focus on vendor-managed servic: The rise in demand for vendor-managed database services reflects a shift towards outsourcing database management, with a projected value of USD 4,213.9 million in 2026, growing to USD 8,243.2 million by 2033.
Choose Your License
Global Open-Source Database Software Market
The global Open-Source Database Software market was valued at USD 5,968.5 million in 2025 and is projected to reach USD 11,343.4 million by 2033, growing at a CAGR of 8.3% over the forecast period.
The Open-Source Database Software market covers software that allows users to create and manage databases without proprietary licensing restrictions. Buyers invest in these solutions to gain flexibility, lower costs, and benefit from community-driven innovation. Key sectors driving expenditure include IT, telecommunications, and financial services, where the demand for scalable and customizable database solutions is significant.
Growth in the market is largely attributed to the increasing adoption of cloud-based services and the need for data-driven decision making. Relational databases represent the segment with the highest value, projected to reach USD 7,534.3 million by 2033. North America holds 39.1% of the market in 2025, with the US leading in 2026. This region benefits from advanced technological infrastructure and high investment levels in digital transformation initiatives.
Enhanced data analytics capabilities significantly contribute to the market's expansion. Organizations prioritize open-source solutions to address diverse data management needs and improve operational efficiency. Major technology firms and emerging companies compete for a share of the growing demand for innovative database solutions.
The Open-Source Database Software market includes various types of database management systems that operate without proprietary constraints, appealing to businesses seeking cost-effective solutions. Organizations invest in these systems to strengthen data management and run operations more efficiently. The demand for flexibility and scalability drives buyers to adopt open-source software, enabling them to tailor databases to specific needs without incurring high licensing fees.
Growth in the market is propelled by the increasing adoption of relational databases, which represent the largest segment in terms of value. The rising need for data-driven decision-making across various industries, including IT and telecommunications, fuels the expansion of open-source database solutions, as businesses recognize the importance of leveraging data for competitive advantage.
Investments in cloud services further support market growth, as companies transition to more agile and scalable infrastructure. The open-source nature of these databases allows organizations to adapt quickly to changing demands while minimizing costs. A continued corporate focus on innovation and efficiency positions the market for sustained growth in the coming years.
The rise of Database as a Service (DBaaS) significantly influences the Open-Source Database Software market, particularly through the increasing adoption of managed PostgreSQL solutions. This trend reflects a growing preference among organizations for cloud-based infrastructure, driven by the need for scalability, ease of management, and reduced operational complexity. Managed PostgreSQL services allow businesses to use the capabilities of PostgreSQL without maintaining complex database systems in-house.
In 2026, the value of vendor-managed database services, which includes offerings like managed PostgreSQL, is expected to reach USD 4,213.9 million, with a projected growth to USD 8,243.2 million by 2033, representing a compound annual growth rate (CAGR) of 10.1%. This expansion highlights the market's shift towards these services, marking a significant transformation in how organizations approach database management.
The move to managed PostgreSQL improves operational efficiency and allows firms to focus on their core competencies, which optimizes resource allocation. With the robust capabilities of PostgreSQL combined with the flexibility of DBaaS, organizations experience improved performance and reduced costs. This shift drives greater innovation and competitiveness among firms that adopt these technologies.
The pricing models for Open-Source Database Software involve various structures, reflecting the diverse needs of buyers across different sectors. This model allows organizations to outsource database management while benefiting from vendor expertise and ongoing support.
Customer-managed software subscriptions and licenses offer another purchasing avenue, with projections indicating a value of USD 2,031.6 million by 2033, reflecting a CAGR of 4.7%. This model grants organizations greater control over their database environments, appealing to businesses seeking customization and flexibility. Standalone support and maintenance services cater to those who prefer to manage their database solutions independently, with an anticipated value of USD 1,068.5 million by 2033.
These purchasing strategies have a significant influence on buyer decisions in the market. Organizations optimize costs and enhance operational efficiency through tailored contracts and service agreements, aligning with specific business requirements and growth objectives.
Recent adjustments in database licensing models impact the portability of Open-Source Database Software. Organizations that adopt relational databases, projected to grow from USD 4,469 million in 2026 to USD 7,534.3 million by 2033, experience challenges when switching between different database systems. Traditional licensing structures often limit the transferability of data and applications, which raises costs for enterprises that migrate their databases or integrate them with third-party solutions.
Small and medium-sized enterprises (SMEs) represent a significant buyer group within the Open-Source Database Software market, driven by the need for flexible solutions that enable scalability and integration. SMEs frequently face constraints due to licensing terms that restrict the ability to customize or transfer databases, reducing operational efficiency. While the market evolves, organizations adopting vendor-managed database services, expected to expand from USD 4,213.9 million in 2026 to USD 8,243.2 million by 2033, will seek solutions that offer greater flexibility and portability.
These licensing changes influence overall market dynamics, prompting buyers to prioritize database solutions that support interoperability. Firms that adapt their offerings to support portability strengthen their competitive position and address the specific needs of SMEs.
Cost considerations heavily influence the choice between managed and self-hosted PostgreSQL solutions. This rapid expansion indicates increasing interest among businesses in leveraging managed services for their databases, driven by operational efficiency and reduced maintenance burdens.
On the other hand, self-hosted PostgreSQL presents significant upfront costs related to infrastructure, personnel, and long-term maintenance. Organizations opting for self-hosted solutions often face challenges in scalability and require dedicated resources for effective management. Both approaches offer unique benefits, and the decision often hinges on a company's operational capacity and long-term strategy.
Evaluating these costs in the context of the Open-Source Database Software market leads to informed decisions that impact overall budget and resource allocation. Businesses that prioritize cost efficiency and scalability lean toward managed services, while those with specific customization needs favor self-hosted options.
The growing interest in Open-Source Database Software among small and medium-sized enterprises (SMEs) drives market expansion. These businesses increasingly seek cost-effective solutions without the burden of licensing fees associated with proprietary software. The shift toward digital transformation drives heightened demand for scalable database solutions that support operational agility. Revenue from SMEs in this segment is projected to reach USD 3,991.7 million by 2033, reflecting a compound annual growth rate of 9.3%. This trend indicates that SMEs prioritize flexibility and innovation, leading to increased volume in the market and a positive impact on overall pricing structures.
The escalating use of open-source options across various sectors enhances competitiveness, enabling SMEs to access advanced data management capabilities without the high costs typically linked to licensed software. This transition reinforces the appeal of open-source database solutions.
The rising demand for vendor-managed database services drives growth in the Open-Source Database Software market. This shift stems from the increasing complexity of data management, which challenges organizations to maintain efficient operations. Companies frequently require enhanced scalability, security, and reliability, driving them to adopt managed services offered by external providers. Those using these services benefit from reduced operational burdens and improved performance, allowing them to allocate resources to core business functions.
Enterprises, particularly large organizations, leverage vendor-managed solutions to streamline database management, which reduces costs associated with in-house infrastructure and expertise. The need for quick deployment and maintenance further supports the transition towards these services. Consequently, vendor-managed database services are projected to capture USD 1,004.1 million of the market, reflecting the ongoing trend of outsourcing critical IT functions. This development highlights a fundamental shift towards managed solutions, shaping future dynamics within the market.
Price sensitivity among buyers poses a significant barrier to the Open-Source Database Software market. Large enterprises, while interested in robust solutions, often face budget constraints that restrict spending on new software. This price consciousness leads to slower uptake of advanced functionalities, resulting in reduced orders or delayed system replacements. Small and medium-sized enterprises experience similar challenges, where tight budgets hinder access to essential tools that enhance operational efficiency. The cost of implementation and ongoing maintenance for sophisticated database solutions exacerbates this issue, making it more difficult for these organizations to transition from traditional systems. Consequently, this financial limitation impacts overall market growth, with potential users hesitating to invest in open-source database solutions due to their long-term benefits and capabilities.
Profitability challenges arise from increasing operational costs associated with talent acquisition and retention in the Open-Source Database Software market. Demand for skilled personnel in database management has surged, leading to higher salary expectations and competition among employers. Many suppliers experience pressure on margins, limiting their ability to invest in technology and development. In response, suppliers implement strategies to optimize operations, focusing on automation and enhancing existing offerings to reduce reliance on high-cost talent. Several companies pursue partnerships to gain access to specialized skills without bearing the full costs of hiring new talent. This approach allows suppliers to maintain competitive pricing while navigating the challenges of rising operational costs. The evolution of technology influences these strategies, encouraging a shift toward cloud-based solutions that minimize the need for extensive in-house expertise. Suppliers emphasize scalable offerings to accommodate a broader range of clients while managing cost structures effectively.
The increasing adoption of open-source database solutions among small and medium-sized enterprises presents a notable growth opportunity. With a projected compound annual growth rate (CAGR) of 9.3% through 2033, this segment demonstrates significant potential within the market. These enterprises often seek cost-effective alternatives to proprietary database solutions, driving demand for open-source options that offer flexibility and lower total ownership costs. The shift toward managing databases without extensive upfront investment aligns well with the operational constraints typically faced by smaller organizations. The rise of customer-managed software subscriptions and licenses further supports this trend, enhancing market penetration among these buyers. Increased awareness of open-source database capabilities enables small and medium-sized enterprises to optimize their data management processes, fueling growth within this segment.
The Global Open-Source Database Software market is segmented based on Database Type, Delivery Model, Organization Size, and End-Use Industry.
This segment serves businesses that require structured data storage and management, with applications spanning IT services, financial systems, and e-commerce platforms. The increasing emphasis on data-driven decision-making fuels demand for relational databases, particularly among large enterprises. Compared to other database types, including key-value or document databases, this segment experiences steady growth, driven by a robust customer base that prioritizes data integrity and complex querying capabilities. The segment's growth trajectory reflects its critical role in supporting enterprise-level applications, which depend on the reliability and performance offered by relational database systems. In addition, the continued evolution of technology within the sector enhances user experience and operational efficiency.
Key-Value Databases segment is estimated to reach USD 1,002.8 million by 2033, at a CAGR of 7.9% during the forecast period. This database type provides a flexible and scalable solution for applications requiring high-speed access to data, making it popular among developers and businesses in sectors including e-commerce and social media. Demand for simplicity in data storage and retrieval drives growth within this segment, promoting adoption in dynamic environments. Compared to other database types, Key-Value Databases offer lower implementation costs and reduced complexity, appealing to several smaller enterprises and startups. The anticipated growth differs from other segments, including Relational Databases, which holds a larger market share but demonstrates a slower CAGR of 7.7%. The adoption of Key-Value Databases signifies a shift towards agile data management solutions that align with modern application requirements.
Document Databases segment is expected to reach USD 654.5 million by 2033. This segment serves various industries, enabling the management of unstructured data efficiently. Companies in sectors including IT and telecommunications leverage Document Databases for their flexibility in handling diverse data types, including text files, images, and JSON formats. Increasing demand for data-driven decision-making drives growth in this segment. A notable factor driving this trend is the surge in big data analytics, which requires robust solutions for data storage and retrieval. In comparison to other database types, Document Databases exhibit a unique appeal due to their adaptability, though their growth rate is slower than Key-Value Databases, which achieve a CAGR of 7.9%. The market anticipates sustained expansion for Document Databases as businesses prioritize data management solutions that support evolving data needs.
Wide-Column Databases segment is projected to grow at a CAGR of 7.2% during the forecast period. This type of database stores and manages data in a flexible schema format, making it suitable for applications requiring scalability and high availability. Large enterprises and organizations in sectors including telecommunications and e-commerce adopt wide-column databases to efficiently handle vast amounts of unstructured or semi-structured data. The demand for this segment benefits from increasing data generation and the need for real-time analytics. Unlike other database types, wide-column databases offer unique advantages in data retrieval speed and flexibility, although they often do not achieve the same level of popularity as relational databases, which are valued at USD 4,469 million in 2026 and are projected to reach USD 7,534.3 million by 2033. This distinct positioning allows wide-column databases to cater to specific use cases while contributing to the overall growth of the market.
Time-Series Databases focus on the management and analysis of time-stamped data, providing capabilities for applications including monitoring, analytics, and Internet of Things (IoT) data management. Industries like finance, telecommunications, and healthcare employ this type of database to track changes over time, making it essential for real-time decision-making. The increasing volume of data generated by these industries drives demand for time-series solutions, aligning with the need for accurate and timely insights. Compared to other database types, Time-Series Databases attract users requiring specialized functionalities to handle time-dependent data, differentiating them with specific performance optimizations. The segment reflects the growing importance of data analytics across sectors. While other database types focus on general data storage and management, Time-Series Databases prioritize efficiency in temporal data processing, ensuring they effectively support the evolving data landscape.
Graph Databases employ graph structures to store and represent data, focusing on the relationships between entities. These databases cater to sectors including social networks, recommendation systems, and fraud detection and prevention applications. The increasing need for real-time data processing and complex querying capabilities drives demand in this segment. Graph Databases appeal to organizations that require enhanced data connectivity, distinguishing them from other database types. Compared to Relational and Document Databases, Graph Databases support more intricate data relationships, enabling more dynamic data exploration. While other segments experience varied growth rates, Graph Databases hold unique advantages in scenarios demanding complex relationship mapping, demonstrating their relevance in a data-driven landscape. The market evolves continually, prompting organizations to adapt to trends in data management and integration.
Vector Databases store and manage high-dimensional data, focusing on applications including machine learning and artificial intelligence. This segment serves industries demanding advanced data retrieval and analysis capabilities, including IT, telecommunications, and financial services. Key drivers of growth in this segment include the rapid expansion of artificial intelligence technologies and the increasing need for efficient data processing. Unlike other database types, Vector Databases enable faster retrieval of complex data structures, making them particularly valuable for applications involving large datasets. Competing database segments cater to general storage needs, while Vector Databases specifically target scenarios requiring high performance and precision in data handling. The unique functionality and application scope differentiate this segment from others, positioning it as an essential component within the broader Open-Source Database Software market.
Others (Object Databases, RDF Triple Stores) include specialized database types that support unique data storage and retrieval methods. These databases find applications in industries requiring complex data relationships and semantic data querying, including research institutions and advanced analytics firms. The increasing demand for sophisticated data modeling and schema flexibility drives growth in this segment. Users prioritize flexibility and adaptability, distinguishing this segment from more traditional database types that rely on static schemas. The growth rate of Others is lower compared to the faster-growing segments, but the unique capabilities serve specific niches, appealing to organizations focused on innovative data solutions. Ongoing advances in object database and RDF triple store technologies keep these systems relevant to current data management strategies.
This segment caters to organizations seeking comprehensive management of their database systems, allowing for enhanced focus on core business activities. Enterprises, particularly large ones, increasingly prefer vendor-managed services to benefit from reduced operational burdens, leading to higher demand. A major driving force includes the growing necessity for scalability and flexibility in database management, enabling organizations to adapt to evolving market demands. Compared to other segments, including Customer-Managed Software Subscriptions and Licenses, this segment experiences faster growth due to its appeal among businesses prioritizing efficiency and reliability. The market reflects a shift toward managed services, focusing on cost-effectiveness and improved operational performance.
This segment encompasses software solutions that users manage independently, allowing customization and control over database environments. Organizations across various industries, particularly small and medium-sized enterprises, increasingly adopt these subscriptions for flexibility and cost management. Demand in this segment is driven by the growing preference for on-premises solutions that enhance data security. Compared to Vendor-Managed Database Services, which experience a higher CAGR of 10.1%, this segment demonstrates slower growth attributed to the higher operational burden on users for maintenance and management. The market increasingly favors offerings that provide a balance between control and ease of use, influencing investment strategies among organizations seeking to optimize their database solutions.
Standalone Support and Maintenance segment is expected to reach USD 1,068.5 million by 2033. This segment serves organizations that require assistance in managing and maintaining their open-source database solutions. It includes technical support, troubleshooting, and software updates, appealing primarily to large enterprises and small and medium-sized enterprises (SMEs) that rely on stable database performance. The demand for reliable support services drives growth in this segment, with an increasing number of businesses adopting open-source databases. Comparatively, this segment experiences slower growth than Vendor-Managed Database Services, which is projected to grow at a CAGR of 10.1%. The Standalone Support and Maintenance segment's growth is influenced by the necessity for ongoing assistance, especially in complex environments, where expert support ensures optimal performance and minimizes downtime.
Valued at USD 4,336 million in 2026, this segment is projected to reach USD 7,351.6 million by 2033, at a CAGR of 7.8% during the forecast period. Large enterprises use open-source database solutions to manage substantial volumes of data, enhance operational efficiency, and reduce costs associated with proprietary software. The increasing demand for scalable and flexible database options drives growth within this segment, reflecting a shift toward cost-effective solutions among larger organizations. Compared to the Small and Medium-Sized Enterprises segment, this segment experiences slower growth due to established processes and existing infrastructure in large firms. However, regulatory compliance and data governance remain crucial factors influencing adoption of open-source database software. The market identifies significant opportunities for vendors that provide tailored solutions to address the unique needs of large enterprises.
Small and Medium-Sized Enterprises segment is estimated to reach USD 3,991.7 million by 2033, at a CAGR of 9.3% during the forecast period. This segment primarily serves businesses that require flexible and cost-effective database solutions to manage their data efficiently. The increasing demand for digital transformation among small and medium-sized enterprises drives growth, with many seeking scalable database solutions to enhance operations. Compared to Large Enterprises, this segment displays a faster growth trajectory, attributed to a heightened focus on adopting innovative technologies within a constrained budget. The market's emphasis on affordability and functionality positions Small and Medium-Sized Enterprises as key players in the Open-Source Database Software market, driving competition and innovation.
Valued at USD 1,789.8 million in 2026, this segment is projected to reach USD 3,172.7 million by 2033, at a CAGR of 8.5% during the forecast period. The IT and Telecommunications segment serves various industries, including telecom operators and IT service providers, focusing on enhancing operational efficiency and managing vast amounts of data. Growth stems from increased demand for scalable solutions that support data-driven decision-making. The requirement for real-time data processing and analytics drives significant investments in open-source databases, differentiating this segment with a higher growth rate compared to others. The competitive landscape compels organizations to seek cost-effective alternatives to proprietary database solutions, resulting in substantial adoption of open-source options. The expansion of this segment encourages innovation in product development.
Banking, Financial Services and Insurance segment is estimated to reach USD 2,083.8 million by 2033, at a CAGR of 7.8% during the forecast period. This segment serves a diverse range of financial institutions, including banks and insurance companies, focusing on data management for transactions, customer interactions, and compliance activities. The demand for robust data security and regulatory compliance drives growth within this segment, reflecting the critical nature of data integrity in financial operations. Compared to other segments, this area exhibits stable growth, supported by consistent investments in technology and digital transformation initiatives. The segment's growth rate of 7.8% positions it favorably against the broader market, while differing from segments like IT and Telecommunications, which experience more rapid expansion. The commitment to adopting open-source solutions facilitates enhanced data analytics capabilities, ensuring organizations remain competitive in an evolving financial landscape.
The Retail and E-Commerce segment is expected to reach USD 1,681.1 million by 2033. This segment primarily serves businesses involved in online sales and retail operations, where efficient database management is essential for driving customer engagement and sales performance. Demand in this segment is propelled by the increasing shift toward digital shopping, with retailers seeking to enhance customer experiences and streamline operations. Compared to other segments, Retail and E-Commerce exhibits a unique growth trajectory, characterized by rapid adoption of e-commerce personalization software and other technologies that facilitate personalized shopping experiences. The projected growth reflects a notable CAGR of 7.8% during the forecast period, driven by the growing necessity for robust data analytics and customer relationship management systems that support strategic decision-making.
The Healthcare and Life Sciences segment is projected to grow at a CAGR of 9% during the forecast period. This segment serves healthcare providers, pharmaceutical companies, and research institutions, focusing on data management for electronic medical records, clinical trials, and drug development. Increasing regulatory demands for data integrity and security support growth in this area, with organizations prioritizing open-source solutions to maintain compliance while optimizing operational costs. The pricing of solutions in this segment tends to be higher compared to others due to the critical nature of managing sensitive health data. With an estimated value of USD 1,681.1 million by 2033, this segment reflects strong demand from organizations seeking reliable, scalable, and flexible database solutions tailored for the healthcare industry. The market continues to advance, driven by the imperative for innovation and efficiency in improving patient outcomes.
Manufacturing employs open-source database software for various applications, including supply chain management, production planning, and quality control. Companies in this sector rely on data-driven insights to enhance operational efficiency and reduce costs. Demand for open-source solutions is fueled by the need for scalable platforms that integrate seamlessly with existing systems. Unlike other segments, the manufacturing industry experiences unique challenges, including real-time data processing and regulatory compliance, which drive the need for tailored solutions. The ongoing shift toward Industry 4.0 and smart manufacturing emphasizes the importance of data analytics in the sector, driving adoption. This segment differentiates itself through its focus on specialized use cases and requirements, standing out in growth potential compared to other segments in the market.
The Government and Public Sector segment employs open-source database software to enhance data management, streamline operations, and improve service delivery to citizens. Government agencies and public sector organizations use this software for various applications, including public record management and data analytics. The segment experiences growth driven by increasing demand for transparency and data accessibility among citizens. This sector faces unique regulatory challenges that influence adoption rates compared to other segments, including IT and Telecommunications, which exhibit a higher growth trajectory. The emphasis on compliance and security in the public sector creates distinct purchasing behavior, prioritizing cost-effectiveness alongside robust security features. This focus on regulatory compliance differentiates it from segments including Retail and E-Commerce, where agility and speed of deployment remain vital.
Media and Entertainment encompasses activities related to content creation, distribution, and consumption across various platforms. This segment serves professionals in film, music, gaming, and broadcasting industries, relying on open-source database software to manage vast amounts of multimedia data, user interactions, and analytics. Demand for innovative content delivery and personalized user experiences drives growth in this area. The need for real-time data processing and integration with evolving technologies encourages adoption among enterprises. Unlike other segments, Media and Entertainment experiences unique challenges related to licensing and rights management, influencing operational strategies differently. The potential for higher customer engagement drives investment in robust database solutions, contributing significantly to the market.
This sub-segment encompasses sectors including Energy and Utilities, Transportation and Logistics, and Education, which employ open-source database software for various key operations. Organizations within these industries use such software for managing large datasets, optimizing resource allocation, and improving operational efficiency. Demand for open-source solutions is driven by the need for cost-effective database management, particularly in sectors facing budget constraints. Compared to other segments, this sub-segment experiences slower adoption rates due to specific regulatory requirements and legacy systems that hinder transition. The open-source database software market continues to evolve, with these industries gradually embracing the advantages of open-source solutions to enhance their data practices.
Based on geography, the Global Open-Source Database Software market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Demand for open-source database software in North America benefits from a robust IT and Telecommunications industry, which drives significant investment in data management solutions. The United States, Canada, and Mexico prioritize innovation and technology adoption across sectors, propelling the market forward. In 2025, this region holds a share of 39.1% of the global market, reflecting its critical position in the overall landscape. Organizations increasingly recognize the advantages of scalable and flexible database solutions, leading to enhanced operational efficiencies. North America is projected to reach USD 4,249.2 million by the end of 2033, highlighting the potential for continued growth in the open-source database software market. Organizations increasingly transition to cloud-based services, driving demand for vendor-managed database services significantly.
The European market for open-source database software exhibits strong growth potential, driven by increasing demand from sectors including IT and telecommunications, along with banking, financial services and insurance. Germany, France, and the UK emerge as key countries, with robust digital infrastructure and innovation ecosystems enhancing adoption. The emphasis on data privacy regulations across Europe has heightened the focus on secure database solutions, enabling organizations to manage data effectively while adhering to compliance standards. By 2025, the market share in Europe is projected to reach 27.2%, reflecting significant investment opportunities. Growing reliance on cloud-based services and the shift toward digital transformation across various industries further support the expansion of the open-source database software market in this region.
In Asia-Pacific, the demand for open-source database software is driven by rapid digital transformation across various industries. Countries including China, Japan, and India invest significantly in technological advancements, creating an environment that supports the adoption of innovative database solutions. The IT and Telecommunications sector leads in this region, with businesses focusing on enhancing operational efficiency and data management capabilities. A growing emphasis on data analytics and cloud computing facilitates demand for robust and scalable database solutions. The market's share in the region is projected at 25.9% in 2025, reflecting increasing reliance on technology in sectors including retail, healthcare, and financial services, all of which benefit from the flexibility of open-source systems. Continuous investments in infrastructure further strengthen the market's growth potential.
Demand for open-source database software in South America highlights the region's unique economic and technological landscape. Growth arises primarily from Brazil and Argentina, where increasing digitalization in various sectors stimulates the adoption of these solutions. The region's share of the global market reached 4.3% in 2025, reflecting a growing recognition of the benefits offered by this technology. The market is driven by the necessity for efficient data management and cost-effective alternatives to traditional database systems. Companies in industries including retail and telecommunications actively seek out these solutions to enhance operational efficiency and data accessibility. Expanding IT infrastructure in urban centers facilitates the deployment and maintenance of open-source database software, encouraging further investment in this area.
The Middle East and Africa region represents a smaller share of the global market, estimated at 3.5% in 2025. In this region, demand primarily arises from the IT and Telecommunications sector, with significant investments aimed at enhancing data management and analytics capabilities. Saudi Arabia and the UAE lead in adopting advanced database solutions, driven by government initiatives focused on digital transformation and infrastructure development. South Africa demonstrates a growing interest in open-source database solutions among small and medium-sized enterprises, which seek cost-effective alternatives to proprietary software. The market experiences challenges related to varying levels of infrastructure maturity and technical expertise across different countries, impacting the pace of adoption. Continuous advancements in cloud technology and increasing awareness of open-source solutions contribute positively to market growth in the region.
The competitive environment in the Open-Source Database Software market comprises various companies adopting distinct strategies to maintain or enhance their market presence. Organizations compete on criteria including pricing, customization, service quality, and the breadth of their ecosystem offerings. Buyers seek solutions that align with their specific operational requirements, leading to diverse preferences across different sectors.
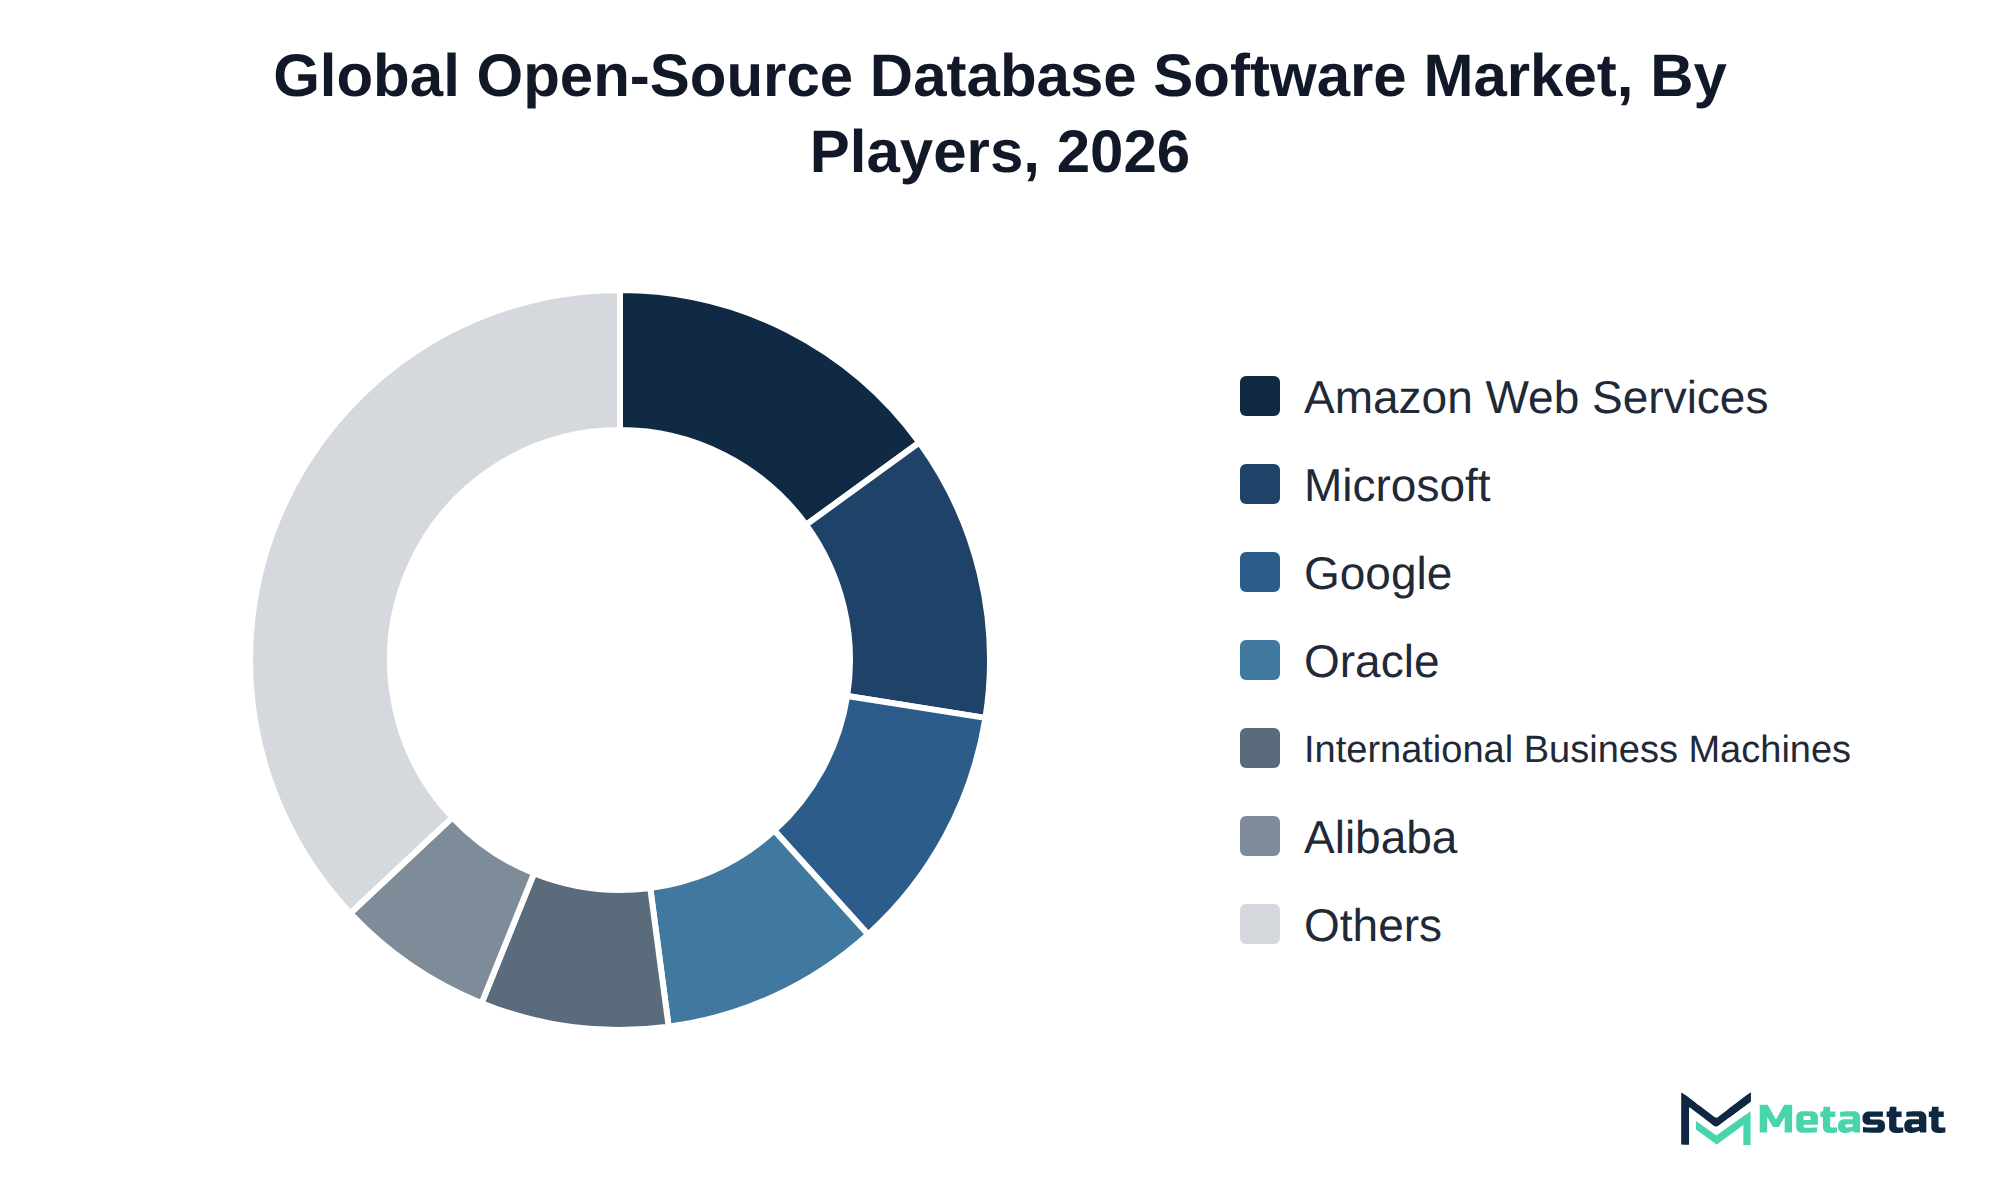
Many players focus on vendor-managed database services, which provide robust support and streamlined functionality. For instance, Amazon Web Services, Inc. emphasizes its comprehensive cloud services, enabling organizations to manage their databases effectively. Microsoft Corporation leverages its Azure platform to offer integrated database solutions tailored to enterprise needs, while Oracle Corporation prioritizes scalability and reliability, catering to large enterprises.
A segment of the market leans toward customer-managed software subscriptions and licenses, which grant organizations greater control over their database environments. Google LLC, with its flexible pricing models and scalability, attracts small and medium-sized enterprises. Similarly, MariaDB plc focuses on open-source solutions that enhance customization and adaptability, appealing to a diverse customer base. This strategic division among companies highlights the varied approaches in addressing the demands of the Open-Source Database Software market.
This growth hinges on several key developments within the Open-Source Database Software market. First, increasing adoption of vendor-managed database services will drive significant demand among large enterprises, resulting in an expected CAGR of 10.1% in this segment. Finally, heightened demand within the IT and telecommunications sector, with an expected increase from USD 1,789.8 million in 2026 to USD 3,172.7 million by 2033, will further support growth.
Potential risks exist that could impede this growth trajectory. Economic fluctuations or increased competition challenge market players, leading to slower adoption rates. These factors could significantly affect both revenue and investment in the Open-Source Database Software market. Stakeholders will need a clear understanding of these dynamics to plan effectively in this market.
By Database Type: Relational Databases, Key-Value Databases, Document Databases, Wide-Column Databases, Time-Series Databases, Graph Databases, Vector Databases, Others (Object Databases, RDF Triple Stores)
By Delivery Model: Vendor-Managed Database Services, Customer-Managed Software Subscriptions and Licenses, Standalone Support and Maintenance
By Organization Size: Large Enterprises, Small and Medium-Sized Enterprises
By End-Use Industry: IT and Telecommunications, Banking, Financial Services and Insurance, Retail and E-Commerce, Healthcare and Life Sciences, Manufacturing, Government and Public Sector, Media and Entertainment, Others (Energy and Utilities, Transportation and Logistics, Education)
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Open-Source Database Software market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 8.3% from 2026 to 2033 |
|
Revenue Unit |
USD million |
|
Segmentation |
By Database Type, Delivery Model, Organization Size, End-Use Industry, and Region |
|
By Region |
North America (By Database Type, Delivery Model, Organization Size, End-Use Industry, and Country)
|
|
Europe (By Database Type, Delivery Model, Organization Size, End-Use Industry, and Country)
|
|
|
Asia Pacific (By Database Type, Delivery Model, Organization Size, End-Use Industry, and Country)
|
|
|
South America (By Database Type, Delivery Model, Organization Size, End-Use Industry, and Country)
|
|
|
Middle East and Africa (By Database Type, Delivery Model, Organization Size, End-Use Industry, and Country)
|
Find answers to common questions about this report
The Open-Source Database Software market size was valued at USD 5,968.5 million in 2025.
The market is projected to grow at a CAGR of 8.3% during the forecast period from 2026 to 2033.
The North America Open-Source Database Software market size is estimated to reach USD 4,249.2 million by 2033.
Relational Databases lead the Open-Source Database Software market with a projected value of USD 7,534.3 million by 2033, reflecting the highest growth compared to other database types.
The growing interest in open-source database solutions among small and medium-sized enterprises (SMEs) drives market expansion, with these businesses seeking cost-effective options without licensing fees. Increased demand for vendor-managed database services due to the complexity of data management enhances scalability, security, and reliability for organizations.
North America holds the dominant share of the Open-Source Database Software market, with a projected value of USD 4,249.2 million in 2033, representing 39.1 percent of the total market. This figure surpasses the shares of other regions significantly.
Price sensitivity among buyers poses a significant barrier, as large enterprises and SMEs face budget constraints that limit spending on new software. Profitability challenges arise from increasing operational costs associated with talent acquisition and retention, pressuring suppliers' margins and hindering investment in technology and development.
The increasing adoption of open-source database solutions among small and medium-sized enterprises is driven by the demand for cost-effective alternatives to proprietary software. This segment is expected to grow significantly, with a projected compound annual growth rate of 9.3% through 2033, as these businesses seek flexible solutions that align with their operational constraints.
The Open-Source Database Software market is estimated to reach a valuation of USD 11,343.4 million by 2033.
Key players operating in the Open-Source Database Software market include Amazon Web Services, Inc., Google LLC, Microsoft Corporation, Oracle Corporation, International Business Machines Corporation, Alibaba Group Holding Limited, and MariaDB plc.
The analysts below cover Information & Technology research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Floating offshore wind feasibility relies heavily on specialized installation vessel availability and port crane limits, which most broad renewable energy forecasts ignore. The report delivered a thorough analysis of dry dock capacity, mooring chain supply constraints, and raw material pricing trends for deepwater anchor installations. It served as a solid independent sanity check for our offshore project capital expenditure assumptions.
Assessing commercial microgrid software adoption requires looking past top-level installation numbers and examining utility interconnection queues. The research provided verifiable data on average permitting timelines, tariff structures, and battery storage integration costs across regional utility territories. That grounded perspective was valuable for our team when building five-year demand projections for industrial microgrid controllers.
Ambulatory surgical centers have very different purchasing cycles for robotic-assisted surgery platforms than major hospital networks. The MetaStat Insight study focused squarely on capital expenditure depreciation, procedural reimbursement pathways, and surgeon training overhead. That operational clarity made it much simpler to validate multi-year procedure growth forecasts against actual ambulatory center adoption patterns.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950
Starting from
$2950