
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Nespresso Capsules Market By Type (Classic Coffee Capsules, Flavored Coffee Capsules, Decaffeinated Flavored Capsules, and Specialty Flavored Capsules (Vanilla, Caramel, Hazelnut), By Application (Home Use and Commercial Use), By Sales Channel (Online Retailers, Supermarkets and Hypermarkets, Coffee Shops and Cafes, Specialty Stores, Direct Sales (Company Websites), and Others, By Industry Analysis, Size, Share, Growth, Trends, and Forecast, 2026-2033
MSI-3282
January 13, 2026
Updated
255 Pages
Report Details
Comprehensive Market Analysis And Insights
Nespresso Capsules market was valued at USD 32.7 billion in 2026 and is projected to reach USD 57.5 billion by 2033, at a CAGR of 8.4% during the forecast period.
The Global Nespresso Capsules market form a niche segment within the beverage market that specifically addresses convenience, flavor, and premium experience. As it connects advanced technology to consumers' wants for good coffee, well-served and on-demand, this product has captured people's imagination unlike most conventional approaches toward brewing. With this efficient approach toward offering an uncomplicated coffee solution through today's hurried lives while providing the attraction of gourmet, one may explain a global interest that cannot be resisted by a new trend like that.
One of its defining characteristics about this market would be its penchant for innovation towards products. As such, firms and companies tend to extend and expand their production lines with such new flavors that are in development, limited-time blends, as well as responsible packaging options to cater to customers' various flavors and address consumers' increased requirement for sustainable-oriented products across geographies. It would be expected to evolve in directions that make the Global Nespresso Capsules market more compatible with broader sustainability goals, given greater emphasis on reduction of waste and adoption of ecologically friendly practices.
Another critical aspect of this market is its dependence on complex marketing strategies. Brands use a combination of aspirational branding, digital outreach, and direct-to-consumer sales models to secure a loyal customer base. The ability to create an exclusive sense through collaborations with renowned chefs, designers, or hospitality chains differentiates the market from other segments in the beverage industry. Such efforts enhance brand identity and deepen the connection between consumers and their coffee experience.
Geographically, the Global Nespresso Capsules market has been very adaptable to regional tastes. For example, manufacturers may have specific coffee blends tailored to the flavor profiles preferred in Europe, Asia, or the Americas. This localization strategy ensures that the market remains relevant across diverse demographics, further strengthening its global footprint. The industry will likely continue to experiment with such regional variations, leveraging local insights to drive product development.
Technological development is also creating the course for this market. Machines that customize the coffee from users to capsules intended to preserve aromas better; in short, technology is the real enhancer that provides an improvement in the final consumer experience. When smart home appliances are so seamlessly integrated in people's everyday lives, innovation that would mean easy connectivity, along with preference-based recommendations, might easily find its space in the market.
With the multitude of strengths this market boasts, there are weaknesses that require consistent adaptation. Such factors as shifting raw material cost fluctuations, the regulatory pressures in place, and the need to ensure consistent quality will call for strategic responses by industry stakeholders. How well they are addressed determines the long-term strength of the market.
As the global awareness of coffee culture is further expanded, the Global Nespresso Capsules market will lead the way for future trends. The industry is capable of rewriting the rules for convenience coffee through innovation and sustainability balanced with the insight of the consumer. The dynamic interplay of these factors makes strategic foresight crucial to ensuring that the market remains a strong force within the beverage sector. Through an unwavering commitment to quality, the market will likely sustain its relevance and appeal to both existing and emerging coffee enthusiasts worldwide.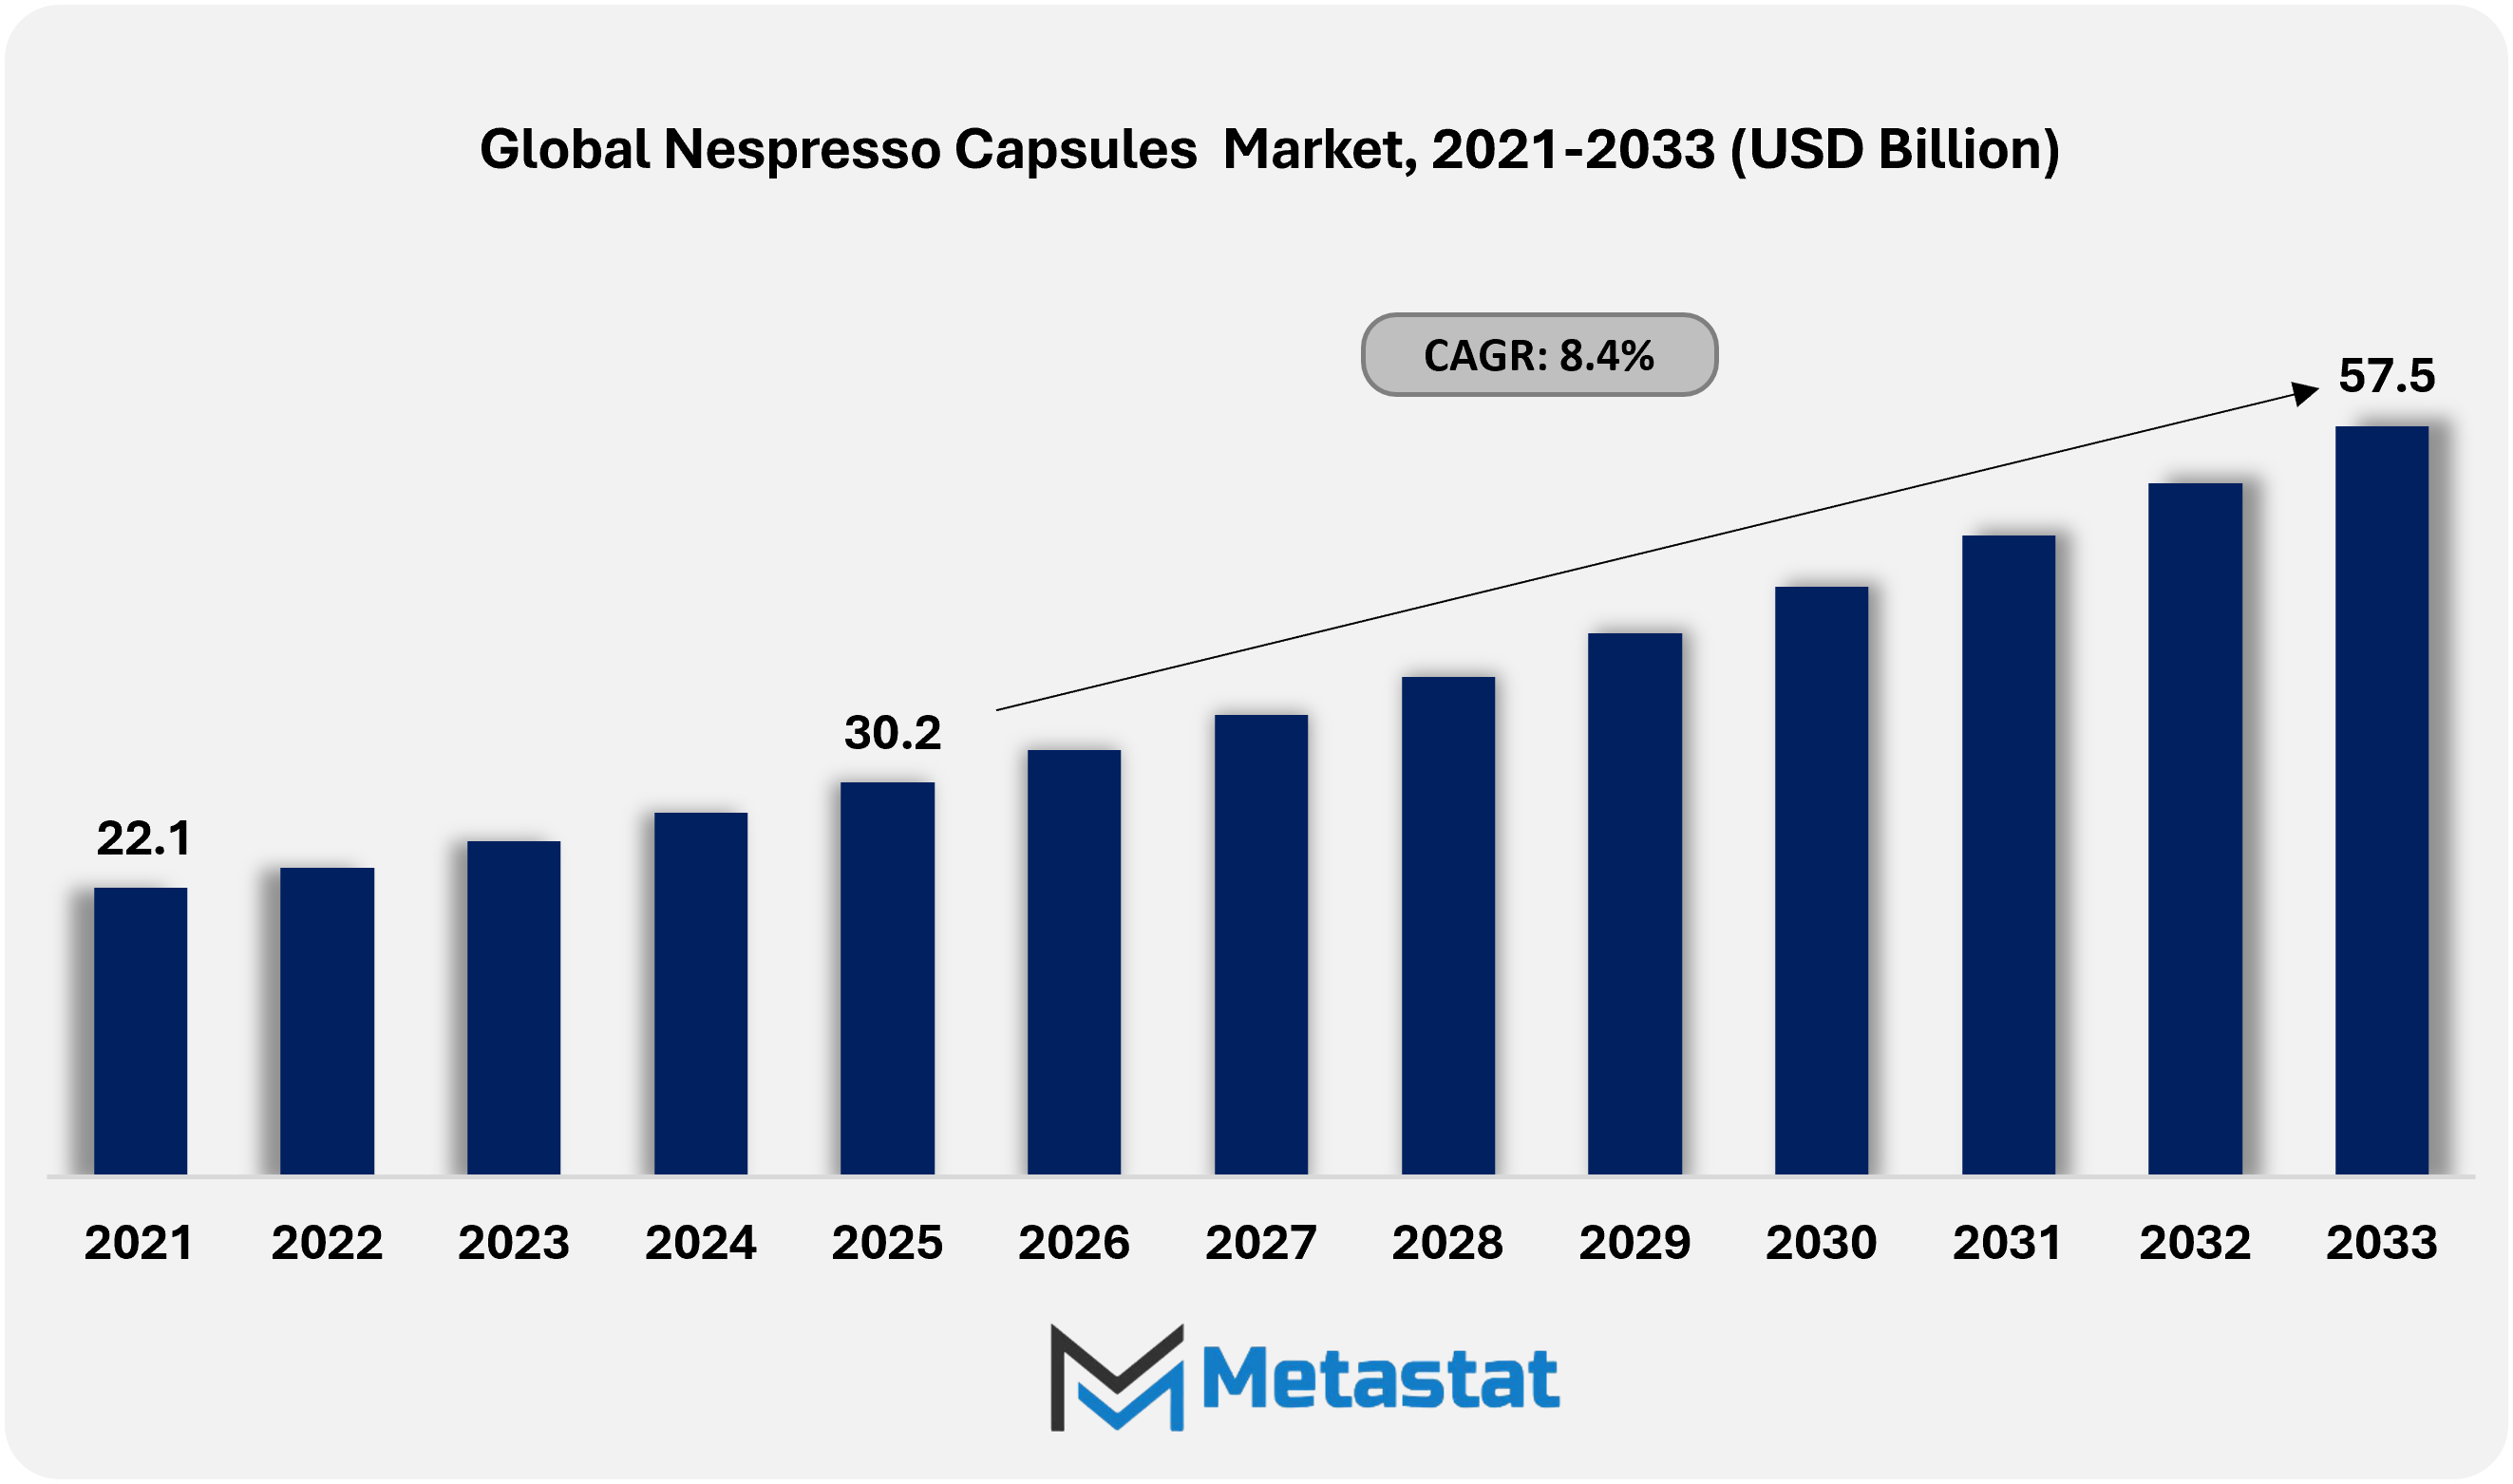
Importantly, the world market for Nespresso capsules expands because consumers demand convenient and excellent coffee solutions right in their houses. As time goes by and people's life tends to be increasingly busy, individuals need to obtain premium coffee even without leaving the house. It is also of great importance the fact that adoption of coffee makers in both house and office domains is growing progressively everywhere in the world. These machines simplify the process of preparing coffee and make them popular in people's minds, especially if they are in search of convenience along with quality in their everyday life. This growth notwithstanding, there are certain barriers that can impact the future of the market.
The primary challenge is that Nespresso capsules are costlier than traditional brewing methods. The price can be quite off-putting for some budget-conscious buyers, even though most consumers would pay the extra price for premium quality. This includes environmental concerns; because most pods are made from non-biodegradable materials, which have elicited criticism due to the high volume of wastes created. Sustainability is an emerging factor as consumers across the globe raise issues about wastes that these products cause. To overcome these, companies in the Nespresso capsules market are developing eco-friendly and compostable alternatives.
Such innovations have been demonstrated to appeal to environmentally conscious consumers due to the ability to meet their values while not forgo outstanding convenience or quality. Still, the scope for the huge markets that can be overtaken by shifting toward sustainable options is enormous in combining demand for good quality coffee with a commitment to reducing environmental harm.
In conclusion, the Nespresso capsules market is being shaped by convenience, quality, and sustainability interplay. Factors such as increasing usage of coffee machines and consumer preference for premium at-home coffee are driving growth. However, high costs and environmental concerns continue to be significant challenges. Nevertheless, the future of expansion for sustainable and compostable capsules looks exciting. By addressing these factors, the industry can continue on its growth trajectory with the changing nature of consumers while responding to other global sustainability targets.
Aluminum capsules remain the primary industry packaging standard because aluminum provides a total barrier against oxygen, moisture, and light, keeping freshly ground coffee shelf-stable for long periods. However, collecting and recycling aluminum pods requires dedicated municipal sorting or private drop-off networks. Major capsule producers invest heavily in proprietary collection bags, collection points in specialty coffee stores, and partnerships with postal carriers to close the loop on aluminum recovery.
Compostable capsules made from plant-based polymers and paper pulp have emerged as an alternative to traditional single-use packaging. Industrial and home-compostable capsules allow users to dispose of spent grounds and packaging together in organic waste bins. Developing certified home-compostable barrier films that prevent oxidation without degrading during hot-water extraction represents a major technological achievement across the industry.
Third-party sustainability certifications, including Fairtrade, Rainforest Alliance, and B Corp standards, are now common requirements for premium capsule lines. Brands communicate ethical supply chains, regenerative agriculture practices, and fair grower compensation directly on capsule packaging to win the trust of eco-conscious consumers.
Cold-brew-style extraction and iced coffee represent significant whitespace in the capsule market. Brewing cold coffee over ice requires specifically formulated beans and darker roasts designed to resist dilution. Additionally, consumer interest in functional wellness coffees—such as pods enriched with vitamins, adaptogens, and nootropics—offers roasters a runway for value-add premiumization.
The post-pandemic return to workplaces and commercial travel created new demand for hygienic, single-serve coffee formats. Premium hotels, boutique offices, and co-working environments increasingly install dedicated commercial capsule machines to eliminate waste, ensure consistent cup quality, and avoid the complex maintenance required by traditional commercial espresso machines.
Government packaging mandates and extended producer responsibility (EPR) regulations pose a major challenge to the capsule sector. Jurisdictions across the European Union and select North American states enforce strict recycling targets, requiring manufacturers to fund recycling infrastructure or pay packaging levies. Pods that fail to meet compostability or recyclability criteria face potential municipal bans and retail shelf restrictions.
Surging green coffee bean prices, caused by climate disruptions and logistics bottlenecks in primary origin countries, compress profit margins across the industry. When combined with elevated energy costs and aluminum packaging prices, roasters face intense cost pressures. Passing these rising costs on to consumers risks driving price-sensitive buyers toward bulk whole-bean or ground coffee alternatives.
Global Nespresso Capsules has witnessed steady growth over the years mainly propelled by growing demands for premium quality and convenient coffee. The market has fragmented itself into various offerings based on preferences. These are segmented into several categories: Classic Coffee Capsules, which alone form the majority and comprise a major share of around $13,228.52 million. The others include Flavored Coffee Capsules, Decaffeinated Flavored Capsules, and Specialty Flavored Capsules with Vanilla, Caramel, and Hazelnut flavors. This diversifies the appeal of the market.
One of the key reasons for this market's growth is the lifestyle of the consumer. Consumers, being busier nowadays, want a product that will be convenient for them while offering quality. The Nespresso capsule meets the criteria very well. They enable people to have a café experience at home. Also, the variety of flavors and styles is such that there is something for everybody, from the traditional coffee lover to the aficionado of unique and exotic blends.
The premium experience that is growing demand for Nespresso capsules is also worth considering. Coffee is just not a liquid anymore but can be seen more as an added comfort in an individual's busy day to find energy and enthusiasm. More individuals are using such capsules for making the perfect Nespresso with available machines and also because they will work seamlessly on any of their machines.
Recently, it has also become important to sustain the environment. Many producers have just started to focus on the green environment, for example, the use of recyclable capsules or sourcing coffee beans from the most ethical and sustainable farms, which appeals to a growing section of conscious consumers.
The segmentation within the market also enables a firm to target specific groups of customers. Because of their popularity and affordability, Classic Coffee Capsules remained market leaders, while flavored and specialty options catered to customers looking for variety. Decaffeinated options ensured that even those avoiding caffeine can still appreciate the taste of coffee without compromise.
In conclusion, the Global Nespresso Capsules market thrives on its ability to adapt to consumer preferences, offering convenience, quality, and sustainability. With diverse options tailored to meet different tastes, this market continues to grow and appeal to a wide audience. It demonstrates how innovation and consumer focus can drive success in today’s competitive environment.
The global Nespresso capsules market is divided into two major applications: home use and commercial use. These categories capture the diverse preferences and needs of consumers worldwide, which influence trends and drive market growth.
Home use has become about convenience and quality. Consumers are increasingly looking for the ease of brewing premium coffee at home, which these capsules deliver. Whether for starting the day or enjoying a relaxing moment, the ability to create café-style coffee without stepping outside is a key reason for their popularity. The capsules provide a consistent experience, allowing users to explore a variety of flavors and intensities tailored to their preferences. As more individuals prioritize convenience and indulgence, this segment continues to grow, fueled by advancements in technology and expanding flavor options.
The commercial use segment caters to the needs of businesses, such as cafes, offices, and hospitality. Here, efficiency, reliability, and quality beverages for customers or employees are the key focus. Nespresso capsules help businesses streamline their coffee services while maintaining a high standard of taste. For office environments, they contribute to employee satisfaction by offering an easily accessible and enjoyable coffee break option. Likewise, a cafe and a restaurant can avail of these coffee capsules for its diversification for different customer's tastes and flavor without having complex traditional preparation systems.
With compatible machines increasingly becoming available and premium experience demand on both segments, the market continues to grow. Manufacturers are innovating, with improvements in sustainable packaging and distinct blends for environmentally conscious consumers. This makes the market adapt to changing consumer expectations and expands its base.
In addition, marketing strategies with a focus on luxury, convenience, and a promise of an excellent experience still appeal to the consumer. Recognizing the worth of Nespresso capsules by home and commercial users, the market is now a hallmark of modern coffee culture.
It clearly shows that these capsules meet various lifestyles and professional needs of consumers. Such division of the market between home and commercial use helps to meet the demand of the consumers and allows for the sustainable growth and adaptability of the Nespresso capsules market as it develops to address new challenges and preferences.
The Nespresso capsule market has grown exponentially in the past few years due to factors like more consumption of coffee and the need for easy options for brewing. The market is diversified into channels for sales, because by showing the different types of divisions into the sale, it meets the various needs of the consumer who varies their purchase behavior. The distribution channels include online retailers such as Amazon and specialty coffee websites, supermarkets and hypermarkets, coffee shops and cafes, specialty stores, direct sales through company websites, and other smaller outlets.
One of the most significant impacts on market shares can be seen with online retailers, giving consumers much easier ways to browse and make purchases from comfort of their homes. Through Amazon, for example, many options abound, coupled often by reviews that assist in buying decisions. For specialty coffee enthusiasts, specialty coffee websites have been attractive toward unique blends or quality-level capsules not otherwise found in traditional retail stores.
Supermarkets and hypermarkets continue to be strong sellers of Nespresso capsules because of their easy accessibility and availability to buy capsules in conjunction with other household items. Capsule flavors and strengths are widely available in most stores, so this is an accessible option for most consumers. The same applies to coffee shops and cafes. By selling capsules to customers who drink their beverage in-store, such houses extend the experience of their brand into homes. Specialty stores will cater to a niche audience.
They are more known for offering personable services and good expert advice on specific tastes regarding the capsules that will best fit their preferences. It allows customers to look into premium and limited-edition items that may not be easily accessible elsewhere.
Direct sales through company websites have also boomed, offering exclusive lines while maintaining authenticity and quality. Brands often use such channels to foster customer loyalty through subscription services or exclusive deals. In other words, smaller, less mainstream outlets that just happen to stock Nespresso capsules as part of larger lines of products. Together, the channels create a diverse and vibrant market, from which consumers may choose the means of purchase best suited to their needs.
Overall, the global Nespresso capsules market reflects a well-structured network of sales channels that adapt to evolving consumer behaviors, ensuring accessibility and variety for coffee lovers worldwide. The interplay between these channels supports the continued growth and prominence of this market segment.
Nestlé Nespresso established its early footprint through the OriginalLine platform, which relies on a classic high-pressure extraction method to brew traditional espresso and lungo styles. Because the original patents for this format expired, the format transitioned into an open industry standard. OriginalLine machines continue to maintain a massive installed base, especially across European households and urban spaces where espresso consumption is entrenched. The market for OriginalLine capsules is highly price-competitive due to the influx of alternative options that fit the exact same espresso machine ecosystem.
VertuoLine capsules represent Nestlé Nespresso's strategic answer to North American and global demand for larger cup sizes, including standard drip-style coffee, gran lungo, and alto formats. The system uses Centrifusion technology, spinning the capsule at high speeds while reading an embedded barcode on the capsule rim to adjust brew parameters automatically. Strong patent protections on VertuoLine capsules shield the format from generic copies. As a result, Nestlé retains strict control over capsule manufacturing, pricing, and gross margins within the Vertuo segment.
Third-party compatible capsules have captured significant market volume in the OriginalLine segment. Major multinational roasters and independent private label challengers manufacture compatible aluminum capsules and compostable alternatives at lower retail price points. These third-party entrants offer consumers accessible options across supermarkets and online retail platforms without requiring a machine upgrade. This dynamic exerts margin pressure on proprietary pods while simultaneously expanding the addressable espresso machine ecosystem.
Single-origin coffee capsules are leading the premiumization trend across the single-serve sector. Consumers increasingly seek beans sourced from specific micro-lots and recognized producing countries such as Ethiopia, Colombia, and Guatemala. Roasters highlight distinct terroir notes, altitude details, and traceable farm practices on capsule packaging. This focus on provenance brings third-wave specialty cafe culture into the convenience-driven home brewing ritual.
While traditional dark roast varieties remain a foundational preference for milk-based espresso drinks, consumer preferences are diversifying. Medium and light roast profiles are expanding rapidly within pod portfolios. Lighter roasts retain delicate floral, citrus, and berry notes, catering to younger coffee drinkers who prefer bright, nuanced extractions over heavy bitterness.
Flavored capsules have evolved beyond simple synthetic syrups into sophisticated, naturally infused flavor formulations. Common offerings include roasted hazelnut, vanilla bean, caramel, and seasonal profiles tailored for autumn and winter demand. Boutique roasters and established brands formulate these profiles to balance smoothly with milk or plant-based alternatives, tapping into cafe-inspired at-home coffee trends.
Direct-to-consumer (DTC) channels, anchored by dedicated brand websites and mobile applications, provide manufacturers with vital customer relationship management capabilities. Proprietary DTC models enable automated replenishment subscriptions, personalized roast recommendations, and seamless integration with capsule return-for-recycling programs. This channel protects brand equity and delivers superior gross margins compared to wholesale distribution.
Specialty coffee stores and brand boutiques serve as experiential touchpoints rather than high-volume inventory clearinghouses. Located in upscale shopping districts and metropolitan hubs, these boutiques allow consumers to taste limited-edition roasts, observe new machine demonstrations, and drop off used aluminum capsules. The boutique model functions as a brand-building vehicle that reinforces a luxury positioning.
Supermarkets and mass grocery chains dominate third-party compatible capsule distribution. Everyday consumers favor the ease of adding compatible coffee pods to their weekly grocery carts. Meanwhile, third-party online retail platforms provide rapid delivery, cross-brand price discovery, and multi-pack bulk purchasing, driving significant volume for both private label challengers and premium specialty roasters.
The household segment accounts for the majority of capsule consumption. The shift toward hybrid remote work solidified post-pandemic at-home coffee trends, encouraging consumers to upgrade their domestic kitchen setups. Consumers routinely replicate cafe-style beverages at home using single-serve espresso systems paired with milk frothers, elevating everyday home consumption into a daily indulgence.
The commercial market spans professional offices, luxury hospitality suites, meeting venues, and quick-service dining. In these settings, capsule systems provide rapid preparation, consistent flavor without trained baristas, and zero grounds cleanup. Commercial machines typically feature dedicated, higher-capacity pod designs to handle higher daily volumes and prevent unauthorized home use.
|
Forecast Period |
2026-2033 |
|
Market Size in 2026 |
USD 30.2 billion |
|
Market Size by 2033 |
USD 57.5 billion |
|
Growth Rate from 2026 to 2033 |
8.4% |
|
Base Year |
2025 |
|
Regions Covered |
North America, Europe, Asia-Pacific, South America, Middle East & Africa |
Due to high demand from various consumers around the globe for the quality and convenient products of Nespresso Capsules, much attention is bestowed on this particular market. Segmentation based on geographically located regions North America, Europe, Asia-Pacific, South America, and Middle East & Africa areas further contributes to this global market dynamics in a diversified manner.
North America includes the United States, Canada, and Mexico. All these countries have experienced high growth as a result of increased demand for single-serve coffee products and their convenience. The U.S. is the largest player in this segment due to a robust consumer base and the popularity of premium coffee products.
Europe is the other key region for Nespresso Capsules, consisting of the United Kingdom, Germany, France, Italy, and the Rest of Europe. The European region has an embedded coffee culture, whereby high-quality coffee consumption forms not only a drink but a way of life. Both Germany and France have steadily followed this growth as consumers demand premium and sustainable coffee solutions, while Italy's tradition of great coffee further enhances the market growth within its territory.
A great opportunity has grown in the Nespresso Capsules market as India, China, Japan, South Korea, and the Rest of Asia-Pacific is included under this region called the Asia-Pacific. With rising disposable incomes and an increasing inclination toward modern lifestyles, the demand for convenient coffee options has risen significantly. Countries like China and Japan are leading in this region, driven by urbanization and the growing café culture.
South America includes Brazil, Argentina, and the Rest of South America. Brazil is one of the world's biggest coffee producers, which makes it very important for Nespresso Capsules growth. Consumers in this region have started to embrace single-serve coffee solutions, which leads to steady growth in the market.
The last segment includes the Middle East & Africa, comprising GCC Countries, Egypt, South Africa, and the Rest of the Middle East & Africa. Premium coffee products in the region are gaining popularity with the emergence of an emerging middle class and increasing awareness of single-serve coffee systems, thus growing the market in this region. Each geographical segment of the global Nespresso Capsules market has its own unique trends and opportunities, reflecting the diverse preferences and consumption patterns across regions.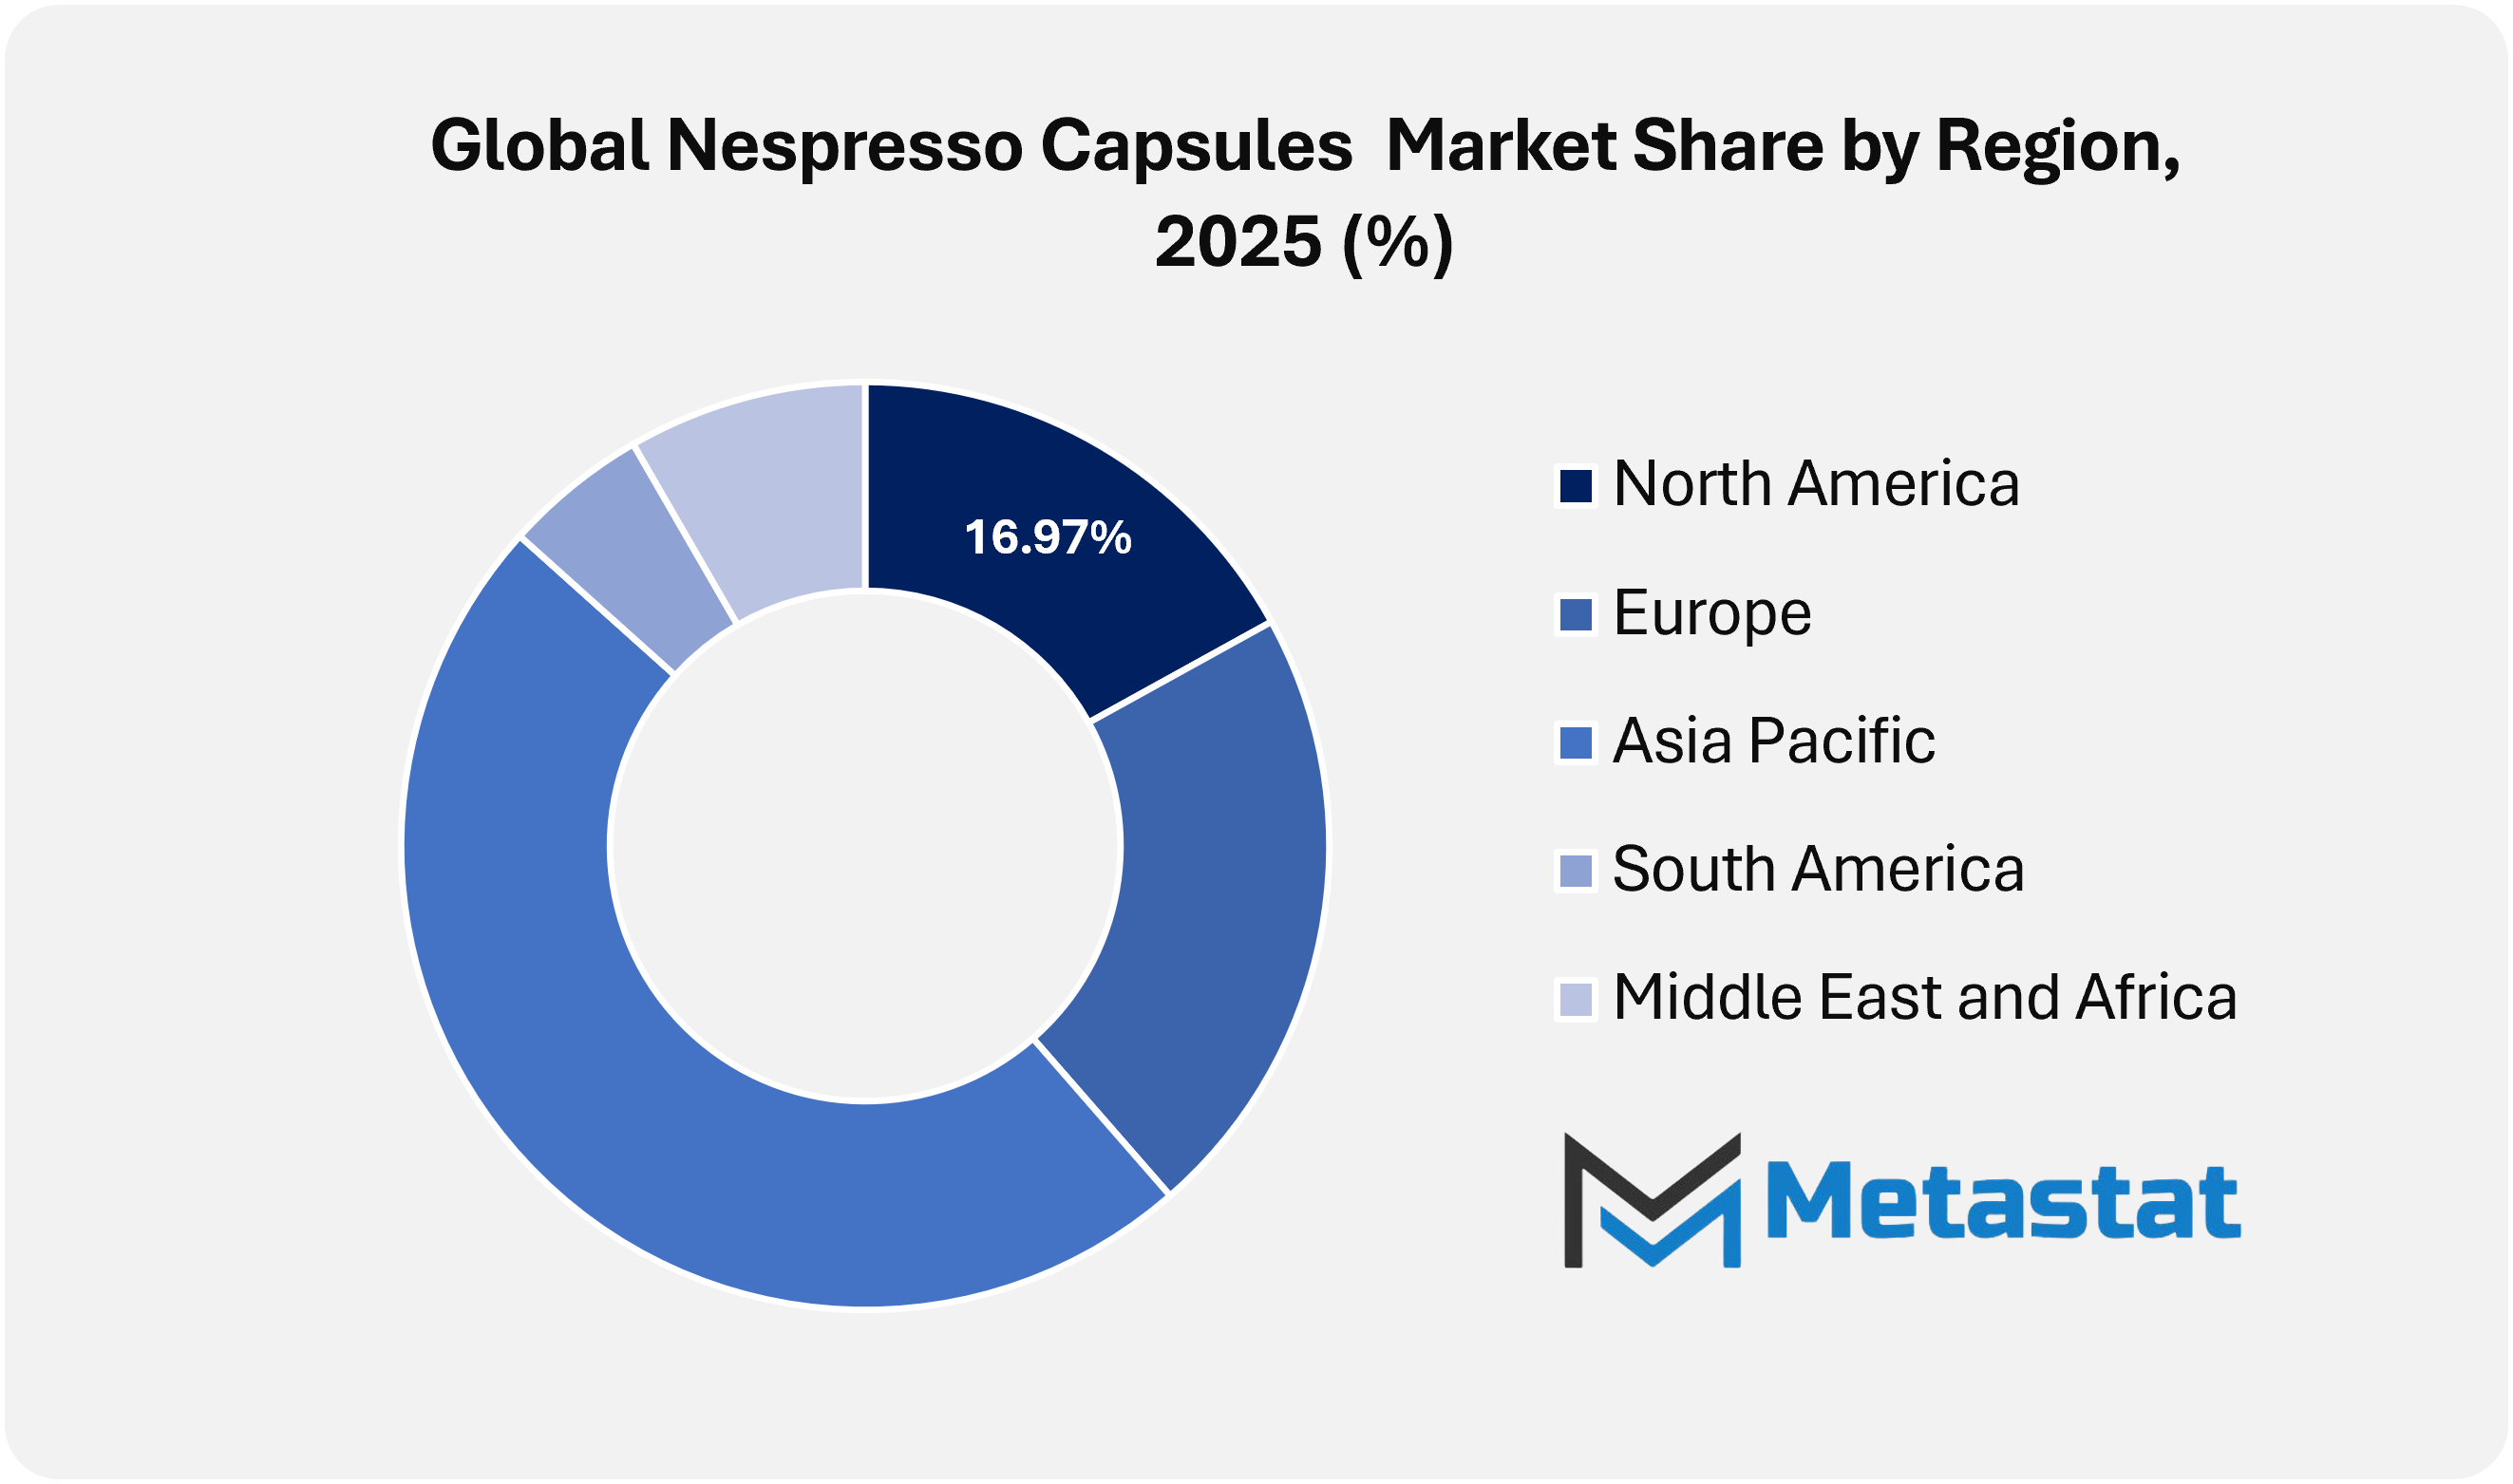
Europe remains the most established and mature market for single-serve coffee systems. Countries like France, Switzerland, Germany, and the United Kingdom exhibit high per-capita capsule consumption. Because European consumers primarily drink espresso and lungo formats, OriginalLine machines and third-party compatible capsules dominate retail shelves. European consumers and regulatory bodies also enforce the world's strictest packaging standards, accelerating the shift toward home-compostable capsules and closed-loop aluminum recovery schemes.
North America is defined by a historical consumer preference for larger, drip-style mugs of coffee rather than short espresso shots. This preference established the region as the key growth engine for VertuoLine capsules. Nestlé Nespresso deployed significant marketing resources in the United States and Canada to educate consumers on Centrifusion technology. Third-party compatible options are less prevalent in the large-cup segment due to Vertuo patent protections, allowing premium proprietary platforms to preserve solid profit margins.
Asia Pacific represents a high-growth frontier driven by rapid urbanization, expanding middle-class demographics, and the swift adoption of Western cafe culture. Markets such as Japan, South Korea, and Australia display sophisticated coffee tastes with an appetite for single-origin coffee and boutique roasters. In emerging coffee markets across China and Southeast Asia, compact capsule machines serve as status symbols in modern urban apartments, offering an accessible entry point to premium espresso brewing.
There is indeed growth in the global market of Nespresso capsules in recent times because people have more and more craving for high quality convenient coffee. It has proved its potential due to consistency of flavor, its convenience, and a luxurious feeling when having the coffee. So many companies try to get themselves in this space by making entry, thus generating tough competition that can offer more variety to customers.
Major players in this market are the well-known names such as Belmoca, Nestlé (Nespresso), Lavazza, Starbucks, and Illycaffè, all of which have contributed to the growth of the market through innovative offerings. These brands have been able to position themselves as leaders by ensuring that their products meet diverse tastes and preferences. For instance, Lavazza and Starbucks are known for their extensive range of blends and strong market presence, while Illycaffè is known for premium quality.
Aside from these big names across the world, there are still other businesses which have impressed a niche target through the consumer. Café Royal and Jacobs Douwe Egberts Pro were focusing on developing thick, smoky flavors in coffee for their targeted coffee drinkers. Caffè Vergnano and L'OR Espresso cater to a highly differentiated flavor portfolio in their own unique capsules. These companies are constantly working to maintain their position by innovating and providing products that appeal to coffee lovers around the world.
The market's diversity has been supported by the contributions of other smaller yet influential players such as Caramelly, Blue Tokai Coffee Roasters, Coffeeza, and Coffee Nirvana. Their distinct approach, typically underpinned by a local source of beans and sustainability, has gained customer loyalty. In particular, Blue Tokai Coffee Roasters, with its artisanal coffee approach, has earned significant popularity; on the other hand, Coffeeza and Coffee Nirvana cater to the market with the perfect combination of quality and convenience.
This competition has led to a wider range of flavors, packaging styles, and price points for premium coffee, making it more accessible. The emphasis on sustainability, including recyclable capsules and eco-friendly practices, is now an important factor for many consumers when choosing their preferred brand.
The Nespresso capsules market will therefore continue growing, with everybody being able to have his or her kind of flavor. Innovation at the top, while newcomers are just perfecting more options, will create the most delicious, tailored experience of coffee drinking by all aficionados worldwide.
Nestlé Nespresso maintains an authoritative position within the global premium single-serve category. Its competitive advantage stems from its closed VertuoLine ecosystem, an extensive global boutique footprint, high brand loyalty, and the high-end appeal of its espresso machine ecosystem. By controlling hardware specifications and Vertuo production, Nespresso protects its premium pricing structure against commoditization.
Global coffee conglomerates such as JDE Peet's, Lavazza, and Starbucks (distributed in pods both via partnerships and standalone lines) hold substantial market share in the third-party compatible space. Alongside these industry giants, retail private labels sold by supermarket chains capture price-sensitive consumers. Private label challengers offer baseline quality at a substantial discount, squeezing margins on standard OriginalLine offerings.
Independent specialty coffee roasters have increasingly entered the capsule segment by partnering with specialized co-packers. Boutique roasters fill a crucial niche by offering specialty-grade, ethically sourced, and micro-lot coffees in compatible formats. Their presence attracts specialty coffee enthusiasts who previously avoided single-serve pods due to quality or freshness concerns.
Between 2023 and 2025, the market saw major commercial rollouts of paper-based and bio-sourced capsules. Nespresso introduced its own line of home-compostable paper-based capsules to run parallel with its aluminum range in key European test markets. This strategic launch responded directly to consumer pushback regarding aluminum packaging waste and local composting habits.
Hardware partnerships expanded as machine manufacturers collaborated with premium coffee brands to bring co-branded brewing equipment to retail shelves. Licensing agreements under the Global Coffee Alliance between Nestlé and Starbucks continued to broaden Starbucks-branded Vertuo and OriginalLine capsule availability across global grocery channels, expanding system penetration in residential kitchens.
Retail footprints underwent strategic updates between 2023 and 2025, with legacy boutiques transitioning into immersive customer experience centers focused on tasting bars, recycling collection, and machine care masterclasses. Concurrently, luxury single-serve platforms expanded into fast-growing emerging markets, including high-end retail hubs across urban centers in India and Southeast Asia.
Find answers to common questions about this report
Nespresso Capsules market was valued at USD 32.7 billion in 2026.
Market is expected to grow at a CAGR of 8.4% during the forecast period.
Nespresso Capsules market is projected to reach USD 57.5 billion by 2033.
Top players operating in the Nespresso Capsules industry includes Belmoca, Nestlé (Nespresso), Lavazza, Starbucks, Illycaffè, Café Royal, etc.
Stringent packaging waste regulations, extended producer responsibility (EPR) mandates, and prospective bans on non-recyclable single-use plastics in jurisdictions like the European Union create significant compliance burdens. Manufacturers must invest heavily in certified compostable materials or establish verifiable collection and recycling systems for aluminum waste.
Europe displays the highest household adoption rates, with single-serve espresso systems firmly entrenched as standard kitchen appliances. North America shows steady adoption centered on multi-serve and large-cup platforms like VertuoLine, while Asia Pacific exhibits accelerating adoption rates among affluent urban households seeking premium at-home coffee convenience.
Compostable and aluminum-free capsules provide an eco-friendly alternative for consumers who find aluminum recycling drop-off systems inconvenient. By allowing users to dispose of coffee pods in organic waste streams, compostable alternatives reduce municipal landfill burden and challenge the sustainability claims of traditional single-serve packaging.
Major brands such as Starbucks, L'OR (JDE Peet's), Lavazza, and supermarket private label challengers are gaining strong traction. They succeed by offering lower price points, utilizing widely available supermarket distribution channels, and providing high-quality aluminum capsules that match the mechanical reliability of original pods.
The rollouts of paper-based home-compostable capsules by major producers and ongoing retail distribution deals under the Global Coffee Alliance between Nestlé and Starbucks have reshaped the landscape. Furthermore, boutique specialty roasters partnering with specialized co-packers have brought high-end specialty coffee into the single-serve capsule segment.
Post-pandemic buying habits accelerated the migration toward online retail platforms and recurring direct-to-consumer (DTC) subscription models for everyday replenishment. Physical brick-and-mortar locations, such as boutique stores and specialty coffee stores, have shifted their purpose toward sensory brand experiences, machine demonstrations, and recycling collection hubs.
Premiumization is primarily driven by light to medium roast single-origin coffee capsules that showcase origin-specific flavor notes, micro-lots, and ethical sourcing certifications. In flavored coffee, naturally derived infusions like bourbon vanilla, roasted hazelnut, and seasonal spiced profiles appeal to consumers looking to replicate specialty cafe beverages at home.
OriginalLine capsules hold a larger total volume share globally, especially in Europe, because their open-source format allows widespread production by third-party brands. VertuoLine capsules experience faster revenue growth in North America and markets favoring large-cup formats, where patent protections prevent generic competition and preserve premium pricing.
Choose Your License
Nespresso Capsules Market
The analysts below cover Food and Beverages research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

LEAD PRINCIPAL ANALYST, PHARMA AND HEALTHCARE
Food and Beverages · Healthcare · Healthcare IT · Medical Devices
Ajay Devgire is the Lead Healthcare Analyst at MetaStat Insight, leading strategic research and market intelligence initiatives across the global healthcare domain.
SENIOR RESEARCH ANALYST
Biotechnology · Food and Beverages · Medical Devices · Packaging
Snehal Pasalkar is a Research Analyst at MetaStat Insight, operating at the intersection of life sciences research, competitive strategy, and market intelligence.
Last Updated: September 2026
When planning edge sensor rollouts across refinery environments, generic IoT reports typically miss the harsh-environment certification bottlenecks. MetaStat Insight gave an objective evaluation of ATEX and Class 1 Division 2 hardware availability, along with realistic five-year maintenance cycle cost projections. The comparison of wireless mesh versus private cellular backhaul helped our team pressure-test network reliability models for remote processing facilities.
In the biological seed treatment space, registration timelines vary drastically between the European Union, Brazil, and North America. The MetaStat Insight research handled these cross-border regulatory barriers with genuine nuance, mapping commercialization pathways alongside historical field adoption rates. The segmentation between microbial strains and biochemical active ingredients was particularly well structured.
Our team was tracking whether regional recycling infrastructure could realistically absorb the growing volume of lithium iron phosphate batteries over the next decade. The report did a solid job separating announced hydrometallurgical plant capacity from active, permitted operational throughput. That distinction made the feedstock availability projections and regional recovery rate models far more credible than standard commercial overviews.
Explore related market intelligence reports worth reading alongside this one.