
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Airborne SATCOM System Market Size, Share, By Component (Antennas, Transceivers and RF Units, Modems and Routers, Radomes), By Platform (Fixed-Wing Aircraft, Rotary-Wing Aircraft, Unmanned Aerial Vehicles), By Frequency Band (Ku-Band, Ka-Band, L-Band, X-Band, UHF, Multi-Band), By Installation Type (New Installation, Retrofit), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-2446
Published
November, 2026
Pages
289 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
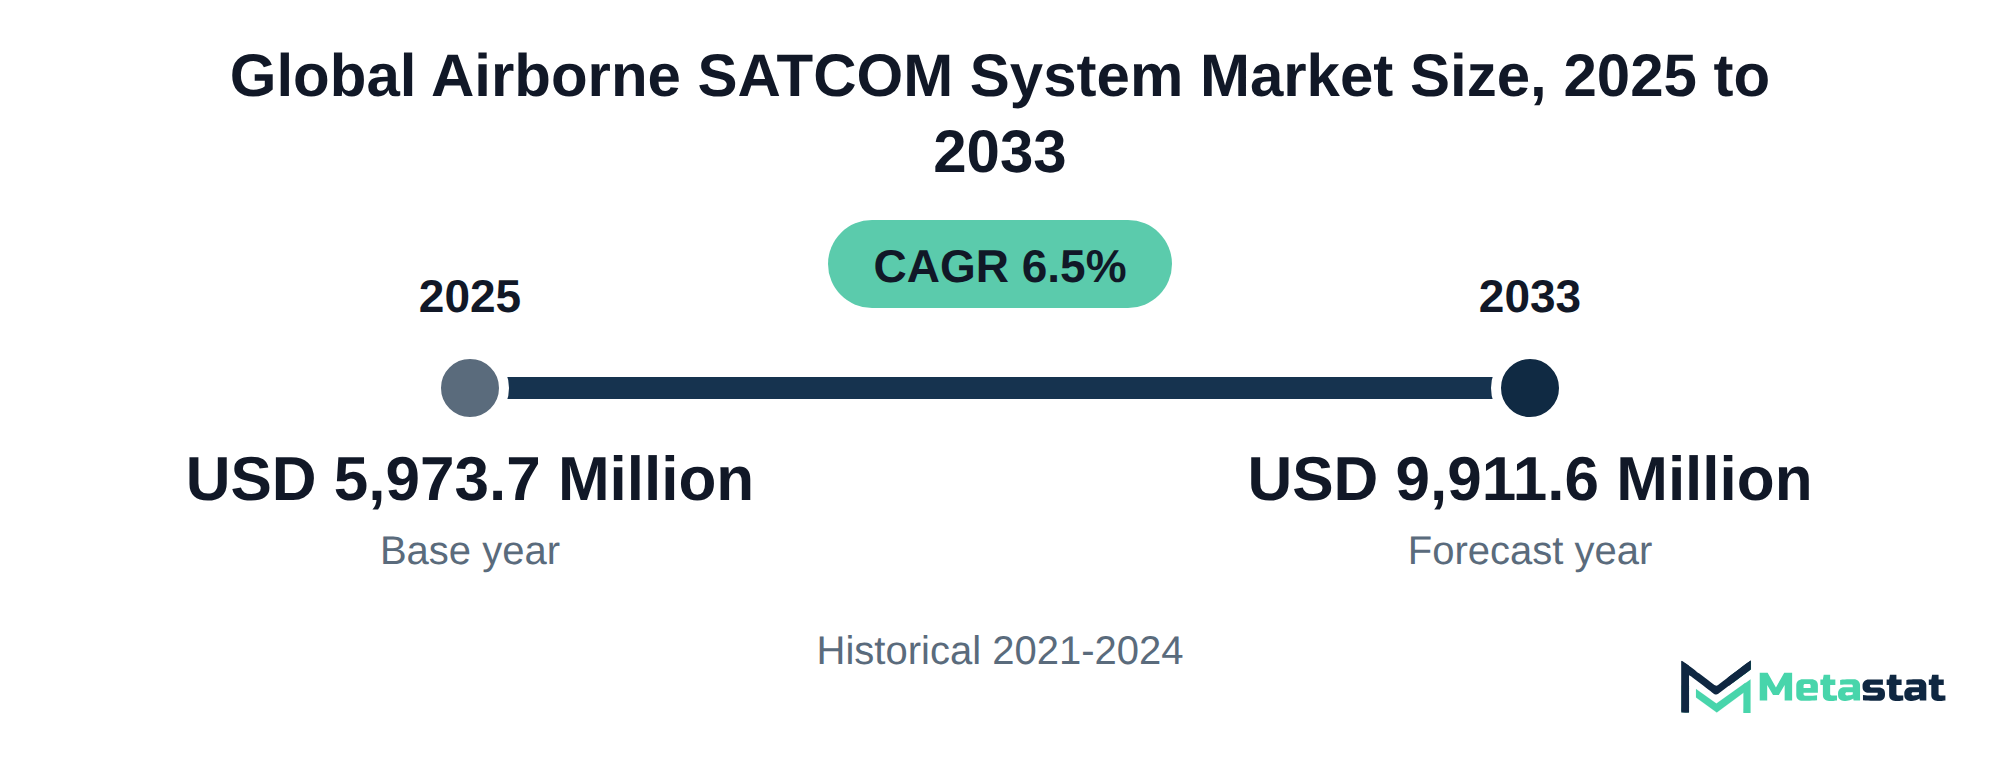
Market Valuation: Valued at $5,973.7 Million in 2025, projected to reach $9,911.6 Million by 2033 at a 6.5% CAGR.
Dominant Segment: Fixed-wing aircraft lead the Airborne SATCOM System market, driven by increasing demand for enhanced data transmission and connectivity in military and commercial aviation.
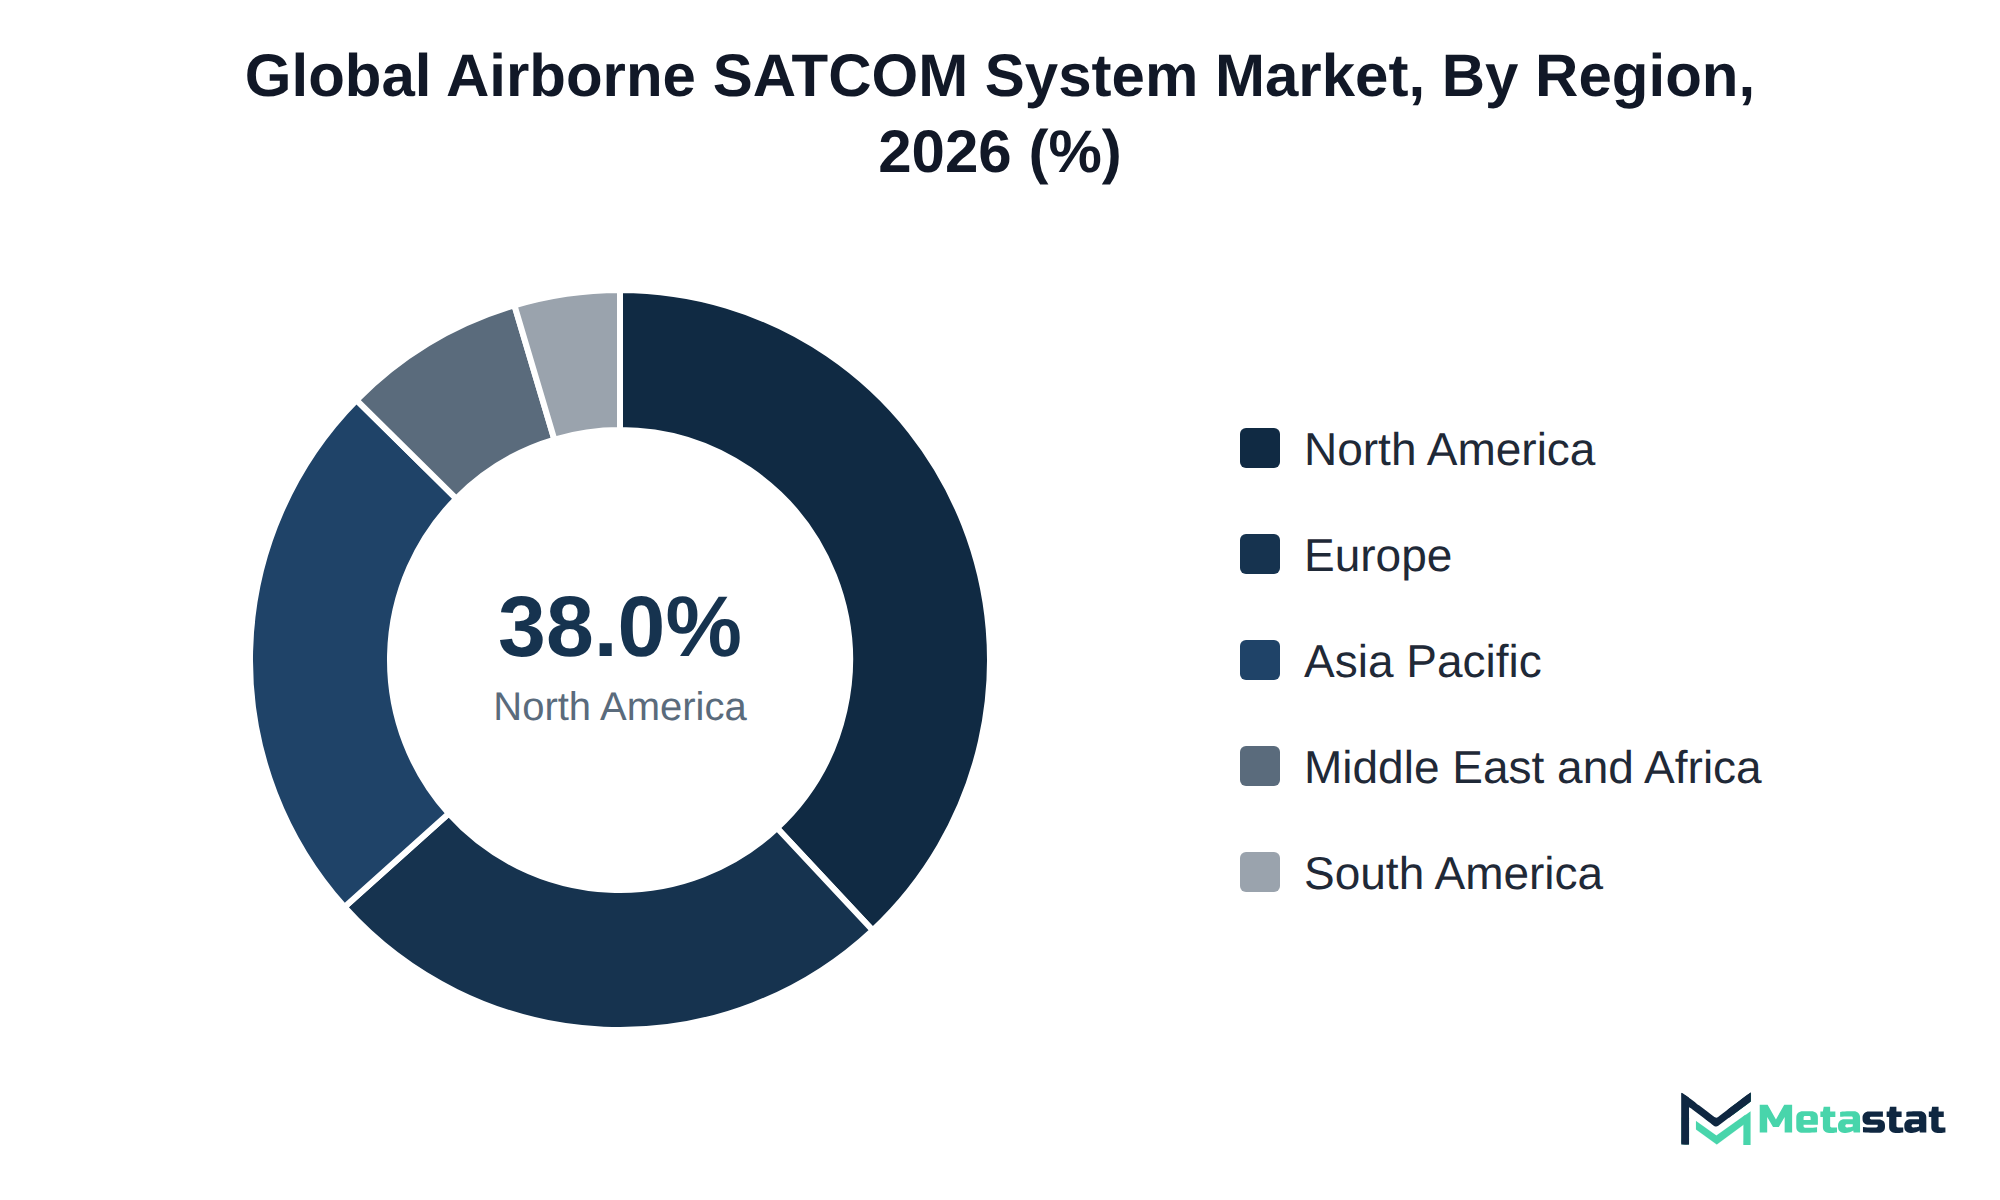
Geographic Lead: North America holds the largest market share at 38.0% in 2025, supported by significant investments in defense and aerospace technologies.
What's Inside: The report provides a comprehensive analysis of market segmentation by component, platform, frequency band, and installation type, along with competitive coverage and forecasts through 2033.
Growth Drivers: The expansion of unmanned aerial vehicles (UAVs) and the rising adoption of advanced communication technologies are key factors propelling market growth.
Pricing Models: Diverse pricing strategies, including fixed pricing contracts and usage-based models, are emerging as buyers seek flexibility and predictability in their investments.
Choose Your License
Global Airborne SATCOM System Market
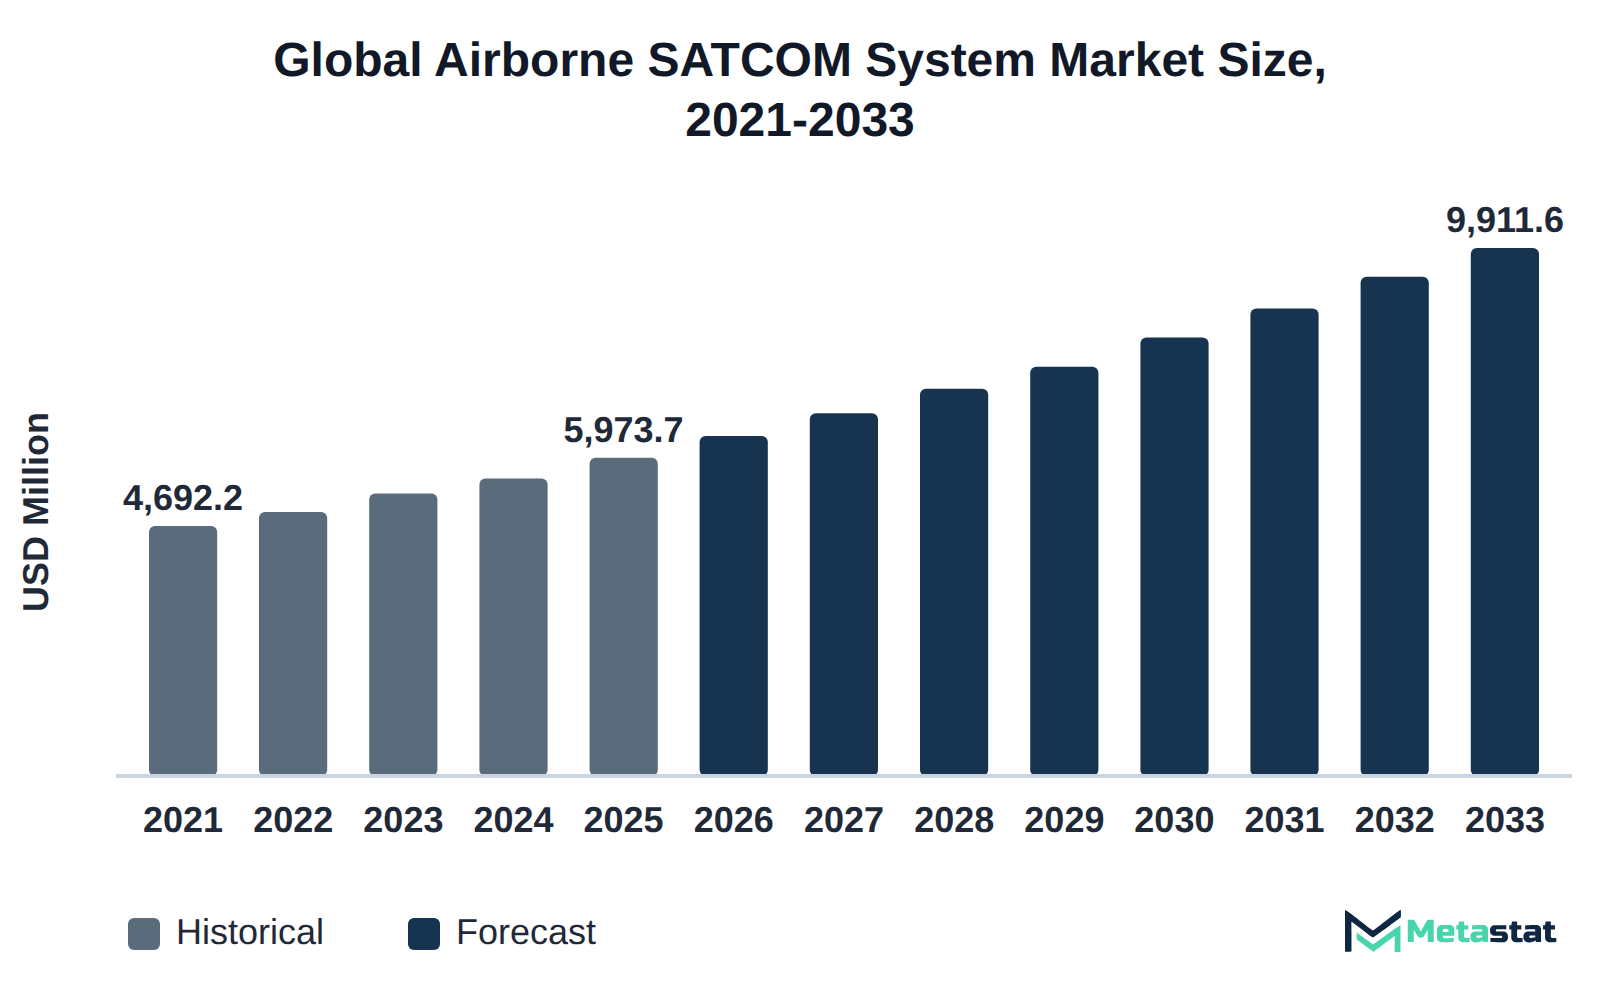
The global Airborne SATCOM System market was valued at USD 5,973.7 million in 2025 and is projected to reach USD 9,911.6 million by 2033, growing at a CAGR of 6.5% over the forecast period.
The Airborne SATCOM System market encompasses a range of technologies designed to provide satellite communication for airborne platforms. Buyers invest in these systems to enhance communication capabilities, improve operational effectiveness, and ensure reliable connectivity during missions. The market includes components including antennas, transceivers, and modems, which play a critical role in enabling communication across various aviation applications.
Growth in the Airborne SATCOM System market is driven by rising demand for advanced communication systems in military and commercial aviation. Fixed-wing aircraft represent the segment with the most value, supported by a rising need for enhanced data transmission and connectivity. North America holds 38.0% of the market in 2025, with the US leading in 2026. The region benefits from significant investments in defense and aerospace technologies, contributing to its dominance in the market.
One main growth driver is the expansion of unmanned aerial vehicles (UAVs), which require robust communication solutions to operate effectively in various environments. The integration of advanced satellite communication systems into these platforms enhances their operational capabilities, making them more attractive to military and commercial operators. This trend reflects a broader shift driven by digitalization and automation within the aviation sector.
The Airborne SATCOM System market covers various components, platforms, frequency bands, and installation types essential for facilitating reliable communication in airborne applications. Spending in this market arises from the increasing demand for high-speed data transmission in military and commercial aviation sectors, where real-time communication significantly enhances operational effectiveness and situational awareness. Buyers prioritize advanced technologies that ensure secure and uninterrupted connectivity, thereby justifying their investment in these systems.
Growth in the market is driven by the rising adoption of airborne platforms, particularly fixed-wing aircraft, which represent the segment with the most substantial value. This region benefits from significant investments in defense and aerospace, creating a conducive environment for advancements in satellite communication technology.
The increasing demand for Ka-Band frequencies, known for providing higher bandwidth and improved data rates, further boosts market expansion. As industries evolve, the focus on enhancing communication capabilities on airborne platforms intensifies, supporting the overall growth trajectory. The Airborne SATCOM System market reflects dynamic technological advancements and shifting demands across various sectors.
The rise of multi-orbit aircraft connectivity significantly influences the adoption of electronically steered antennas in the Airborne SATCOM System market. This technology allows communication across different satellite networks, enhancing data transmission capabilities and operational flexibility. Antennas designed for electronically steered systems enable tracking multiple satellites simultaneously, resulting in uninterrupted connectivity even during flight. This advancement meets rising demand for communication solutions in the aviation sector.
In the forecast period, antennas are projected to grow from USD 1,882.3 million in 2026 to USD 3,232.2 million by 2033, reflecting a compound annual growth rate of 8%. The increasing reliance on high-speed data services in both commercial and military aviation drives this trend, allowing operators to manage operations more efficiently and improve passenger experiences. Enhanced connectivity becomes essential for airlines and defense contractors striving to meet modern communication requirements.
The adoption of electronically steered antennas contributes to operational efficiencies, reducing downtime and maintenance needs associated with traditional systems. While the market evolves, this technology helps companies strengthen their competitive position in the Airborne SATCOM System market. This shift towards advanced connectivity solutions signifies a critical transition for the industry, highlighting the importance of investing in innovative technologies that support future growth.
In the Airborne SATCOM System market, buyers increasingly favor Ka-Band terminals for their enhanced broadband capacity, particularly within airline and defense fleets. These terminals facilitate high-speed data transmission, essential for modern aviation and military operations. The growing demand for such capabilities has led to the establishment of diverse pricing models. Fixed pricing contracts dominate, providing predictability for long-term budgeting, while usage-based models offer flexibility for clients looking to scale services according to operational needs.
Specifically, the adoption of Ka-Band technology is expected to reach USD 3,553.3 million by 2033, reflecting a compound annual growth rate of 9.3%. This growth influences pricing strategies, encouraging suppliers to offer competitive rates to capture market share. The ability to bundle installation and service costs into comprehensive solutions enhances customer appeal, effectively lowering entry barriers for potential clients. Combined with the benefits of Ka-Band terminals, this pricing gives buyers operational efficiencies and a stronger return on investment.
Low-SWaP (low size, weight, and power) SATCOM solutions provide essential support for long-range control of unmanned aerial vehicles (UAVs). The growing reliance on UAVs for various applications, including surveillance, reconnaissance, and military operations, drives demand for efficient communication systems. These systems facilitate real-time data transmission and command control, ensuring operational effectiveness in mission-critical scenarios. This growth highlights the increasing focus on advanced communication technologies.
UAV manufacturers prioritize Low-SWaP SATCOM systems to enhance the capabilities of their platforms while maintaining performance and efficiency. Lightweight and compact systems reduce aircraft load and improve fuel efficiency, contributing to longer flight durations and extended operational ranges. Military and commercial applications for UAVs expand, driving the demand for reliable communication links that enhance overall mission success. Meeting the specific needs of UAV operators gives suppliers a competitive advantage.
Airlines often face a critical decision when integrating SATCOM systems: whether to opt for line-fit or retrofit solutions. Line-fit installations occur during the manufacturing phase, providing an opportunity for effective integration within the aircraft’s design. In contrast, retrofit installations are applied to existing aircraft, prolonging the operational lifespan of older models while enhancing their communication capabilities.
The Airborne SATCOM System market demonstrates significant investment in both installation types, reflecting the strategic choices airlines make. For instance, new installations are projected to reach USD 4,882.5 million by 2033, highlighting airlines' commitment to investing in modern equipment. This investment facilitates advanced functionalities including high-speed data transmission and connectivity, which are essential for maintaining competitive service offerings.
The choice between line-fit and retrofit solutions influences operational efficiency and service quality. Airlines that strategically opt for line-fit installations during new aircraft purchases capitalize on advancements in SATCOM technologies, while those choosing retrofits enhance the capabilities of their current fleets, ensuring that they meet evolving customer demands and regulatory requirements.
Growth in military spending significantly influences demand for advanced airborne communication systems. Defense agencies prioritize enhanced connectivity to support operational effectiveness and situational awareness. This shift towards modernization results in increased investment in airborne SATCOM solutions, with military buyers seeking capabilities that improve communication reliability and performance. The global defense budget is projected to rise, with North America accounting for 38% of the market share in 2025, reflecting a strong emphasis on upgrading military technologies. Enhanced connectivity solutions enable improved coordination in mission-critical environments, driving demand for advanced systems. The market experiences growth driven by these military investments, influencing both volume and price trends.
Adoption of advanced antenna technologies drives innovation within the market. The development of electronically steered antennas (ESAs) enhances connectivity options for various airborne platforms, including fixed-wing and rotary-wing aircraft. These systems allow for improved bandwidth and more efficient satellite communication, reflecting a strong demand from military and commercial sectors seeking reliable communication solutions.
Technological advancements in antenna design, including phased-array antennas, facilitate rapid beam steering, enabling effective communication across multiple satellites. This flexibility appeals to operators aiming to maintain connectivity in diverse operational environments. Enhanced performance characteristics support operational efficiency, thus lowering potential costs associated with communication downtime.
The increasing deployment of unmanned aerial vehicles (UAVs) further fuels innovation in antenna technologies. The need for lightweight, compact systems aligns with market trends emphasizing low size, weight, and power (Low-SWaP) requirements. This trend drives the growth of the airborne SATCOM System market by enabling integration into various platforms, thereby expanding operational capabilities.
Pressure from pricing impacts demand in the airborne communication sector. High costs associated with advanced technologies deter several buyers, particularly in the commercial aviation segment. Airlines face challenges in balancing budget constraints with the need for enhanced communication capabilities. This situation leads to slower uptake of new systems and smaller orders as firms prioritize cost-effective solutions. Reluctance to invest in retrofitting existing aircraft results in delayed upgrades and replacements, further stalling market momentum. While the airborne SATCOM System market is poised for growth, pricing pressure remains a significant barrier for many potential buyers seeking to adopt advanced solutions.
Increasing costs of inputs create significant challenges for suppliers in the Airborne SATCOM System market. Price volatility in raw materials and technology components directly impacts profit margins. Suppliers face pressure to maintain competitive pricing while ensuring quality, leading to tighter financial constraints. This pressure influences the ability to invest in research and development, hampering innovation in product offerings.
To address these challenges, suppliers are exploring strategic partnerships and sourcing alternatives to mitigate input costs. Collaborations with component manufacturers enhance bargaining power and create cost-effective solutions. Investment in streamlined production processes aims to optimize operational efficiency and reduce dependence on single-source suppliers. These initiatives reflect a proactive approach to maintaining competitiveness amid market pressures.
The rotary-wing aircraft segment presents a significant growth opportunity within the market, driven by increasing demand for versatile airborne communication solutions. This segment is projected to achieve a compound annual growth rate (CAGR) of 5.4% through 2033. Rising utilization of rotary-wing aircraft in both military and commercial applications supports this trend, reflecting expanding operational requirements for real-time communication and data transfer.
Investments in this segment focus on advanced transceiver and RF unit technologies, enhancing connectivity capabilities for rotary-wing platforms. Operators seek robust communication systems to support complex missions, driving demand for these advanced airborne solutions and positioning the rotary-wing aircraft segment as a key area for growth in the Airborne SATCOM System market.
The Global Airborne SATCOM System market is segmented based on Component, Platform, Frequency Band, and Installation Type.
This segment serves military and commercial aviation, enabling reliable satellite communications on a range of airborne platforms. The increasing focus on enhancing communication capabilities drives demand for advanced antenna technologies, particularly in environments requiring high data transmission rates. Compared to other segments, including Transceivers and RF Units, which exhibit a CAGR of 5.3%, antennas demonstrate a more rapid growth trajectory. Distinct technological advancements in antennas contribute to competitive pricing and appeal to buyers in both defense and commercial sectors, emphasizing their critical role in modern airborne communication systems.
Transceivers and RF Units segment is estimated to reach USD 2,604.8 million by 2033, at a CAGR of 5.3% during the forecast period. This segment encompasses essential equipment for converting and managing radio frequency signals in airborne communication applications. Military and commercial aviation sectors employ these units to enhance connectivity and ensure reliable real-time data transmission. The increasing demand for advanced communication systems drives investments in this segment, particularly within military operations that require high-data-rate capabilities. Compared to other components, including antennas, the growth of transceivers and RF units remains stable, with a CAGR of 5.3%, indicating a steady preference among buyers for established technologies. This segment, characterized by its critical role in signal processing, differs from antennas, which experience faster growth due to technological advancements including electronically steered antennas. Overall, the market reflects a balance between technological progress and the need for reliability in airborne communications.
Modems and Routers segment is expected to reach USD 2,732.6 million by 2033. These components transmit data through satellite communication systems for military and commercial aviation users. Increasing demand for high-bandwidth connectivity drives this segment, particularly due to the growing reliance on real-time data transmission for operational efficiency. In contrast to other components like antennas, which exhibit a higher growth rate with a CAGR of 8%, the growth for Modems and Routers stands at a CAGR of 5.3%. This segment's growth reflects ongoing technological advancements in digital communication and the need for enhanced performance, positioning it uniquely within the broader Airborne SATCOM System market.
Radomes segment is projected to grow at a CAGR of 3.1% during the forecast period. This segment consists of protective covers for antennas that shield them from environmental factors while ensuring signal performance. Users of radomes include military and commercial aviation sectors, where reliable communication is crucial. Demand for lightweight, durable radomes drives growth, owing to advancements in aerospace materials and design that enhance performance. Compared to other components, radomes experience slower growth, influenced by the steady demand for existing designs rather than rapid technological shifts. Despite this, their essential role in ensuring optimal antenna function under varying conditions assures continued investment. In 2033, the radomes segment contributes to the overall market, highlighting its significance in maintaining effective airborne communication systems.
Others, including antenna controllers, power supplies, and installation kits, support the functionality of airborne SATCOM systems. These components are essential for ensuring the proper operation and integration of satellite communication systems within various airborne platforms including fixed-wing aircraft and unmanned aerial vehicles. Demand for this sub-segment is influenced by the increasing focus on enhancing connectivity and communication reliability in military and commercial aviation sectors. The growing complexity of aerial operations drives the need for integrated solutions that provide reliable connectivity. Compared to other components like antennas and modems, this sub-segment typically experiences slower growth due to its niche application and specific buyer base. The emphasis on advanced technology adoption in the airborne SATCOM System market supports growth in this area, driven by stakeholders seeking comprehensive solutions that include all necessary supporting elements.
Fixed-Wing Aircraft segment is valued at USD 3,404.8 million in 2026 and is projected to reach USD 4,919.1 million by 2033, at a CAGR of 5.4% during the forecast period. This segment primarily serves military and commercial aviation sectors, providing critical communication capabilities for operations including surveillance, reconnaissance, and passenger connectivity. Demand for this segment is driven by increasing requirements for secure and reliable communication systems in various aviation missions. Compared to other platforms including rotary-wing aircraft and unmanned aerial vehicles, the fixed-wing segment shows a distinct growth trajectory, reflecting a higher value and sustained investments in advanced technologies. Enhanced bandwidth and connectivity solutions significantly influence customer choices, distinguishing fixed-wing platforms through their operational versatility and ability to support diverse missions across the market.
Rotary-Wing Aircraft segment is estimated to reach USD 2,392.7 million by 2033, at a CAGR of 5.4% during the forecast period. This segment serves primarily military and commercial aviation sectors, focusing on reconnaissance, transport, and emergency response operations. Technological advancements in lightweight materials and communication systems drive significant growth in this segment, owing to operators seeking improved performance and reliability. The higher operational flexibility of rotary-wing aircraft compared to fixed-wing platforms attracts various buyers, including government and private entities. With a focus on enhancing connectivity in challenging environments, the rotary-wing segment's growth trajectory remains robust, distinguishing it from other segments, including Fixed-Wing Aircraft, which has a different demand profile and growth rate. The market continues to evolve, addressing the increasing requirements for integrated communication solutions in aviation.
Unmanned Aerial Vehicles segment is expected to reach USD 2,599.8 million by 2033. This segment finds extensive applications in military surveillance, reconnaissance, and commercial operations, attracting buyers from defense and commercial sectors. The growing need for advanced surveillance and reconnaissance capabilities drives demand for these systems. Compared to other platforms, this segment experiences unique growth dynamics, influenced by rapid technological advancements and increasing military investments. The CAGR for this segment aligns with that of rotary-wing aircraft at 5.4%, while the pricing strategy remains competitive, ensuring broader accessibility. The focus on enhanced capabilities, including autonomous operations and real-time data transmission, distinguishes this segment from fixed-wing aircraft. Anticipated advancements in technology and increasing defense budgets are projected to enhance the appeal of unmanned aerial vehicles within the Airborne SATCOM System market.
Ku-Band segment is valued at USD 2,336.6 million in 2026 and is projected to reach USD 3,136 million by 2033, at a CAGR of 4.3% during the forecast period. This frequency band supports military and commercial aviation, providing reliable communications for both voice and data transmission. Demand for Ku-Band systems arises primarily from the need for consistent connectivity during flight operations. The segment stands out from others in its group due to its relatively stable growth compared to Ka-Band, which experiences a higher CAGR of 9.3%. The established infrastructure and widespread use of Ku-Band by numerous buyers, including government and defense agencies, contribute to its sustained market position. Ongoing advancements in satellite technology enhance the segment's capabilities, further driving adoption across multiple platforms.
This segment provides enhanced data transmission capabilities, making it ideal for military and commercial applications that require high-throughput satellite communication. Demand for Ka-Band systems is largely driven by advancements in satellite technology, enabling faster and more reliable connections. In comparison to other frequency bands, Ka-Band shows a higher growth trajectory, reflecting growing interest from sectors including government, aviation, and telecommunications. Growing adoption of Ka-Band technology matches rising demand for efficient, high-capacity communication systems, making it a key player in the Airborne SATCOM System market.
L-Band segment is expected to reach USD 1,425.3 million by 2033. This frequency band serves critical applications in airborne communication systems, particularly for military and aviation purposes. Demand for L-Band technology is primarily driven by its ability to offer reliable communication in various operational environments, making it a preferred choice for defense and emergency services. Compared to other frequency bands, including Ku-Band and Ka-Band, L-Band experiences slower growth, attributed to lower data transmission rates that impact adoption among commercial users. The market benefits from regulatory support for enhanced communication capabilities, ensuring that L-Band continues to fulfill essential communication needs where cost-effectiveness and reliability are significant.
X-Band segment is projected to grow at a CAGR of 5.7% during the forecast period. This frequency band is primarily applied in military applications, providing secure and reliable communication for various airborne platforms. The increasing focus on defense capabilities drives significant demand within this segment, particularly from government and military entities. Compared to other frequency bands, X-Band operates at a lower frequency, offering advantages in terms of signal penetration and resistance to adverse weather conditions, leading to consistent performance in demanding environments. However, competition from higher frequency bands, including Ka-Band, which offers higher data rates, poses a challenge for X-Band growth. Market dynamics indicate a continued reliance on X-Band for critical communications in military operations, ensuring its relevance in the evolving landscape of airborne SATCOM systems.
UHF operates within the frequency band of airborne communication systems, catering primarily to military applications that require reliable and secure communication over various distances. This segment facilitates communication between aircraft and ground stations, ensuring critical data exchange during operations. Demand for UHF systems is driven by the increasing need for secure military communications, particularly in conflict zones where traditional communication methods face challenges. Compared to other frequency bands, UHF typically offers lower costs and broader coverage, making it attractive for military organizations focused on budget optimization. However, this segment experiences slower growth relative to others, including the Ka-Band, which benefits from higher data rates and advanced applications. The Airborne SATCOM System market is expected to expand, reflecting the strategic importance of UHF in enhancing operational capabilities for defense forces.
Multi-Band operates as an advanced frequency band option, supporting diverse communication needs in airborne platforms. Primarily used by military and commercial aviation sectors, this frequency band enhances connectivity and ensures reliable communication links during operations. Demand for Multi-Band is driven by the increasing requirement for versatile communication solutions, particularly in environments necessitating transitions between various frequency bands. Compared to other frequency bands like Ku-Band and Ka-Band, Multi-Band offers unique advantages in adaptability and performance, catering to a broader range of operational scenarios. This flexibility makes it a preferred choice for users who need resilient communication in changing conditions. The growing adoption of unmanned aerial vehicles further stimulates interest in Multi-Band technology, highlighting its strategic importance in the Airborne SATCOM System market.
S-Band and Q/V-Band are critical frequency bands in airborne SATCOM systems. Military and commercial aviation sectors leverage these frequencies for secure communication and data transfer. Demand for enhanced bandwidth and resilient connectivity drives interest in this segment, particularly in defense and surveillance applications. The adoption of advanced technologies and the need for reliable communication in challenging environments contribute to its growth. Compared to Ku-Band and Ka-Band, which experience rapid growth, S-Band and Q/V-Band face competition from higher frequency bands that offer greater data capacity. Buyers often choose these bands when specific operational requirements dictate lower interference and better signal propagation. This frequency band supports niche applications that require reliable connectivity without the constraints of other frequency bands.
New Installation segment is valued at USD 3,322.1 million in 2026 and is projected to reach USD 4,882.5 million by 2033, at a CAGR of 5.7% during the forecast period. This segment supplies the infrastructure for new airborne satellite communication systems in military and commercial aviation. Demand increases primarily due to rising military and civilian applications that require reliable, high-speed connectivity. The New Installation segment differentiates itself from retrofit installations, which involve upgrading existing systems, by focusing on initial setups that address the latest technological advancements. This segment's growth trajectory, driven by the need for modern systems, supports overall expansion in the market, presenting opportunities for companies to enhance their portfolios and capture larger shares of emerging markets.
Retrofit segment is estimated to reach USD 5029.2 million by 2033, at a CAGR of 7.4% during the forecast period. This segment involves upgrading and enhancing existing airborne SATCOM systems to improve performance and extend operational life. Military organizations and commercial aviation sectors primarily use retrofit solutions to address evolving communication needs. Growing demands for enhanced data transmission capabilities and integration of advanced technologies drive the retrofit segment. Compared to new installations, the retrofit segment exhibits a faster growth trajectory, attributed to budget constraints and the preference for upgrading existing systems instead of starting from scratch. This strategic approach allows operators to leverage existing infrastructure while benefiting from advanced technology solutions, positioning the segment for substantial expansion in the market.
Based on geography, the Global Airborne SATCOM System market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Demand within the North American Airborne SATCOM System market receives significant attention due to military applications and commercial aviation requirements. The presence of advanced defense systems in the United States, Canada, and Mexico drives investment in satellite communication technology. Noteworthy infrastructure projects, including modernization initiatives for air traffic management, enhance connectivity and operational efficiency. Increasing emphasis on secure communication channels in military operations supports substantial growth. North America is projected to reach USD 3,530.5 million by the end of 2033, representing a 38% share of the global market in 2025. This strong demand signals an evolving landscape where innovation and investment play vital roles.
The European market for airborne SATCOM systems demonstrates significant growth potential, driven by increasing demand from defense and commercial aviation sectors. Countries including Germany and France prioritize advanced communication technologies to enhance military operations and support civil aviation requirements. Investment in satellite infrastructure strengthens connectivity across the region, contributing to the market's growth. The UK and Italy continue to adopt sophisticated systems to meet operational demands, reflecting advancements in aerospace capabilities. The share of Europe in the global market reached 25.3% in 2025, highlighting its importance within the industry. Regulatory frameworks and technological innovations further influence market dynamics, creating opportunities for new entrants while existing players adapt to evolving customer needs.
The Asia-Pacific region stands out due to increasing investments in defense and commercial aviation, driving demand for advanced communication systems. Countries including China and India focus on enhancing their military capabilities, leading to a greater emphasis on reliable airborne SATCOM systems. Japan and South Korea prioritize modernization efforts in their aerospace sectors, further contributing to market growth. Infrastructure developments in Australia and Southeast Asia support the deployment of these systems, creating a favorable environment for new installations. The market in this region is expected to account for 24.0% of the global share in 2025, reflecting robust demand from both military and commercial applications. Strategic partnerships among regional players enhance competitive positioning, driving innovation and technological advancements in the airborne SATCOM system market.
The South American market demonstrates distinct characteristics driven by defense and commercial aviation sectors in Brazil and Argentina. Significant investment in military modernization programs supports demand for advanced communication systems. The region's share of the global Airborne SATCOM System market reached 4.6% in 2025, reflecting growing interest in reliable satellite communication solutions. Infrastructure development within air transport enhances operational capabilities, promoting the adoption of airborne systems. The market for airborne SATCOM systems is projected to experience further expansion, fueled by modernization efforts and increasing connectivity requirements across the region.
In the Middle East and Africa, the Airborne SATCOM System market is driven mainly by military and defense applications. Countries including Saudi Arabia and the UAE focus heavily on enhancing their aerial communication capabilities, supported by increasing defense budgets. The need for reliable and secure communication systems among military operations remains a strong demand driver. South Africa, with its growing military modernization efforts, contributes to the market's expansion. The region's share of the global market was 8.0% in 2025, reflecting a commitment to upgrading aerial communication infrastructure. Innovations in technology and a focus on satellite communication solutions further enhance the market's growth prospects.
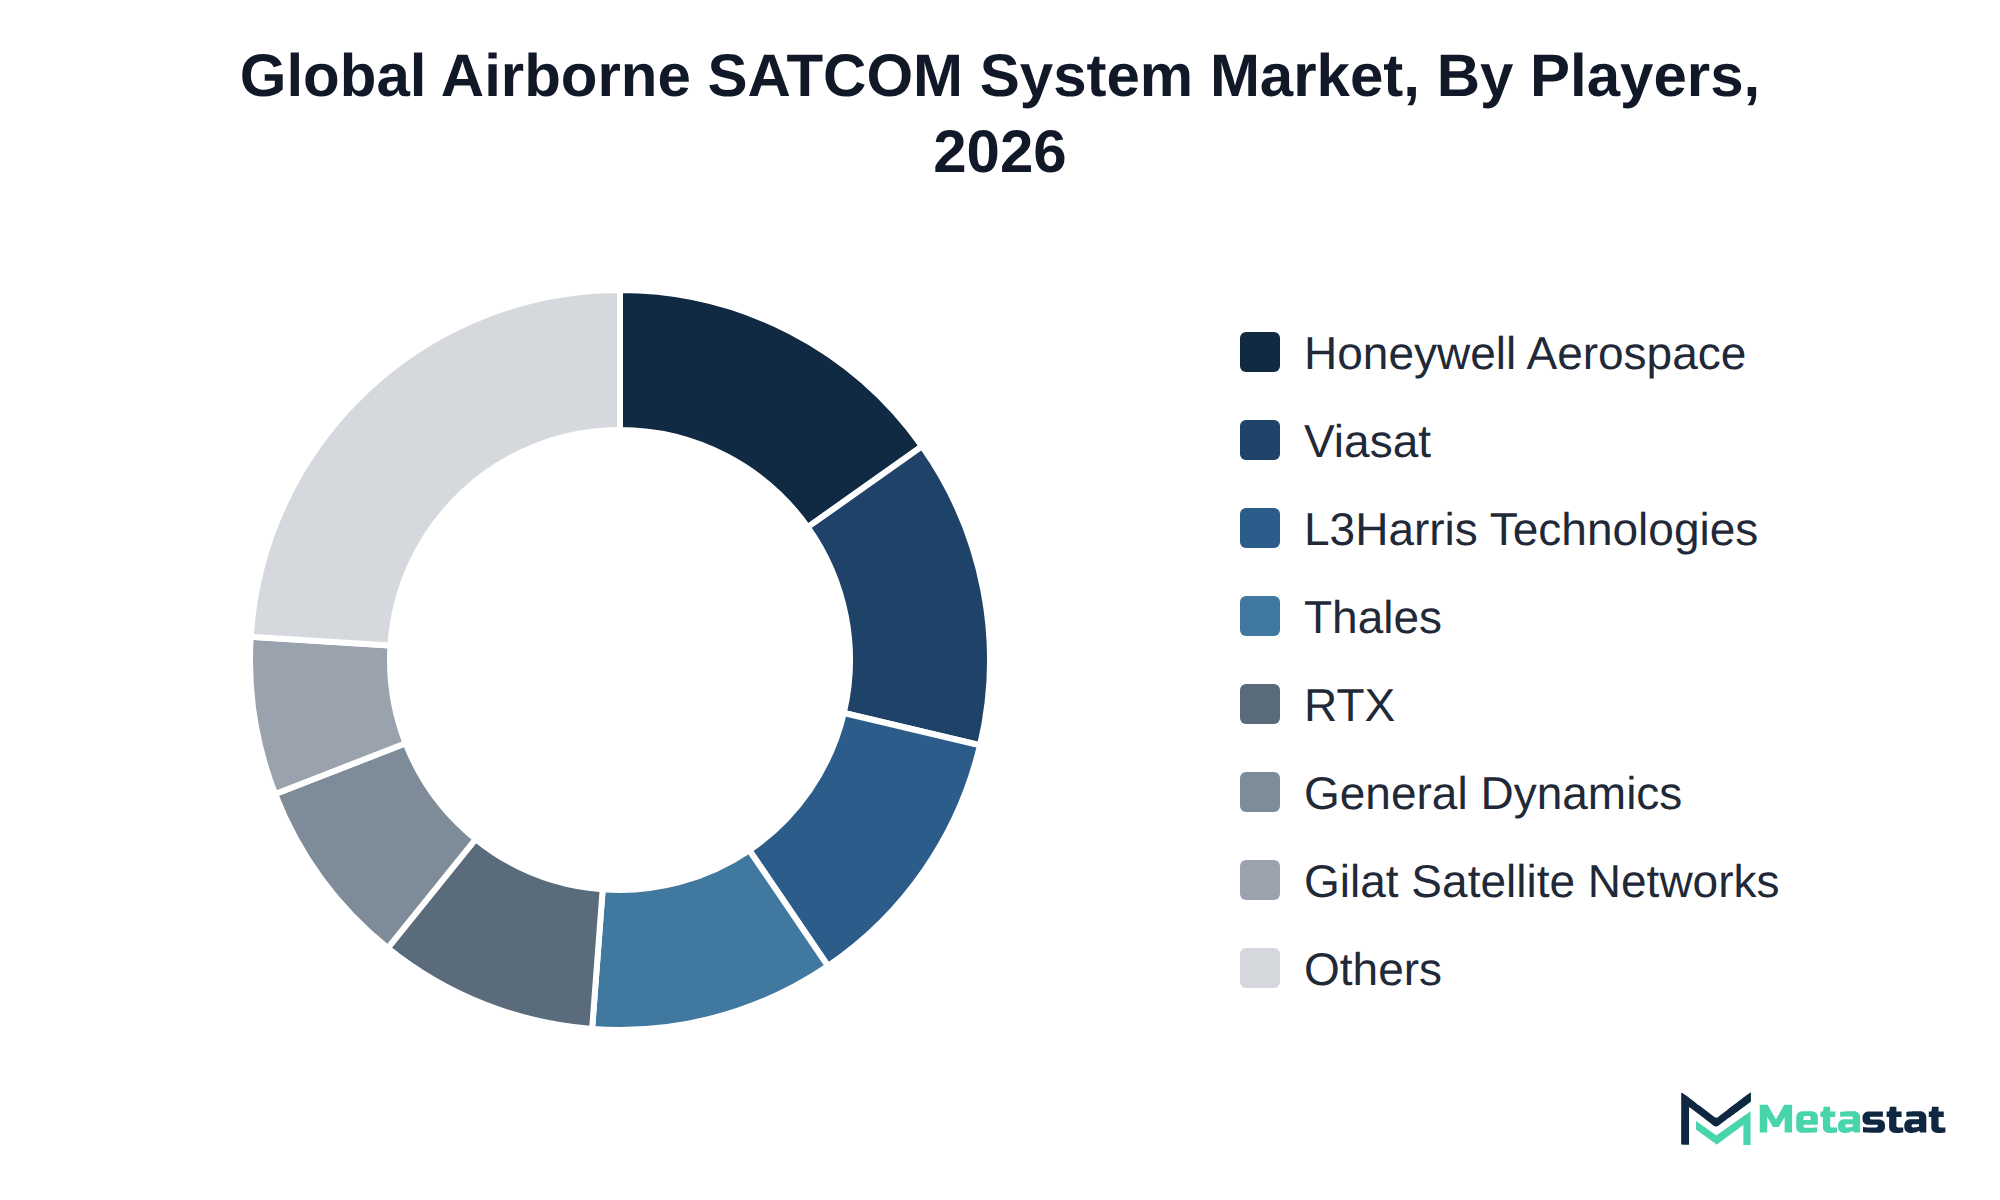
Competitive dynamics in the Airborne SATCOM System market reflect varied strategies among key players. Companies focus on product differentiation, emphasizing advanced technology integration and system capabilities. For example, Honeywell Aerospace Inc. emphasizes innovation in antenna technologies, while RTX Corporation prioritizes secure and reliable communication solutions. Thales S.A. maintains a strong portfolio in both defense and civil aviation applications.
Buyers in the market prioritize factors including price, certification, and customization options when selecting SATCOM systems. System performance and integration with existing platforms significantly influence purchasing decisions. Viasat, Inc. and L3Harris Technologies, Inc. focus on providing tailored solutions that meet specific customer requirements, enhancing their appeal in a competitive environment. General Dynamics Corporation excels in delivering comprehensive support services, establishing long-term relationships with clients.
The expansion of the Airborne SATCOM System market relies on several key developments. Second, advancements in the Ka-Band frequency segment, expected to reach USD 3,553.3 million by 2033, reflect a shift towards higher bandwidth capabilities. This trend is crucial for meeting the demand of various applications, particularly in fixed-wing aircraft and rotary-wing aircraft segments. However, the market faces risks, primarily regarding supply chain disruptions affecting component availability. Limitations in the procurement of essential parts could delay the deployment of new installations and retrofits, impacting overall growth. Thus, while the market outlook remains positive with a projected CAGR of 6.5%, these factors will play a vital role in determining the trajectory towards USD 9,911.6 million by 2033.
By Component: Antennas, Transceivers and RF Units, Modems and Routers, Radomes, Others (Antenna Controllers, Power Supplies, Installation Kits)
By Frequency Band: Ku-Band, Ka-Band, L-Band, X-Band, UHF, Multi-Band, Others (S-Band, Q/V-Band)
By Installation Type: New Installation, Retrofit
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Airborne SATCOM System market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 6.5% from 2026 to 2033 |
|
Revenue Unit |
USD million |
|
Segmentation |
By Component, Platform, Frequency Band, Installation Type, and Region |
|
By Region |
North America (By Component, Platform, Frequency Band, Installation Type, and Country)
|
|
Europe (By Component, Platform, Frequency Band, Installation Type, and Country)
|
|
|
Asia Pacific (By Component, Platform, Frequency Band, Installation Type, and Country)
|
|
|
South America (By Component, Platform, Frequency Band, Installation Type, and Country)
|
|
|
Middle East and Africa (By Component, Platform, Frequency Band, Installation Type, and Country)
|
Find answers to common questions about this report
The Airborne SATCOM System market size was valued at USD 5,973.7 million in 2025.
The market is projected to grow at a CAGR of 6.5% during the forecast period from 2026 to 2033.
The North America Airborne SATCOM System market size is estimated to reach USD 3,530.5 million by 2033.
The leading segment in the Airborne SATCOM System market is Fixed-Wing Aircraft, with a projected value of USD 4,919.1 million by 2033. This segment surpasses others in terms of revenue generation within the platform category.
Growth in military spending significantly influences demand for advanced airborne communication systems. The increasing deployment of unmanned aerial vehicles (UAVs) further fuels innovation in antenna technologies, aligning with market trends emphasizing low size, weight, and power requirements.
North America holds the dominant share of the Airborne SATCOM System market, with a value of USD 3,530.5 million in 2033, representing 38 percent of the total market.
The increasing demand for versatile airborne communication solutions, particularly in the rotary-wing aircraft segment, significantly favors adoption. This segment is projected to grow at a compound annual growth rate (CAGR) of 5.4 percent through 2033, driven by investments in advanced transceiver and RF unit technologies.
The Airborne SATCOM System market is estimated to reach a valuation of USD 9,911.6 million by 2033.
Key players operating in the Airborne SATCOM System market include Honeywell Aerospace Inc., RTX Corporation, Thales S.A., Viasat, Inc., L3Harris Technologies, Inc., General Dynamics Corporation, and Elbit Systems Ltd.
The rotary-wing aircraft segment is projected to reach USD 2,392.7 million by 2033, reflecting a compound annual growth rate (CAGR) of 5.4 percent.
The analysts below cover Aerospace and Defense research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
Tracking ceramic matrix composite adoption in high-bypass aero engines requires strict attention to material qualification cycles and FAA airworthiness testing milestones. The MetaStat Insight team provided a detailed timeline of silicon carbide fiber manufacturing capacity and commercial foundry lead times. Having clear visibility into upstream thermal barrier coating supply helped us stress-test our long-term component procurement strategy.
Transitioning ultra-class mining haul trucks to alternative power requires concrete data on remote hydrogen refueling infrastructure economics. The report evaluated megawatt-scale electrolyzer installation expenses, onsite storage safety mandates, and heavy-duty fuel cell stack degradation under continuous duty cycles. That technical rigor helped our engineers benchmark realistic total operating cost horizons for off-highway fleet decarbonization.
Enterprise zero-trust network rollouts are often slowed down by multi-cloud transit latency and proprietary hardware retirement schedules. This study provided realistic total cost of ownership models comparing cloud-delivered security edge solutions against traditional hardware refreshes. The analysis of contract renewal lengths and software maintenance fees gave us clear visibility into enterprise replacement cycles over the next three to five years.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950