
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Air Valves Market Size, Share, By Application (Irrigation Systems, Waterworks, Mining Operations, Wastewater Treatment, Industrial Processes), By End Users (Agriculture Sector, Municipal Water Authorities, Mining Industry, Industrial Manufacturing), By Sales Channel (Direct Sales, Distributors, Online Sales), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-3488
Published
November, 2026
Pages
277 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
Market Valuation: Valued at $517.7 Million in 2025, projected to reach $901.5 Million by 2033 at a 7.2% CAGR.
Dominant Segment: The irrigation systems segment leads the market, driven by increasing investments in agricultural technologies and the need for efficient water management.
Geographic Lead: North America holds a significant market share of 30.6% in 2025, with the US expected to maintain its leadership position in 2026 due to ongoing infrastructure investments.
What's Inside: The report provides a comprehensive analysis of the Air Valves market, covering competitive landscapes, market dynamics, and detailed forecasts from 2026 to 2033.
End-User Insights: The agriculture sector is a key driver of demand for air valves, particularly for irrigation applications, reflecting a shift towards modernized and efficient water usage practices.
Market Challenges: Price sensitivity among municipal water authorities poses a barrier to adoption, impacting procurement decisions and slowing the uptake of advanced air valve solutions.
Choose Your License
Global Air Valves Market
The global Air Valves market was valued at USD 517.7 million in 2025 and is projected to reach USD 901.5 million by 2033, growing at a CAGR of 7.2% over the forecast period.
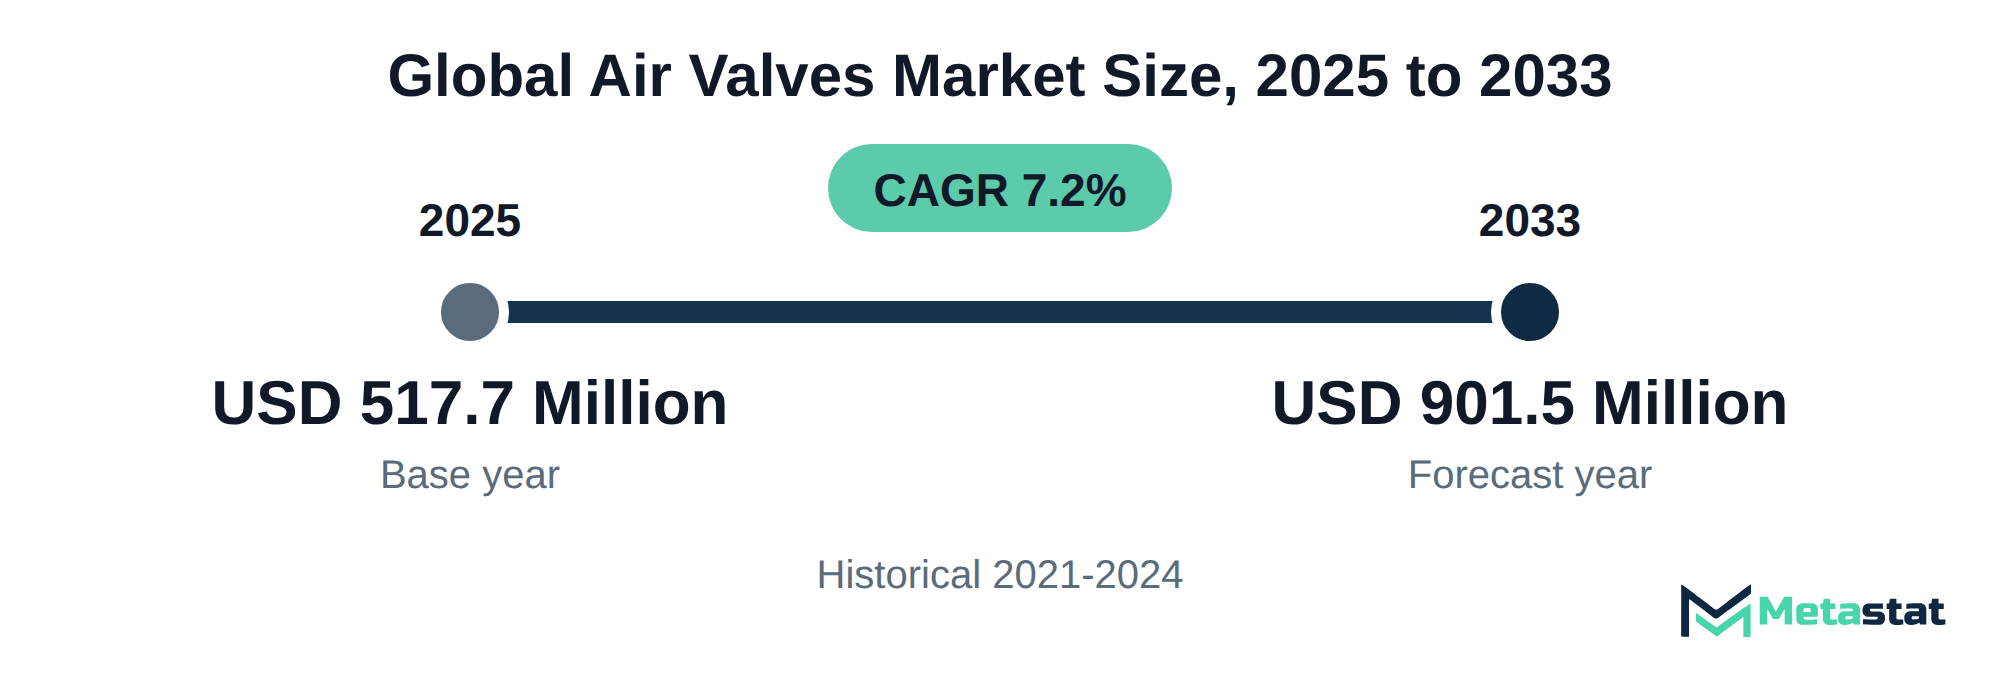
The Air Valves market encompasses a range of products designed to manage the flow of liquids and gases, primarily within water supply, wastewater treatment, and irrigation systems. Buyers invest in these solutions to enhance operational efficiency, ensure safety, and comply with regulatory standards. Applications in agriculture and municipal water authorities drive demand, which shows how important air valves are to infrastructure and industrial processes.
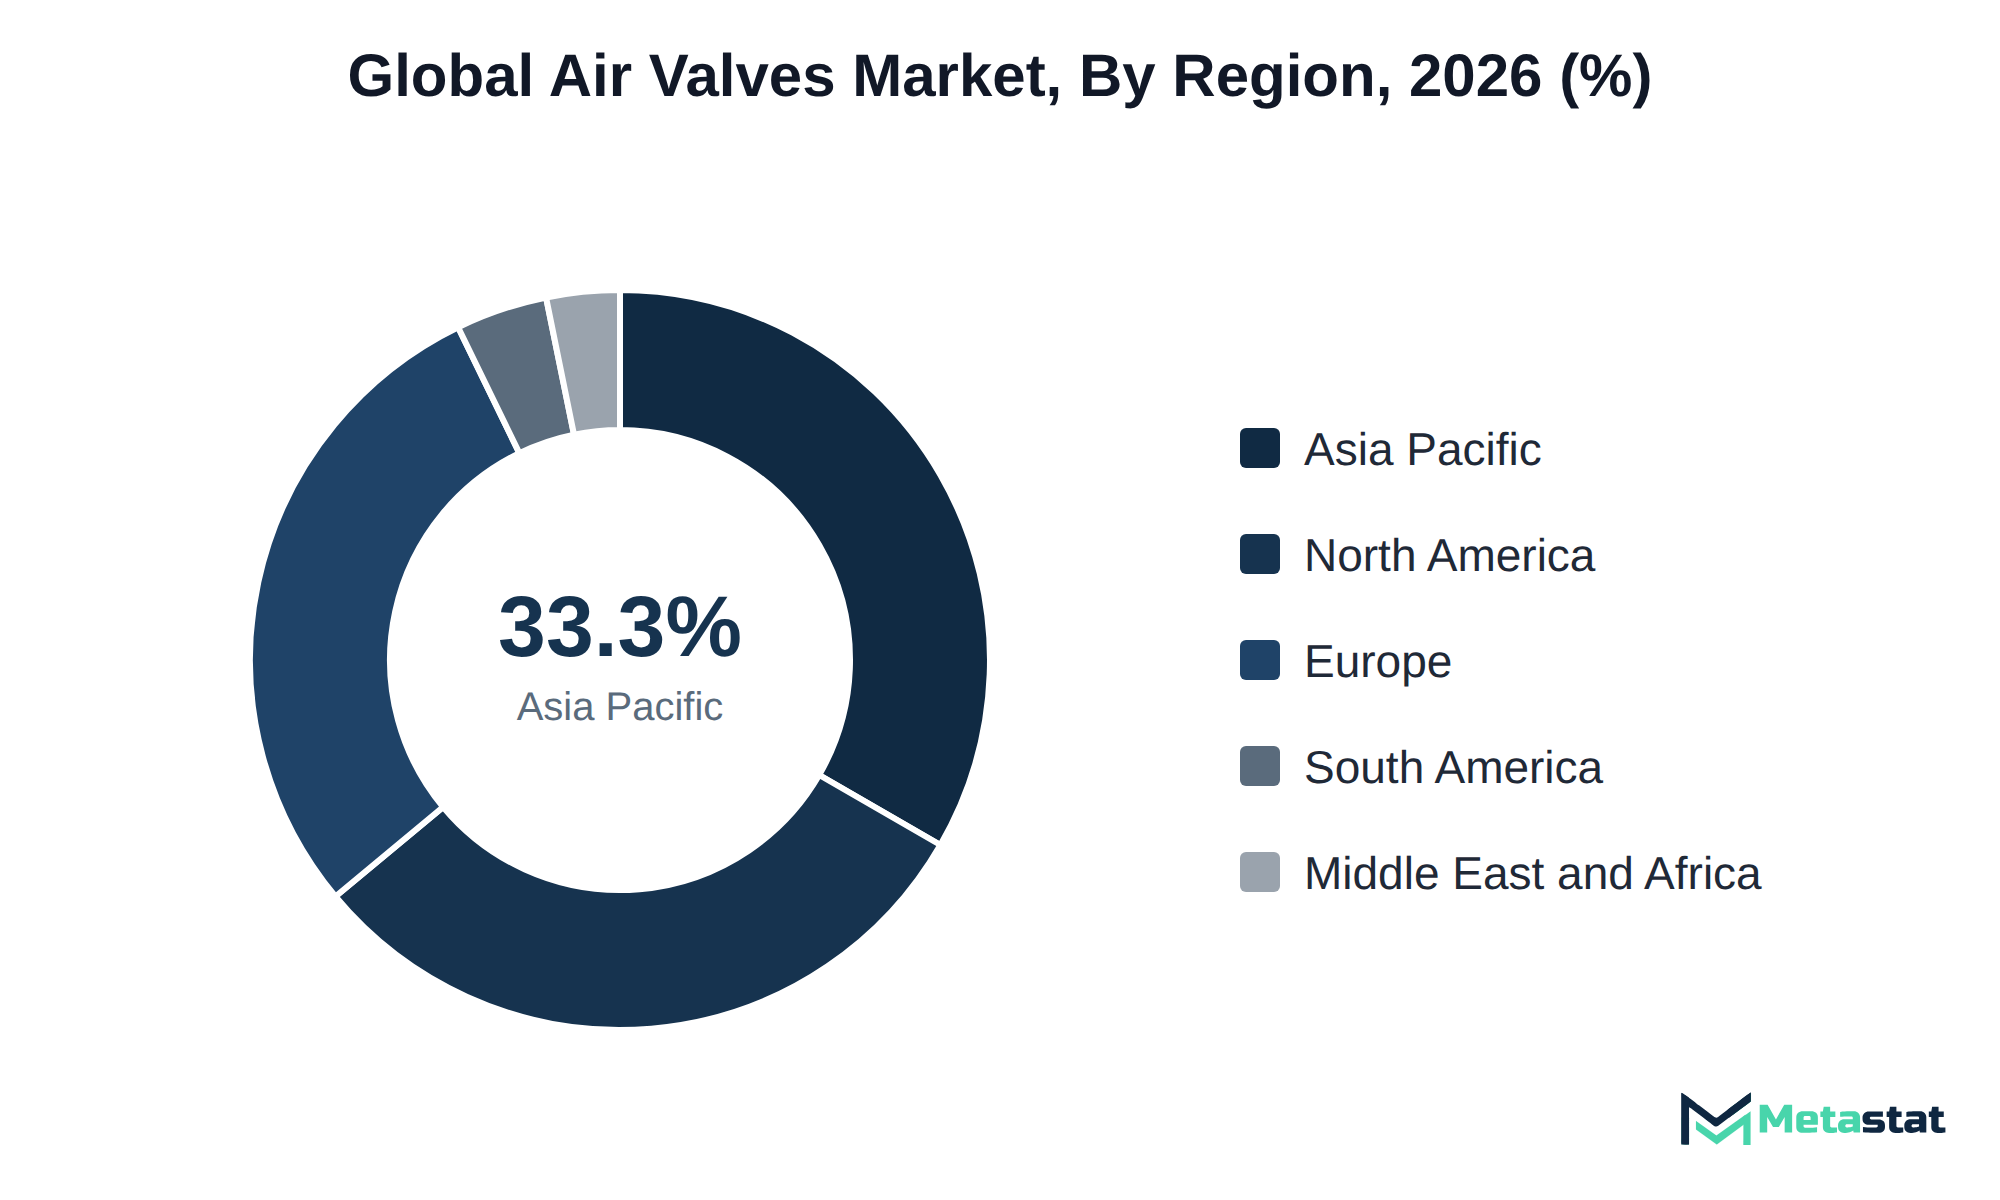
Growth within the market is fueled by increasing investments in water infrastructure and rising demand for efficient water management systems. The irrigation systems segment holds the highest market value, which shows how much agricultural applications depend on air valves. North America holds 30.6% of the market in 2025, with the US leading in 2026. The Asia Pacific region follows closely, capturing 33.3% of the market share, indicating significant growth potential.
Technological advancements and the need for sustainable practices drive market expansion, while increasing awareness of water conservation further stimulates demand. The ongoing shift toward automated and smart systems in agricultural and municipal applications reinforces the necessity for advanced air valve solutions. Consequently, stakeholders in the market are positioned to capitalize on these trends, exploring opportunities for growth in a competitive environment.
The Air Valves market serves various industries, addressing the demand for efficient fluid management solutions. Buyers invest in air valves to enhance system performance, ensure safety, and comply with regulatory requirements. This investment is particularly significant within the municipal water supply sector, where reliable and efficient operation is critical for infrastructure sustainability and public health.
Growth in the market is driven by the increasing demand for efficient irrigation systems, particularly in the agriculture sector. Asia Pacific follows closely, accounting for 33.3% of the market share, reflecting the region's rapid industrialization and urban development that enhances the need for advanced water management solutions.
Investment in the Waterworks segment, which is projected to reach USD 185.8 million by 2033, highlights the commitment to improving municipal water supply systems. The need for modernized infrastructure, along with the rising focus on sustainable practices, drives market expansion. These factors collectively position the Air Valves market for significant growth in the coming years.
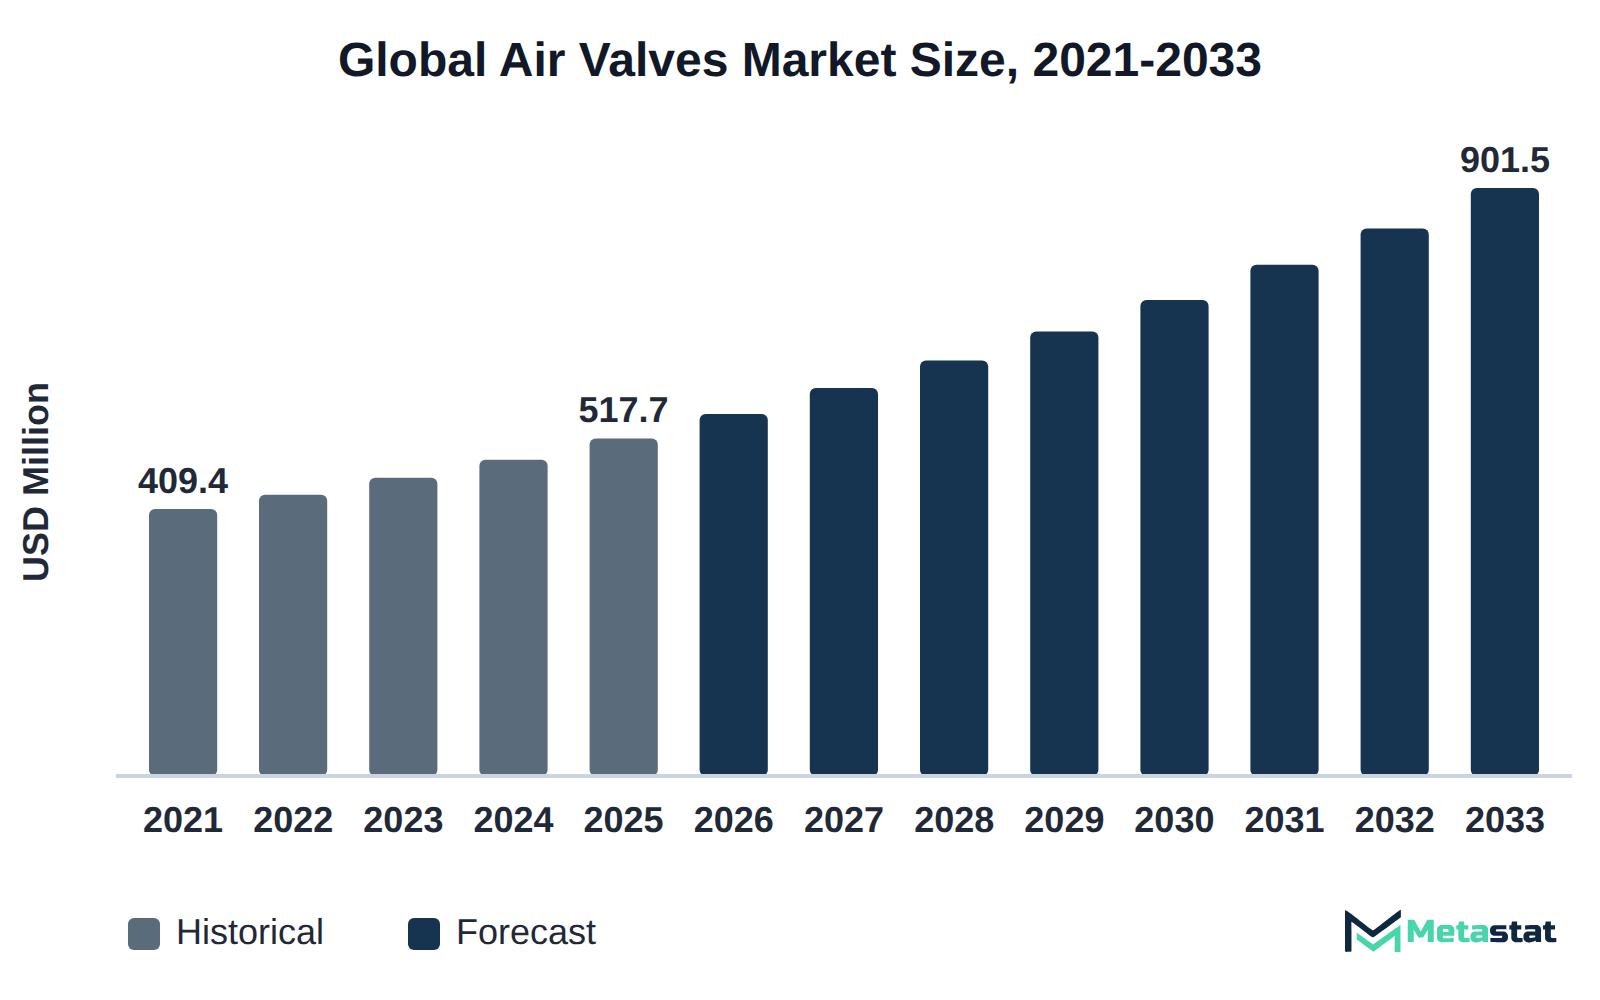
Transitioning from mechanical air valves to IIoT-connected combination air valves transforms maintenance practices within the Air Valves market. This shift allows for predictive maintenance, enhancing operational efficiency and reducing downtime. The integration of IIoT technology enables real-time monitoring of valve performance and system health, facilitating proactive maintenance strategies that prevent unexpected failures.
The irrigation systems application segment is projected to experience growth from USD 146.2 million in 2026 to USD 239.5 million by 2033, reflecting a compound annual growth rate of 7.3%. This growth stems from the increasing adoption of smart technologies in agriculture and other sectors reliant on irrigation systems. IIoT-connected valves contribute to this trend by providing valuable data that supports better decision-making regarding resource management and maintenance schedules.
The market adopts these advanced technologies, and suppliers of air valves benefit from increased demand for IIoT-connected solutions. The ability to offer enhanced functionality and reliability positions manufacturers favorably in a competitive landscape, driving investments in R&D and innovation. Ultimately, the transition toward IIoT-connected combination air valves improves product offerings and aligns with broader industry trends toward automation and digitalization.
The rehabilitation of global water infrastructure directly influences procurement cycles for the Air Valves market. Increased investments in waterworks, particularly in regions including North America and Europe, drive higher demand for air valves. Municipal water authorities, projected to reach a market value of USD 325.9 million by 2033, are central to this surge in demand. The need for efficient and reliable air valves becomes essential for maintaining the integrity of aging systems and ensuring compliance with new regulatory requirements. Trenchless pipeline rehabilitation is one method used to renew aging water networks without full excavation.
Buyers in the Air Valves market engage in long-term contracts with suppliers, allowing for stable pricing and supply continuity. These contracts generally include terms that address bulk purchasing and delivery schedules, which are crucial for projects that span multiple years. The growth in demand for waterworks applications, with a compound annual growth rate (CAGR) of 7.5%, suggests that procurement strategies will evolve. Organizations prioritize partnerships with manufacturers that offer flexible payment terms and the ability to adapt to fluctuating market conditions.
Emerging technologies in the valves sector encourage buyers to seek suppliers who provide comprehensive service agreements, ensuring ongoing support during the lifecycle of their products. This trend reflects a shift toward weighing total value rather than initial purchase price. Buyers focus on long-term performance and operational efficiency as key factors in procurement decisions. Adopting such strategies is likely to enhance competition among suppliers while improving project outcomes for end users.
Evolving material specifications are reshaping demand for air valves in hydrogen transmission and corrosive environments. With the rise of hydrogen as an energy source, air valves exhibit enhanced durability and resistance to corrosion. This growth stems from an increased focus on sustainable practices and the adoption of hydrogen in agricultural applications.
Material specifications are critical in ensuring air valves withstand challenging operating conditions. The incorporation of advanced materials, including non-corrosive alloys and specialized coatings, enhances the performance and longevity of these components. Municipal water authorities, another key end-user group, anticipate higher demand for air valves with enhanced reliability in corrosive environments. As a result, the segment is expected to reach a market value of USD 325.9 million by 2033, supported by a compound annual growth rate of 7.7%.
Overall, the evolution of material specifications in the air valves market directly impacts operational efficiency and cost-effectiveness. Buyers prioritizing high-performance valves positioned to handle hydrogen and corrosive conditions secure a competitive edge, enabling them to meet increasing environmental regulations and sustainability goals. These strategic decisions shape market dynamics and stimulate growth across sectors.
The agriculture sector stands out as a significant driver of demand for automated air valves. This sector employs these valves extensively for irrigation systems, which are crucial for ensuring efficient water distribution. This growth is driven by the increasing focus on optimizing water usage and enhancing crop yields, prompting agricultural producers to invest in advanced irrigation technologies.
Municipal water authorities contribute to the robust demand for automated air valves, particularly in waterworks for municipal water supply. Investments in infrastructure upgrades and the need for reliable water supply systems create a favorable environment for the adoption of automated air valves. This trend results in improved efficiency, reduced water loss, and enhanced service delivery for urban populations. Water pipeline leak detection systems also support loss reduction by helping utilities locate leaks in distribution networks.
The mining industry represents another noteworthy end user, with a focus on ensuring effective water management in mining operations. The market value for automated air valves in this sector is expected to reach USD 30.3 million by 2033. The emphasis on maintaining environmental standards and operational efficiency leads to increased demand for these valves. The air valves market benefits from multiple industrial applications, driving its growth trajectory across key sectors.
Rising investment in agricultural technologies drives increased spending within the agriculture sector. The shift toward modern irrigation systems and efficient water management practices stimulates demand for advanced air valves. Agricultural producers prioritize water conservation and improved crop yields, leading to higher volumes of purchases. This trend reflects a significant growth opportunity, with the agriculture sector projected to reach a market value of USD 239.5 million by 2033, growing at a CAGR of 7.3% from 2026. The market benefits from these dynamics, enhancing overall prospects for air valves in irrigation applications, which align with emerging sustainability goals across agricultural practices.
The trend of modernization within this sector aligns with broader infrastructural improvements and increased regulatory focus on water efficiency. Buyers increasingly seek solutions that enhance productivity while minimizing environmental impact. This heightened awareness among municipal water authorities and agricultural stakeholders influences their purchasing decisions, further supporting market growth.
Technological advancements in automation significantly improve air valve performance across various industries. The integration of automated systems enhances operational efficiency and ensures precise control, optimizing fluid management processes. Electric valve actuators are one of the components that allow valves to be controlled automatically. Industries including municipal water authorities and industrial manufacturing increasingly adopt these systems to streamline workflows and reduce labor costs. Enhanced monitoring capabilities provided by automation facilitate real-time data collection, allowing for informed decision-making regarding maintenance and operations.
This shift toward automation directly influences demand within the Air Valves market. Businesses prioritize solutions that enhance productivity and reliability. The increased efficiency achieved through automation lowers operational costs and boosts overall output levels. The push for greater efficiency and reliability intensifies competition among suppliers and encourages innovation in air valve technologies.
Price sensitivity presents a significant barrier to adoption among buyers, particularly within the municipal water authorities segment. Heightened operational costs lead to slower uptake of advanced air valves, hindering infrastructure improvements and maintenance initiatives. Budget constraints limit the ability of these authorities to invest in updated systems, resulting in smaller orders or delayed replacements for aging installations. This situation creates a ripple effect across related sectors, affecting manufacturers that rely on consistent demand for air valves. The market experiences constraints in growth potential, particularly in urban areas where investment in water management systems is essential. In addition, this price sensitivity encourages several buyers to consider lower-cost substitutes, which do not meet the same performance standards as higher-end air valves. Demand for air valves therefore faces pressure, which points to a need for pricing models that match buyer capabilities and incentives.
Suppliers face significant challenges stemming from rising material costs, which directly impact profitability within the Air Valves market. These increased expenses, driven by fluctuations in raw material prices, particularly metals and plastics, escalate production costs. The agriculture sector, municipal water authorities, and the mining industry experience heightened scrutiny on budgeting and procurement strategies due to these financial pressures. In response, suppliers implement strategies including optimizing supply chain management and seeking alternative materials to mitigate costs. Several manufacturers invest in research and development to identify more cost-effective solutions without compromising quality. This proactive approach supports maintaining competitive pricing while addressing client expectations for reliability and performance. While the market continues to grow, suppliers with adaptable strategies are likely to enhance their market positions and financial stability despite the persistent challenges associated with material costs.
The irrigation systems segment demonstrates significant growth potential, driven by rising investments in agricultural technologies and sustainable practices. Increasing water scarcity and the need for efficient water management contribute to this upward trend. Agricultural buyers prioritize advanced solutions that enhance resource utilization, impacting procurement decisions. This focus on effective irrigation necessitates a shift toward high-performance air valves that support optimal system efficiency.
Investments in irrigation automation and related infrastructure facilitate the integration of innovative air valve technologies that improve operational efficiency. The air valves market benefits from this trend, catering to an expanding customer base within the agriculture sector. Suppliers that prioritize product development and align their offerings with the specific demands of irrigation systems gain a competitive advantage. This segment's growth presents ample opportunities for market players to enhance their portfolios and strengthen their positions in the agriculture sector.
The Global Air Valves market is segmented based on Application, End Users, and Sales Channel.
Irrigation air valves serve agricultural practices and municipal water management, facilitating effective water distribution and resource management. Increasing investments in modern irrigation techniques drive demand, particularly within the agriculture sector, where efficient water usage is critical. Regulatory frameworks emphasizing water conservation stimulate growth in this segment. In comparison to other segments, including Waterworks, which has a projected CAGR of 7.5%, the irrigation segment maintains a competitive growth rate, highlighting its significance in the overall dynamics of the Air Valves market. The focus on sustainability and technological advancements further enhances its appeal among end users, positioning it favorably against other applications.
Waterworks (Municipal Water Supply) segment is estimated to reach USD 185.8 million by 2033, at a CAGR of 7.5% during the forecast period. This segment focuses on the supply of water to municipalities and public utilities, ensuring the availability of clean water to residential and commercial users. Municipal water authorities primarily employ air valves to maintain system pressure and prevent water hammer effects. Demand within this segment is driven by the pressing need for modernized water infrastructure and increased investment in sustainable water management. Compared to other segments, including irrigation systems, the Waterworks segment exhibits a slower growth rate, reflecting regulatory complexities and budget constraints faced by municipal agencies. The ongoing focus on compliance with water quality standards contributes to steady demand, while technological advancements in valve design offer potential for enhanced efficiency and reliability in municipal water supply systems.
The Mining Operations segment is expected to reach USD 30.3 million by 2033. This segment primarily serves the mining industry, focusing on efficient liquid management in various mining processes. A notable driver for growth in this area stems from increased mining activities, particularly in emerging markets where demand for minerals and resources is rising. Compared to other segments, the Mining Operations segment exhibits a slower growth rate, with a compound annual growth rate (CAGR) of 7.1% for the Industrial Manufacturing segment, illustrating a lower demand trajectory. The specialized nature of air valves in mining applications often leads to higher pricing due to the requirement for advanced materials and technologies that withstand harsh environments. Overall, this segment reflects the ongoing trend of heightened investment in mining technology and operational efficiency.
Wastewater Treatment segment is projected to grow at a CAGR of 8% during the forecast period. This segment focuses on managing and treating wastewater generated from various sources, including industrial, residential, and municipal activities. Municipal water authorities are significant end-users, relying on effective wastewater treatment systems to ensure compliance with environmental regulations. Demand for air valves in this segment is driven by increasing regulatory scrutiny concerning wastewater quality and rising awareness of sustainable water management practices. Compared to other segments, including Waterworks (Municipal Water Supply), which is expected to grow at a CAGR of 7.5%, the Wastewater Treatment segment exhibits a faster growth trajectory. This growth shows the sector's importance for public health and environmental standards, and it significantly affects investment in infrastructure and technology.
Industrial Processes use air valves to regulate and control the flow of gases and liquids in various manufacturing environments. This segment serves industries including chemical processing, food and beverage, pharmaceuticals, and petrochemicals, where precise fluid management is essential for operational efficiency. Sanitary valves serve flow control needs in the food and beverage and pharmaceutical settings within this segment. Demand within this segment stems from ongoing technological advancements aimed at enhancing automation and process efficiency. Compared to other segments, the Industrial Processes segment encounters unique challenges related to stringent regulatory compliance and the need for higher safety standards. These factors contribute to a differentiated pricing structure, with industrial applications often demanding more specialized and costly solutions. This segment stands out because it helps maintain production quality and reduce downtime, which reflects a growing focus on operational reliability across the air valves market.
This segment serves agricultural producers, focusing on efficient irrigation and resource management. Increasing investments in modern agricultural practices drive demand for air valves, particularly in irrigation systems. The need for reliable and innovative solutions to optimize water usage distinguishes this segment from others. With a higher growth rate compared to the broader market, the Agriculture Sector benefits from advancements in technology and sustainable practices. Municipal Water Authorities typically prioritize cost savings and regulatory compliance, impacting their purchasing decisions differently. Air valves ensure the effective operation of irrigation systems, enhancing agricultural productivity and sustainability.
Municipal Water Authorities segment is estimated to reach USD 325.9 million by 2033, at a CAGR of 7.7% during the forecast period. This segment includes water and sewage utilities responsible for the supply and management of water resources, focusing on the distribution and treatment of municipal water. Significant investments in infrastructure upgrades drive demand in this segment, reflecting a rising focus on improving water quality and ensuring reliable access to essential services. Compared to other segments, this segment experiences strong growth, supported by increasing urbanization and regulatory pressures to enhance water supply systems. In contrast, segments like Mining Operations exhibit slower growth due to their niche applications and limited buyer pool. The ongoing commitment to sustainable water management practices positions Municipal Water Authorities as a critical driver within the air valves market, reflecting the growing prioritization of efficient water management solutions.
This segment finds application in various processes involving the extraction and processing of minerals, where air valves facilitate the control and regulation of air and gas flow. Increased regulation of safety standards and environmental compliance drives demand for reliable and efficient air valves in mining operations. The segment demonstrates a slower growth trend compared to others, with less emphasis on mining automation and smart technologies. Buyers within this segment prioritize performance and durability, which leads to higher operational costs. In contrast, segments including Municipal Water Authorities experience faster growth due to heightened investments in automation, highlighting the differing dynamics at play in the market.
The Industrial Manufacturing segment is projected to grow at a CAGR of 7.1% during the forecast period. This segment encompasses the production processes that apply air valves for regulating fluid dynamics, primarily in manufacturing operations across various industries. Key users include companies in sectors including automotive, aerospace, and consumer goods, all of which require precise control of air and fluid management in their production lines. Increasing automation efforts drive demand within this segment, leading to enhancements in efficiency and productivity. Compared to the Agriculture Sector and Municipal Water Authorities segments, which have higher CAGRs of 7.3% and 7.7% respectively, the Industrial Manufacturing segment experiences relatively stable growth. This stability contrasts with fluctuations in demand observed in other segments, influenced by economic cycles and varying levels of infrastructure investment. The market landscape indicates that industrial applications remain foundational in air valve usage, ensuring operational efficiency across multiple manufacturing environments.
Direct Sales segment is valued at USD 149.5 million in 2026 and is projected to reach USD 227.9 million by 2033, at a CAGR of 6.2% during the forecast period. This segment serves various industries, primarily facilitating the direct purchase of air valves by end users including municipal water authorities and agricultural sectors. Increasing demand for efficient water management solutions drives this segment, particularly among buyers prioritizing reliability and performance. Compared to other sales channels, Direct Sales typically experiences slower growth due to competitive pricing strategies employed by distributors. The emphasis on personalized service and technical support in direct sales differentiates it from distributor channels, which focus on bulk transactions and lower prices, impacting buyer choices in the market.
Distributors segment is estimated to reach USD 558.2 million by 2033, at a CAGR of 7.5% during the forecast period. This segment facilitates the supply of air valves to various end users, including municipal water authorities and the agriculture sector. The growth in demand for air valves, driven by increasing water management needs, supports the expansion of this segment. Unlike other sales channels, distributors are positioned to offer a wider range of products and provide efficient logistics, thereby enhancing accessibility for buyers. Competitive pricing strategies employed by distributors contribute to attracting a larger customer base, particularly in markets sensitive to pricing. While the distributors segment experiences healthy growth, it operates in a landscape that requires continuous adaptation to market trends and demands. The air valves market benefits significantly from the effectiveness of this distribution channel.
Online Sales segment is expected to reach USD 115.4 million by 2033. This channel provides a convenient purchasing option for buyers across various sectors, facilitating access to air valves for applications in irrigation systems and municipal water authorities. The growing trend toward digitalization within the industry enhances the appeal of online sales, attracting a diverse customer base that seeks efficiency and ease of procurement. Demand for air valves through online platforms is driven by the increasing preference for quick and straightforward purchasing methods. Compared to traditional sales channels, online sales exhibit a slower growth trajectory with a compound annual growth rate (CAGR) lower than other segments. This difference highlights evolving buyer behaviors, where convenience is prioritized; however, barriers including limited product availability online restrict faster adoption. The market continues to expand as suppliers strengthen their online presence and offer a broader product selection to meet customer needs.
Based on geography, the Global Air Valves market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Strong demand for air valves in North America stems from the agricultural and municipal sectors, which employ these components for efficient water management and distribution. The agriculture sector relies heavily on air valves to optimize irrigation processes, reflecting a growing trend toward sustainable farming practices. Municipal water authorities play a crucial role in maintaining waterworks infrastructure, driving the need for reliable and durable valves. North America is projected to reach USD 277.4 million by the end of 2033, representing a 30.6% share of the global market in 2025. Continuous investments in infrastructure upgrades and environmental regulations further enhance the market's growth prospects. The air valves market benefits from technological advancements that improve efficiency and reduce wastage, positioning it for significant expansion through the forecast period.
The Air Valves market in Europe benefits from strong demand driven by key sectors including waterworks and agriculture. Municipal water authorities play a crucial role in this market, with an estimated growth in their segment expected to reach USD 325.9 million by 2033. Countries including Germany, France, and the UK stand out due to their advanced infrastructure and regulatory frameworks that support sustainable water management practices. With a projected market share of 28.8% in 2025, Europe presents significant growth opportunities in applications including irrigation systems and wastewater treatment, which are anticipated to expand due to increasing investments in environmental sustainability and efficiency. The market dynamics reflect a commitment to improving water resource management across the region.
Rapid urbanization and industrial growth in Asia-Pacific drive significant demand in the Air Valves market. The region's infrastructure improvement initiatives enhance the need for efficient water management systems, particularly in countries like China and India. Municipal water authorities increasingly focus on upgrading facilities to ensure secured water supply, resulting in a projected increase in related investments. Agriculture in Southeast Asia further supports the market through rising mechanization and modern farming techniques, which require advanced irrigation solutions. Australia and Japan, leading in technology adoption, emphasize sustainable practices in water usage, reinforcing the market's growth potential. The share of the global market in 2025 is 33.3%, highlighting the strategic importance of this region for future developments.
The Air Valves market in South America displays unique characteristics driven by the agricultural sector and municipal water authorities. Brazil and Argentina represent key markets, with Brazil's substantial agricultural activities creating significant demand for efficient water management solutions. Municipalities in Argentina seek to enhance water supply infrastructure, contributing to market growth. The region's market share stands at 4.00% in 2025. Challenges in infrastructure development and investment levels continue to impact adoption rates, particularly in rural areas. The market's expansion aligns with increasing government initiatives aimed at improving water distribution systems. These developments signify a growing recognition of efficient air valve applications across various sectors.
Demand for air valves in the Middle East and Africa stems from the agriculture sector and municipal water authorities. Rapid population growth and urbanization in countries like Saudi Arabia and the UAE drive investments in water infrastructure, significantly boosting demand for air valves. The agricultural industry in these regions relies on efficient irrigation techniques, enhancing the need for reliable valve solutions. South Africa's expanding mining sector contributes to market growth, leading to increased procurement of valves for operational efficiency. Ongoing investments in water management and agricultural improvements support future expansion in the market.
Companies in the Air Valves market adopt various strategies to differentiate themselves. Pricing, certification, customization, and service quality significantly influence buyer decisions. For instance, AVK International A/S emphasizes high-quality products tailored to meet specific agricultural and municipal needs. VAG GmbH positions its offerings with a strong focus on compliance with international standards, appealing to buyers prioritizing certification and reliability.
DeZURIK, Inc. provides innovative solutions that enhance operational efficiency, addressing the needs of industrial manufacturing clients. Val-Matic Valve & Manufacturing Corporation targets the wastewater treatment sector, offering products designed for durability and performance. This strategic diversity illustrates how companies in the market leverage their strengths to attract various customer segments.
Achieving this growth relies on several key developments within the market. The irrigation systems segment is expected to experience increased demand, driven by the agriculture sector's need for efficient water management solutions. The municipal water authorities segment is anticipated to expand significantly, with a target value of USD 325.9 million by 2033, supported by ongoing investments in infrastructural upgrades. Risks exist that could impede this growth. Economic fluctuations in global markets challenge investment levels in infrastructure, particularly in regions including South America, which represents a smaller share of the market at 4%. The air valves market will need to address these challenges and act on emerging opportunities to reach its forecast value.
By Application: Irrigation Systems, Waterworks (Municipal Water Supply), Mining Operations, Wastewater Treatment, Industrial Processes, Others (Fire Protection Networks, HVAC Systems, Desalination Plants, Oil & Gas Pipelines, Power Generation Cooling Systems)
By End Users: Agriculture Sector, Municipal Water Authorities, Mining Industry, Industrial Manufacturing, Others (Oil & Gas Companies, Power Utilities, Chemical Processing Plants, Marine & Shipbuilding, Commercial Construction)
By Sales Channel: Direct Sales, Distributors, Online Sales
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Air Valves market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 7.2% from 2026 to 2033 |
|
Revenue Unit |
USD million |
|
Segmentation |
By Application, End Users, Sales Channel, and Region |
|
By Region |
North America (By Application, End Users, Sales Channel, and Country)
|
|
Europe (By Application, End Users, Sales Channel, and Country)
|
|
|
Asia Pacific (By Application, End Users, Sales Channel, and Country)
|
|
|
South America (By Application, End Users, Sales Channel, and Country)
|
|
|
Middle East and Africa (By Application, End Users, Sales Channel, and Country)
|
Find answers to common questions about this report
The Air Valves market size was valued at USD 517.7 million in 2025.
The market is projected to grow at a CAGR of 7.2% during the forecast period from 2026 to 2033.
The North America Air Valves market size is estimated to reach USD 277.4 million by 2033.
The leading segment in the Air Valves market is the Agriculture Sector, with a projected value of USD 239.5 million by 2033. This segment demonstrates significant growth potential, driven by increasing demand for irrigation systems.
Rising investment in agricultural technologies drives increased spending within the agriculture sector, stimulating demand for advanced air valves. Technological advancements in automation significantly improve air valve performance, enhancing operational efficiency and ensuring precise control across various industries.
Asia Pacific holds the dominant share of the Air Valves market, accounting for 33.3 percent. This region's significant share reflects its robust industrial activities and demand across various applications.
Price sensitivity presents a significant barrier to adoption within the Air Valves market, particularly among municipal water authorities. This situation leads to smaller orders or delayed replacements for aging installations. Rising material costs further challenge profitability, prompting suppliers to optimize supply chain management and seek alternative materials to mitigate expenses.
Rising investments in agricultural technologies and a focus on sustainable practices favor adoption within the air valves industry. The need for efficient water management and improved crop yields drives agricultural producers to prioritize advanced air valve solutions, enhancing overall market prospects.
The Air Valves market is estimated to reach a valuation of USD 901.5 million by 2033.
Key players operating in the Air Valves market include AVK International A/S, VAG GmbH, DeZURIK, Inc., Aquestia (Includes ARI Flow), Val-Matic Valve & Manufacturing Corporation, Hawle Beteiligungsgesellschaft m.b.H., and American Manufacturing Company, Inc.
The analysts below cover Machinery & Equipment research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
INDUSTRY CONSULTANT - CHEMICALS & ADVANCED MATERIALS
Chemicals and Materials · Machinery & Equipment · Packaging
Amit Gadhekar Consultant for Chemicals and Materials at MetaStat Insight, directing sector-specific intelligence, research, and strategic consulting across global chemical and processing markets.
PRINCIPAL CONSULTANT - QUALITY SYSTEMS & COMPLIANCE
Electronics and Semiconductor · Machinery & Equipment · Professional Services
Omkar Phadtare is an Industry Consultant at MetaStat Insight, specializing in quality systems, regulatory compliance, and standards benchmarking to drive data-driven market intelligence and strategic industry research.
ENERGY & INFRASTRUCTURE INDUSTRY CONSULTANT
Automotive and Transportation · Electronics and Semiconductor · Energy and Power · Machinery & Equipment
Saurabh Vasant Ganvir consults for Energy & Infrastructure Industry at MetaStat Insight, specializing in renewable energy, solar EPC, and electric vehicle (EV) infrastructure markets.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
When planning edge sensor rollouts across refinery environments, generic IoT reports typically miss the harsh-environment certification bottlenecks. MetaStat Insight gave an objective evaluation of ATEX and Class 1 Division 2 hardware availability, along with realistic five-year maintenance cycle cost projections. The comparison of wireless mesh versus private cellular backhaul helped our team pressure-test network reliability models for remote processing facilities.
In the biological seed treatment space, registration timelines vary drastically between the European Union, Brazil, and North America. The MetaStat Insight research handled these cross-border regulatory barriers with genuine nuance, mapping commercialization pathways alongside historical field adoption rates. The segmentation between microbial strains and biochemical active ingredients was particularly well structured.
Our team was tracking whether regional recycling infrastructure could realistically absorb the growing volume of lithium iron phosphate batteries over the next decade. The report did a solid job separating announced hydrometallurgical plant capacity from active, permitted operational throughput. That distinction made the feedstock availability projections and regional recovery rate models far more credible than standard commercial overviews.
Explore related market intelligence reports worth reading alongside this one.